
USD continues to trade at stronger levels ahead of US CPI report
USD: A quick reversal of US mid-term elections losses
The US dollar has continued to trade at stronger levels overnight after rebounding strongly at the end of last week. It has resulted in the dollar index rising back above the 102.00-level after hitting a low of 101.10 on 4th November just after the release of the US mid-term elections results. The US dollar has quickly reversed all of its post-election losses (click here) encouraged by the release of further evidence showing that the US labour market continues to strengthen this year. The latest nonfarm payrolls report for October revealed that the US economy added 159k alongside upward revisions to prior months totalling 84k. There has been a clear pick-up in employment growth over the last three months which has averaged 137k/month compared to only 28k/month in the prior three months. For this year as a whole employment growth averaged 86k/month compared to only 10k/month in 2025. Stronger employment growth has shifted the Fed’s policy focus on to upside inflation risks.
The risk of second round inflation effects from the labour market still appears contained at the current juncture. The unemployment rate remains stable holding at just above 4.0% over the last four months. Stronger employment growth has been offset by a pick-up in the labour force preventing a tightening of labour market conditions. At the same time, average hourly earnings growth continues to remain close to year-to-date lows on an annual basis at 3.1% despite the stronger monthly reading of 0.4% in October. The breakdown of employment growth revealed that a strong increase in professional and business services jobs totalling 70k which may help to ease some concerns that AI adoption will significantly hold back employment growth.
Overall, the report provides further evidence that the US labour market is continuing to strengthen alongside stronger economic activity in recent quarters which will encourage the Fed to tighten policy further. However, with the risk of second round inflation effects from the labour markets still appearing contained the report does not significantly increase pressure on the Fed to speed up plans for hikes helping to dampen upward pressure on US yields and the US dollar. the Us rate market has moved to price back in a higher probability of the Fed hiking rates again in December as planned. There are currently around 20bps of hikes priced for December. The main risk of delay would be if US financial conditions continued to tighten significantly heading into year-end triggered by a deeper sell-off in AI-related investments. The Nasdaq composite index closed up by 1.1% on Friday but still declined for the fourth consecutive week by almost 5% for the week.
The other main development last week was the sharp adjustment lower for energy prices. The price of Brent fell by around 16% and has continued to weaken further at the start of this week. Lower energy prices have been encouraged by renewed investor optimism over the potential for a US-Iran deal. Investor optimism has been encouraged further over the weekend by comments from President Trump who told CNN that it is “highly unlikely” he will need to order fresh military strikes on Iran if talks show progress. He noted that “it depends on whether or not they sign a very strong agreement. The report added that diplomatic activity across the Middle East has increased sign the Us mid-term elections. On Friday, Qatar said that President Trump called Qatari Emir Sheikh Tamin bin Hamad Al Thani to discuss de-escalation, and a day earlier, Iran’s Foreign Minister Abbas Araghchi spoke with his counterparts from Saudi Arabia, the UAE, Oman, Pakistan, Kuwait, Jordan, Turkey, Cyprus and Qatar. However, US Secretary of State Macro Rubio sounded more cautious saying that “I wouldn’t say we’re on the verge of a breakthrough”. Further progress in talks will be required to sustain lower energy prices and help to ease upward pressure on the US dollar from a more protected energy price shock.
Market participants and the Fed will be watching closely for evidence of spillover effects from higher energy prices in the latest US inflation data released this week. Recent core CPI readings have surprised to the upside over the last couple of months putting pressure on the Fed to tighten policy. However, consensus expectations are looking for a softer core CPI print of 0.2%M/M in October. A reading that would help put a dampener on the US dollar’s upward momentum in the near-term. The US dollar appears to be running ahead of short-term yield spreads indicating that a hawkish surprise maybe required to maintain US dollar strength.
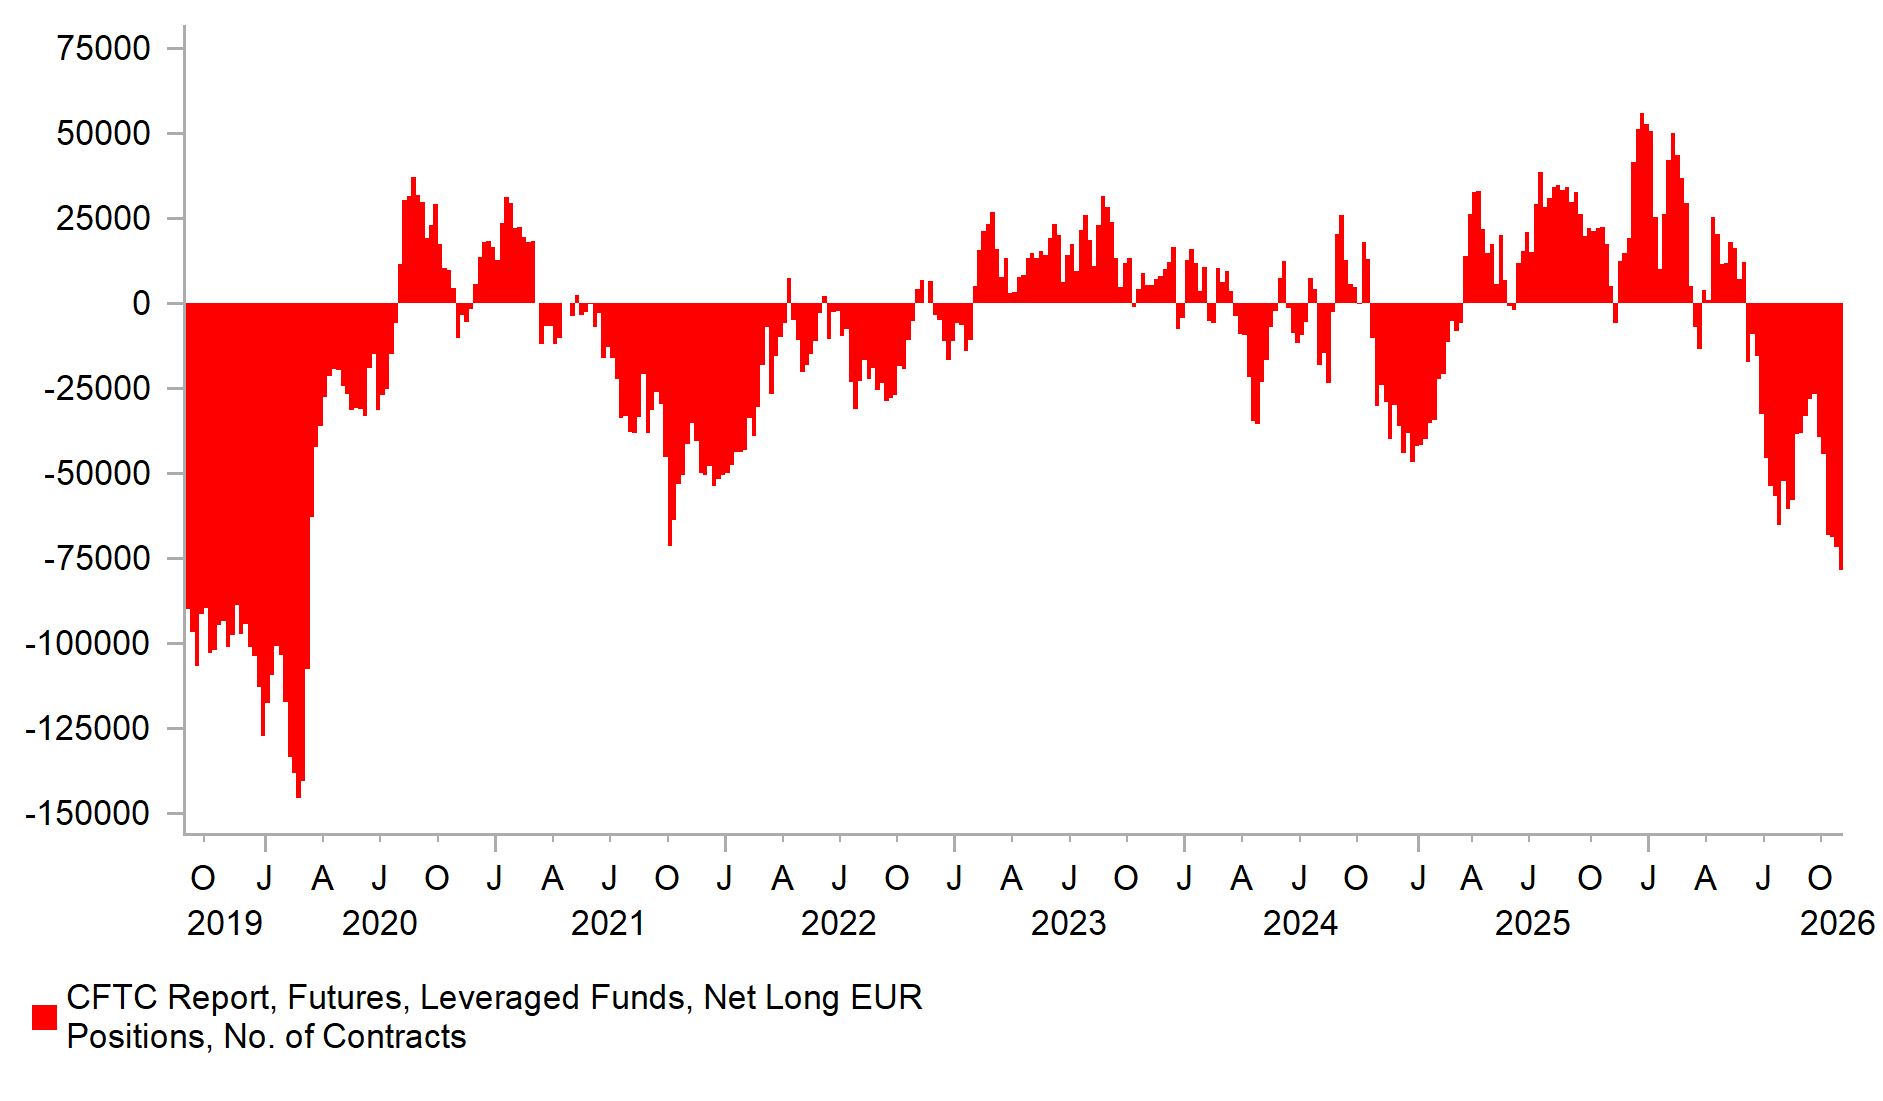
SPECULATIVE USD LONGS ARE HEAVILY CONCENTRATED AGAINST EUR
Source: MUFG Research, Macrobond, Bloomberg
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Forecast | Previous | Mkt Moving |
EU | 09:30 | Sentix Investor Confidence | (Nov) | 2.1 | 2.7 | ! |
US | 13:40 | FOMC Member Bowman Speaks | - | !! | ||
US | 15:00 | Fed Goolsbee Speaks | - | ! | ||
GB | 17:25 | BoE Gov Bailey Speaks | - | !!! |
Source: Bloomberg & Investing.com