
US dollar & energy prices correct lower after US mid-term elections
USD: Renewed optimism over US-Iran deal weighing on oil prices & US dollar
The US dollar has continued to weaken overnight extending the sell-off triggered by the US mid-term election results. The dollar index has now fallen by around 0.6% since the results were announced revealing a Blue wave as the Democrats decisively took control of Congress. The correction lower of the US dollar has also coincided with a further adjustment lower in US yields. The 2-year and 10-year have both fallen by around 8bps and 12bps respectively. The weaker US dollar and lower US yields have been encouraged by the sharp decline in the price of oil which is helping to ease market concerns over upside inflation risks. The price of Brent has fallen by around USD10/barrel since the US mid-term elections results were announced dropping back towards support from the 200-day moving average at around USD93.60/barrel. The price of oil had already been falling sharply at the start of this week and the mid-term election results have reinforced the sell-off. It leaves the price of Brent around 20% below the high from the end of last month.
The significant adjustment lower for the price of oil reflects renewed optimism over the potential for deal between US and Iran to end the conflict. The heavy election defeat for the Republicans driven by public anger over the rising cost of living triggered by the US-Iran war is encouraging speculation that it will put more pressure on the Trump administration to end the conflict sooner. President Trump has already told the FT that he has no immediate plans to strike Iran. Media reports earlier in the week also stated that the US and Iran are reviewing fresh proposals from mediators on how to resolve their differences and avoid a return to conflict. Iran’s president Masoud Pezeshkian has also said that his government has been granted more authority by Supreme Leader Mojtaba Khamenei to pursue peace talks including issues that had previously been considered “non-negotiable”.
Overall, the latest developments have clearly boosted investor optimism over the prospect of a deal to end the US-Iran conflict. A less prolonged energy price shock would help to dampen the case for a stronger US dollar. The main beneficiary amongst G10 currencies from the move higher in energy prices this year has been the Norwegian krone which has strengthened by around 2.4% against the US dollar and around 7.5% against the euro since the US-Iran conflict began. It would be the currency most at risk of a reversal lower if there was further evidence of progress towards a deal.
Another downside risk for the US dollar from the US mid-term election was the potential for the results to further undermine investor confidence in US AI-related investments in response to increased Democratic opposition to the ongoing AI build-out. However, those initial concerns did not prevent US equities from closing higher yesterday. The Nasdaq equity index finished up on the day by 1.4% although remains close to support form the 200-day moving average at around 27,970. Market attention at the end of this week will shift to the release of the last nonfarm payrolls report on Friday. Leading indicators of labour demand including yesterday’s ADP survey are signalling strengthening US employment growth which is confirmed on Friday could help to provide some support for the US dollar after the recent setback.
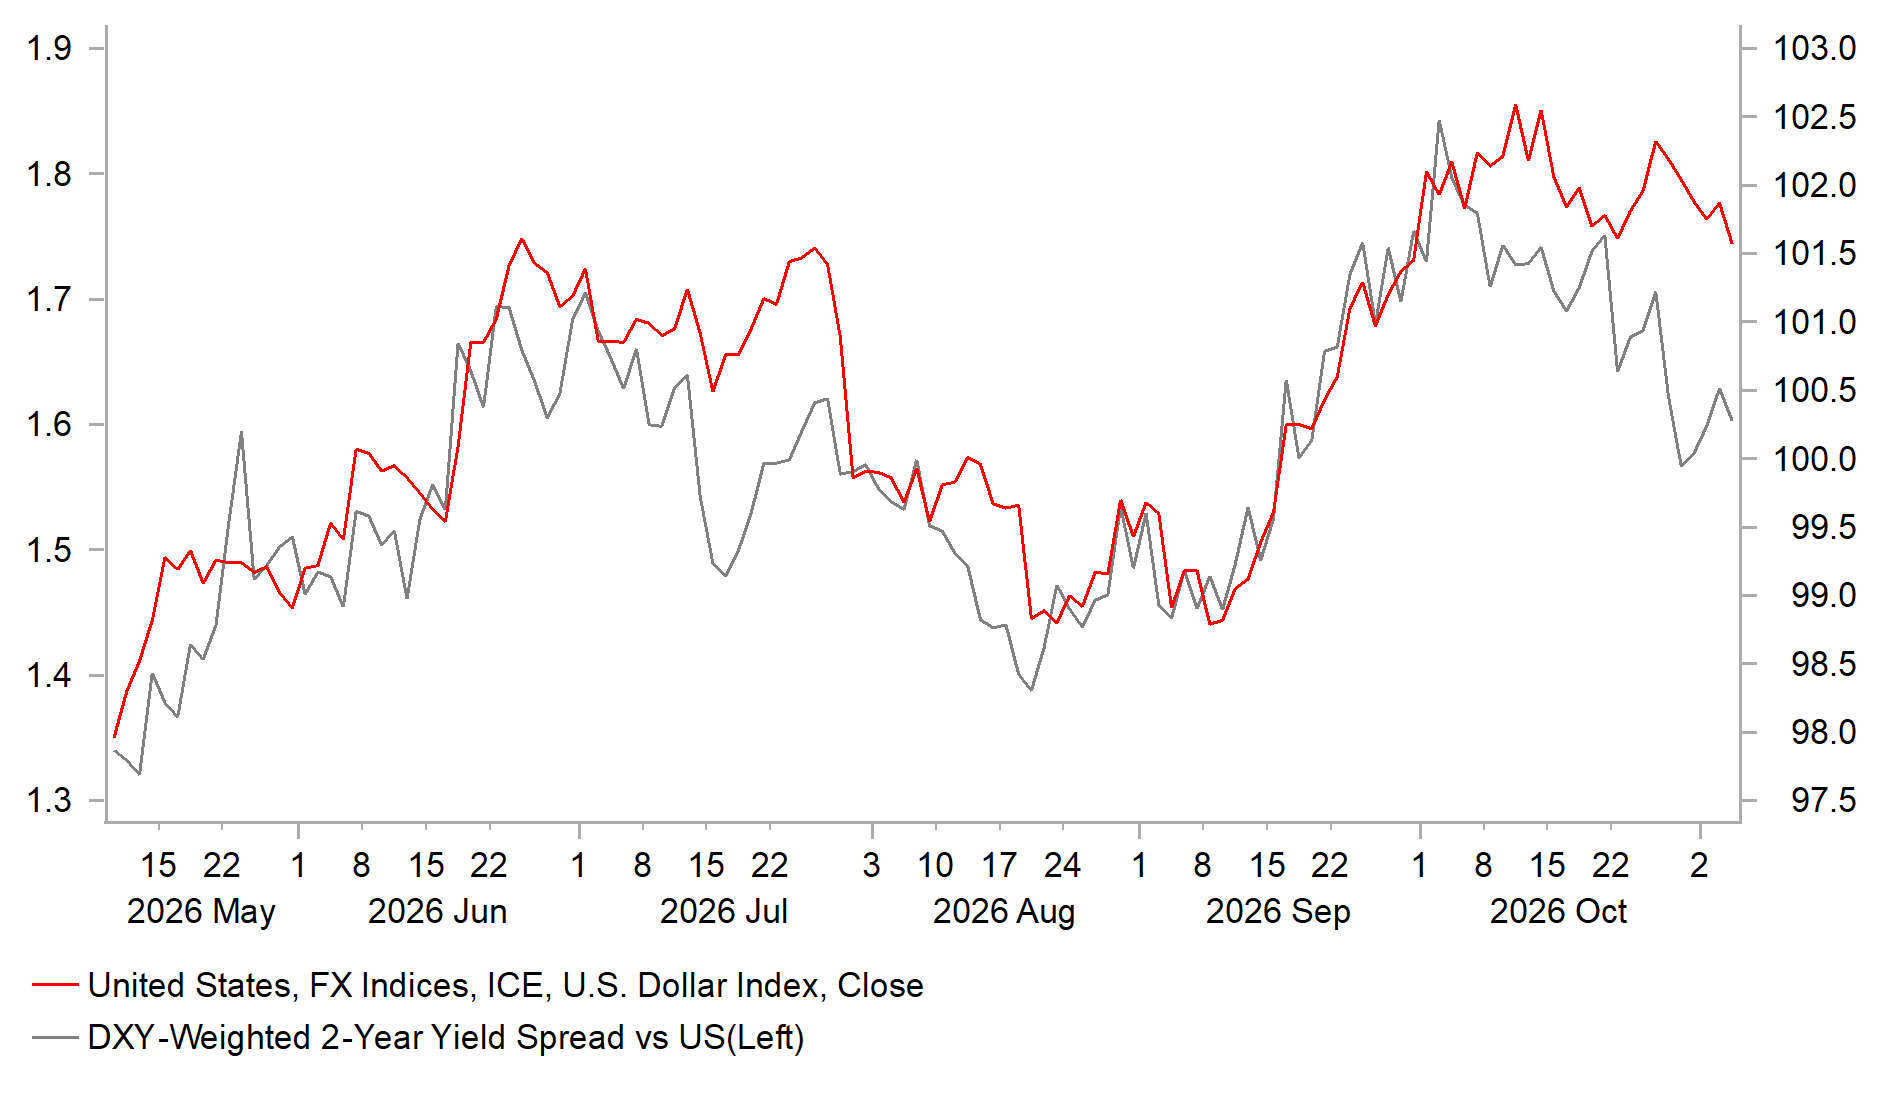
YIELD SPREADS MOVING AGAINST USD PRIOR TO MID-TERM ELECTIONS
Source: MUFG Research, Macrobond, Bloomberg
GBP: BoE to finally hike rates but provide cautious guidance update
The pound has benefitted from broad-based US dollar weakness after the Us mid-erm elections resulting in cable rising briefly back above 1.3500 yesterday. At the same time, the pound continues to trade close to year-to-date highs against the euro with EUR/GBP moving closer to the 0.8300-level. The outperformance of the pound over the past month has been encouraged by building optimism over stronger growth in UK and for the BoE to tighten policy in response to upside inflation risks. The BoE is finally expected to begin hiking rates today for the first time since the US-Iran conflict began. BoE officials including Governor Bailey have clearly stated recently that time is running out to keep looking through higher energy prices.
A 25bps hike is almost fully priced in today so the market reaction will be determined more by the updated forward guidance. We expect the BoE to signal that further tightening is likely to be required but not as much as currently priced in. the Uk rate market had been pricing in 4-5 hikes although that has been scaled back as the price of oil has dropped sharply this week. There are currently around 90bps of hikes priced by September of next year. It is moving towards our own forecast for 2 hikes from the BoE. While cautious guidance over further hikes could put a dampener on recent pound strength, we do not expect it to trigger a significant reversal lower for the pound. Please see our latest BoE preview report for more details (click here)
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Forecast | Previous | Mkt Moving |
NO | 09:00 | Interest Rate Decision | - | 4.50% | 4.50% | !! |
EU | 10:00 | PPI (YoY) | (Sep) | 10.9% | 8.2% | ! |
US | 10:30 | Challenger Job Cuts (YoY) | - | -19.9% | ! | |
GB | 12:00 | BoE Interest Rate Decision | (Nov) | 4.00% | 3.75% | !!! |
GB | 12:30 | BoE Gov Bailey Speaks | - | !!! | ||
CH | 12:40 | SNB Vice Chairman Schlegel Speaks | - | ! | ||
US | 13:30 | Initial Jobless Claims | - | 197K | 194K | !!! |
US | 13:30 | Nonfarm Productivity (QoQ) | (Q3) | 2.8% | 1.4% | !! |
US | 13:30 | Unit Labor Costs (QoQ) | (Q3) | 0.3% | 1.2% | !! |
CA | 15:30 | BoC Gov Macklem Speaks | - | !! | ||
EU | 15:40 | ECB's Lane Speaks | - | !! | ||
EU | 18:00 | ECB President Lagarde Speaks | - | !! |
Source: Bloomberg & Investing.com