
USD continues to trade at modestly weaker levels at start of the week
USD: What’s been driving the correction lower for the US dollar?
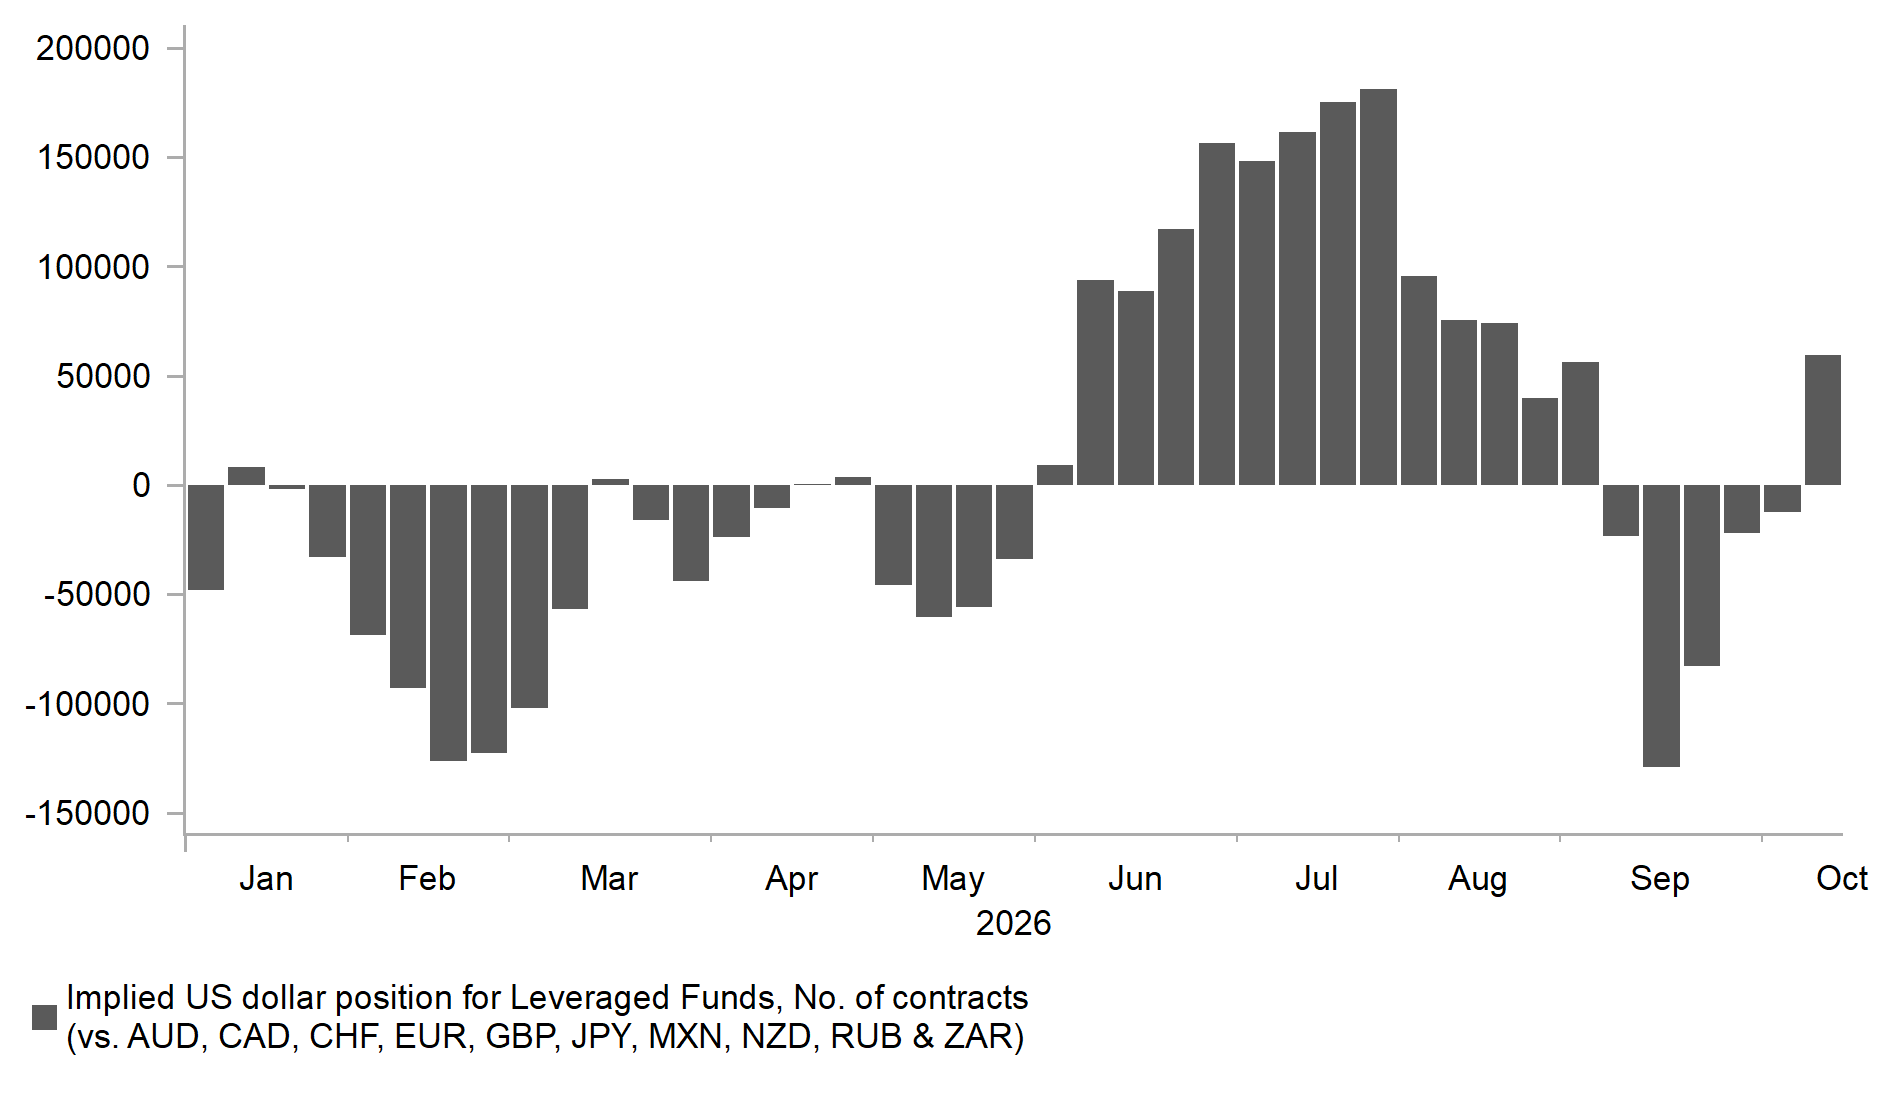
The major foreign exchange rates have remained stable overnight with the US dollar continuing to trade at modestly weaker levels following last week’s correction lower. The dollar index closed lower last week brining an end to four consecutive week of gains that had lifted it to a fresh year-to-date high of 102.95. It has since fallen back below resistance from the 200-week moving average which comes in at around 102.10. The last time the dollar index was consistently above the 200-week moving average was prior to President Trump’s “Liberation Day” tariffs announcement back in April 2025. The US dollar’s failure to extend its gains last week following the release of stronger US inflation data was disappointing and has likely encouraged some investors to trim long positions accumulated over the past month. Despite the stronger US inflation data, which further highlights the limited progress towards the Fed’s inflation objective, market participants have been reluctant to price in a more hawkish policy path. Market pricing for a back-to-back Fed rate hike later this month has fallen to only around 3bps after Fed Chair Kevin Warsh at the end of last week refrained from signalling a clear need for another increase so soon after last month’s initial hike.
At the same time, the US dollar’s pullback this week has coincided with a wobble in AI-related trades (click here). After reaching a fresh record high earlier this month, Bloomberg’s AI equity index has since fallen by around 9%. The correction has been even more pronounced in semiconductor and neocloud equity indices. The sell-off has been driven by a combination of factors, including renewed concerns that the scale of AI investment could ultimately result in oversupply. Furthermore, the growing need to raise capital to finance AI infrastructure is contributing to tighter financing conditions. Bloomberg has reported today that neocloud company Nscale is facing opposition to its IPO valuation target of about USD30billion. It was also reported over the weekend that Microsoft, one of their biggest customers, has pulled out of a UK data centre deal. The report could add to building investor concerns toward AI infrastructure companies building on top of last week’s reports about rising funding costs for CoreWeave. Nscale publicly filed for a Us listing on 18th September. Australian AI data-centre developer Firmus recently had to withdraw their plans for an IPO in early October after it failed to attract enough investor demand. The IPO plans had valued the company at roughly USD30 billion which would have made it one of the largest IPOs in Australin history.
In last their latest Global Financial Stability report released last week, the IMF warned that the consequences of an AI-related market correction could be felt globally, although some jurisdictions appear more vulnerable than others. Its analysis showed that advanced Asian equity markets exhibit the highest betas to a proxy for global AI equity returns, indicating greater sensitivity to fluctuations in AI-related sentiment. In contrast, equity markets in the euro area, the UK and most emerging economies display significantly lower betas. US financial markets have been a major beneficiary of strong foreign investor demand driven by AI-related optimism. Foreign investors purchased USD942 billion of US equities in the twelve months to July, while purchases of US corporate bonds increased sharply to USD452 billion over the same period. These sizeable inflows highlight how the USD has become increasingly tied to investors’ search for higher returns in US financial markets, rather than benefiting from its traditional safe-haven status. However, this dynamic also leaves the USD more exposed to a reversal if sentiment towards AI deteriorates.
LEVERAGE FUNDS HAVE BEEN REBUILDING LONG USD POSITIONS
Source: MUFG Research, Macrobond, Bloomberg
EUR/CNY: Social unrest in Europe & stronger growth in China
The other main developments over the weekend have been rising social unrest in Europe where protests in France spread to other countries including Italy. However, the initial market impact has been muted at the start of this week with the euro continuing to trade close to levels from the end of las week at just above 1.1200 against the US dollar. The social unrest will reinforce investor concerns over the outcomes from upcoming elections next year in France and Italy. The probability of RN leader Le Pen becoming president have continued to rise hitting around48% according to Polymarket encouraged by further evidence of growing public unease with the current political status quo. She stated in a speech posted on X that the country was “held hostage, between violence and powerlessness”. She blamed the party of her far-left rival Jean-Luc Melenchon for trivializing violence. Adding that France “cannot, must not, and will never get used to such scenes”. We expect heightened fiscal and political risks in France to remain a headwind for euro performance heading into next year.
It was also revealed over the weekend that China’s economy performed better than expected in Q3 expanding by an annual rate of 4.5% up from 4.3% in Q2. The latest monthly activity for September also revealed stronger growth momentum heading into Q4. The annual rate of retail sales growth picked up to 1.1% in September from 0.4% in August. They were boosted by the Mid-Autumn Festival falling in September this year. Elsewhere, faster fiscal delivery helped to provide more support for growth with industrial production picking up to 5.5% in September. Stronger growth will reinforce market expectations for the renminbi to continue strengthening gradually.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
CA | 13:30 | CPI YoY | Sep | 3.2% | 3.0% | !!! |
US | 15:00 | NAHB Housing Market Index | Oct | 31.0 | 32.0 | !! |
CA | 16:30 | BoC Overall Business Outlook Survey | 3Q | -- | - 0.4 | !! |
Source: Bloomberg & Investing.com