
BoJ fails to meet hawkish market expectations
JPY: BoJ communications leaves yen vulnerable
We mentioned here yesterday that we felt the bar was low for the BoJ failing to meet the level of hawkish pricing in the rates market and that is what has unfolded today with the initial reaction to the decision to hike by 25bps to 1.25% underlining the risks that the BoJ could well fail to meet expectations of nearly 100bps (incl today’s hike) of tightening over the coming twelve months. But the trigger for the initial yen sell-off following the announcement at 3:54 BST does likely simply reflect the fact that recent speculation, including talk of the potential for 50bp moves, was overdone. Two factors look to have prompted the initial sell-off. Firstly, there was a 7-2 vote. This is not hugely surprising though. It’s well known that there are two hawks (Tamura & Takata) and two doves on the committee. Neither of the hawks voted for a 50bp hike (Takata had mentioned this in general as a possibility). Toichiro Asada and Ayano Sato dissented today. Asada dissented in June and Sato attended only her second meeting. Both were appointed by the Takaichi administration, likely for their reflationary leanings.
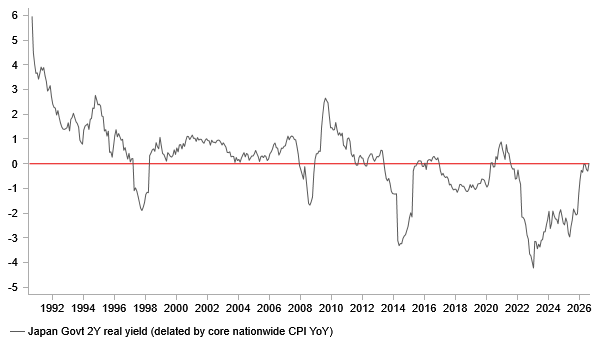
Secondly, the BoJ removed the description in the statement that real interest rates were “negative, mainly in the short-to-medium term zone” to “remained at low levels, mainly in the short-to-medium term zone”. This is really just the BoJ acknowledging facts – the move up in front-end rates has been notable (2yr JGB yield is 35bps higher since the last BoJ meeting) and with inflation currently below the 2.0% target the description of “low” rather than “negative” makes sense. We wouldn’t link that to an indication of altering intentions ahead. That was underlined by the fact that the BoJ maintained its view that “accommodative financial conditions are expected to be maintained” and therefore the bank “will continue to raise the policy interest rate and adjust the degree of monetary accommodation”.
The yen has started to recoup some of the initial losses following the start of Governor Ueda’s press conference. Ueda’s comments have been largely consistent with the initial communications, and he has repeated that there are upside risks to price stability, the monetary stance is still accommodative and that the BoJ expects to continue raising rates.
Perhaps most importantly he has stated that the “stage for policy conduct has changed” which would suggest the possibility for an altered pace of tightening ahead although Ueda did then add that the BoJ has no particular pace in mind. Still, that is not a denial that the pace of tightening may now have picked up. While there may be something to this comment it is not exactly explicit and Governor Ueda has probably intentionally kept this vague. We suspect this guidance is not going to be strong enough to convince the market that this was a clear signal of a faster pace of tightening is in place. In any case, rates pricing remains aggressive and hence the bar for triggering a further move higher in rates is high. Hence, some giveback from recent yen strength makes sense to us over the short-term. If broader US dollar sentiment remains favourable, USD/JPY has scope to grind further higher from here over the short-term.
BOJ TODAY ACKNOWLEDGED INTEREST RATES NO LONGER NEGATIVE
Source: MUFG Research, Macrobond, Bloomberg
GBP: BoE surprises markets with updated QT plan
There was only 2bps of hikes priced for the BoE announcement yesterday, so the unchanged policy announcement was no surprise. We wrote a review (here) yesterday and our key takeaway on monetary policy is that a rate hike is coming. Front-end rates did soften and that likely reflected the fact that the signalling of a rate increase in November was expected to be stronger. There were no clear explicit signals of an imminent hike but of the six who voted to maintain an unchanged stance, four indicated a hike may be required – Governor Bailey, Sarah Breeden, Clare Lombardelli and Dave Ramsden. Only the two uber-doves (Swati Dhingra and Alan Taylor) would likely oppose a rate hike if energy prices remain in the current vicinity through to the meeting on 5th November.
While the rate decision was expected, the updated QT plan was not. There has been a significant overhaul that contained three important elements that will help contain yields at the longer-end of the Gilt yield curve. Firstly, the BoE has paused all sales from its bond portfolio until April next year. Secondly, GBP 120bn worth of longer-dated Gilts, maturing beyond 2049, will be held permanently until maturity on the BoE’s balance sheet. Thirdly, GBP 146bn worth of Gilts maturing between 2035 and 2049 will be sold at a pace of GBP 20bn per year with these bonds sold directly to the government via the DMO rather than directly to the market via auctions as has been the case under QT so far. The balance, GBP 222bn, will be removed from the BoE’s balance sheet passively as the bonds mature on tenors out to 2034. This implies QT will be completed by September 2034.
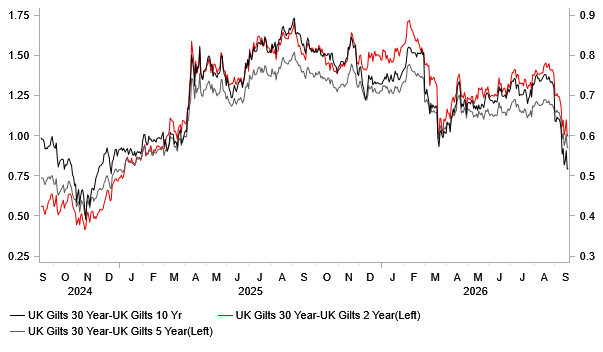
The active sales of GBP 20bn per year of Gilts maturing between 2035 and 2049 to the DMO rather than to the market is biggest impact here and the 30-year Gilt fell by 12bps yesterday. The government will have to issue of course to cover this but will likely issue shorter, more liquid tenors helping to improve investor sentiment at the long-end. In essence this is like the Scott Bessent buyback announcement in August that saw yields and the dollar fall. The pound fell yesterday but reduced risks to the Gilt market ahead of the budget on 28th October does also reduce to some degree a negative reaction. That’s pound positive. So the FX fallout is unlikely to be large on the back of this especially with a rate hike likely delivered in November.
30-YEAR GILT HAD BEEN OUTPERFORMING BEFORE YESTERDAY
Source: MUFG Research, Macrobond, Bloomberg
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
EZ | 09:00 | Current Account | (Jul) | 30.7B | 35.1B | ! |
EZ | 09:00 | ECB's 1-Year CPI Expectations | Aug | 3.1% | 2.9% | !!! |
EZ | 09:00 | ECB's 3-Year CPI Expectations | 2.8% | 2.7% | !!! | |
EZ | 10:00 | Construction Output (MoM) | (Jul) | - | -1.34% | ! |
EZ | 11:30 | ECB President Lagarde Speaks | - | - | - | !! |
US | 14:15 | Industrial Production (MoM) | (Aug) | 0.3% | 0.2% | !! |
US | 14:15 | Manufacturing Production (MoM) | (Aug) | 0.3% | 0.2% | !! |
US | 14:15 | Industrial Production (YoY) | (Aug) | - | 1.08% | ! |
US | 14:15 | Capacity Utilization Rate | (Aug) | 76.4% | 76.3% | ! |
US | 14:30 | Fed Governor Bowman Speaks | - | - | - | !!! |
US | 15:00 | US Leading Index (MoM) | (Aug) | 0.1% | 0.2% | ! |
US | 16:45 | Fed's Schmid Speaks | - | - | - | !! |
Source: Bloomberg & Investing.com