
USD’s renewed upward momentum remains firmly in place
USD: Faster Fed hikes & weak growth overseas adding to upward momentum
The US dollar has continued to strengthen at the start of this week building on top of the strong gains recorded last week. It has resulted in the dollar index hitting a fresh year-to-date high overnight at close to 103.50, and is now trading back above levels prior to President Trump’s’ Liberation Day’ tariffs announcement in April 2025. The renewed upward momentum in the USD has been driven primarily by an abrupt hawkish repricing of Fed rate hike expectations. Reflecting this shift, the 2-year US Treasury yield has rebounded by around 40bps from its low at the start of the week, moving back towards the year-to-date high of 4.96% reached on 29th September. Market participants have moved to price in a more aggressive Fed tightening cycle following the third consecutive upside surprise in US core CPI in October and a hawkish shift in Fed rhetoric. Fed officials have signalled that a faster pace of rate hikes may be required heading into the winter. As a result, the US rates market is now assigning a higher probability to three consecutive hikes in December, January and March, which would lift the effective Fed funds rate towards 4.6%.
One of the key events today will be comments from Fed Chair Kevin Warsh who is scheduled to give opening remarks at the Productivity and Jobs Task Force Conference at the San Francisco Fed. He will also moderate two panels and participate in a fireside chat. Market participants will be listening closely to see if he gives away any indication over how he is likely to react to the latest upside US inflation surprise. However, the main focus of discussions is likely to be on the outlook for productivity and labour market. We expect the discussions to support his optimistic outlook for stronger productivity growth which should allow the US economy to grow more strongly without creating inflationary pressure.
At the same time, the US dollar is deriving additional support from evidence of weaker growth outside of the US in particular in China. The latest monthly activity data revealed a broad-based slowdown in growth in October. The annual rate of retail sales growth slowed to 0.4% in October down from 1.1% in September. The annual rate of industrial production growth slowed to 4.8% in October down from 5.5% in September, and fixed asset investment slowed to -8.1%Y/Y YTD in October down from -7.2% in September. The NBS described the economy as “overall stable” and “extending a trend of renewing growth engines and improving its structure”. The October data will be closely scrutinized by top officials ahead of the Central Economic Work Conference which is usually held in the first half of December.
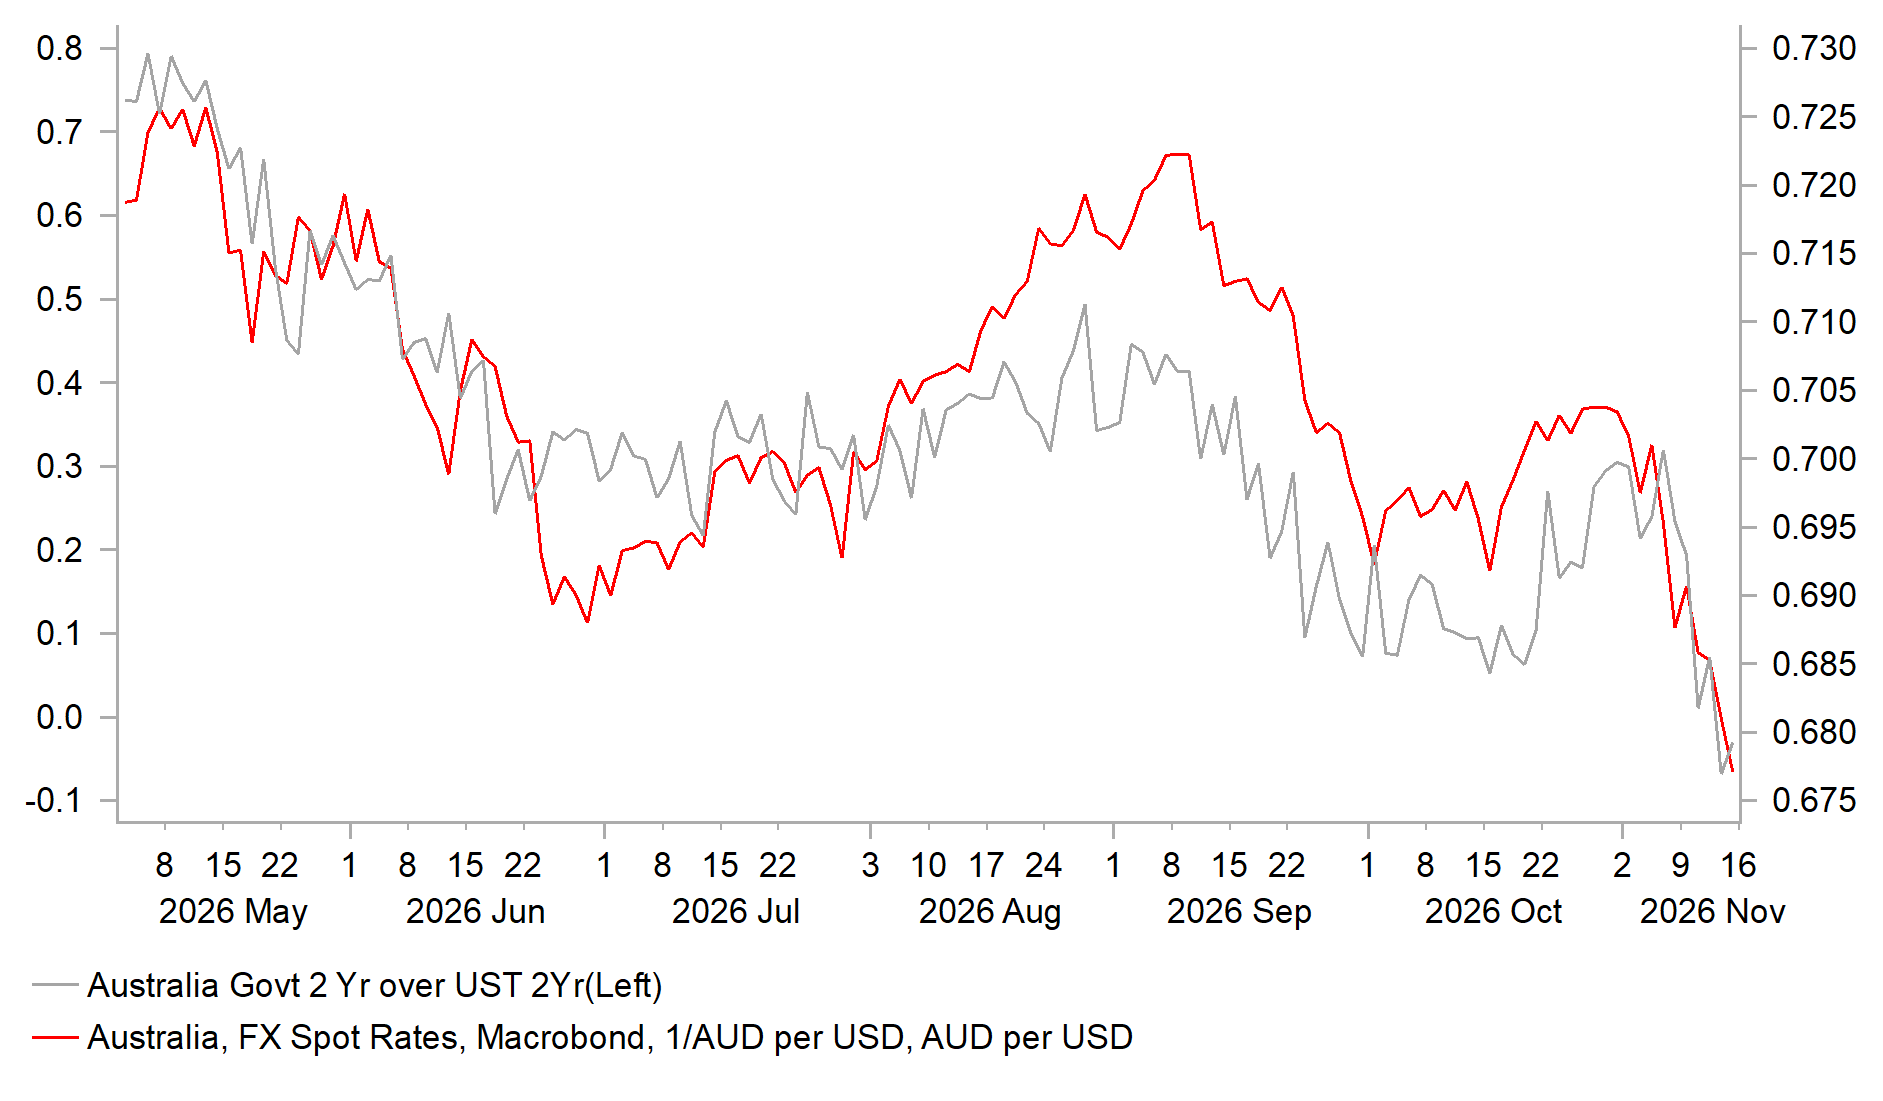
The economy remains on track to meet the government’s annual growth target of between 4.5-5.0%, but the loss of growth momentum will increase pressure on policymakers to provide more support for growth. It could also add to caution over allowing the renminbi to continue strengthening. China has already attempted to dampen upward momentum by raising the foreign exchange reserve requirement ratio from 4% to 6% which became effective on 15th November. Slower growth in China also to the recent headwinds facing the Australian dollar contributing to its underperformance this month when it has been the worst performing G10 currency. Please see our latest FX Weekly for more details (click here).
SHARP MOVE LOWER FOR AUD/USD BACKED BY YIELD DIFFERENTIALS
Source: MUFG Research, Macrobond, Bloomberg
JPY: Weakness in Japan GDP driven by temporary factors limiting impact
The yen has strengthened modestly supported both by more risk-off trading conditions overnight and heightened concerns over the risk of further intervention from Japan to support the yen. It has resulted in a stronger yen despite the release of weaker than expected Japanese GDP for Q3. It was revealed overnight that Japan’s economy unexpectedly contracted marginally by an annualized rate of -0.1% in Q3 following an upwardly revised expansion of 1.7% in Q2. The sharp slowdown in growth was mainly driven the temporary negative impact from an earthquake and bad weather due to typhoons and heavy rain. Bad weather put a dampener on private consumption the summer which fell by -0.3% in Q3. Tokyo saw rain for 37 consecutive days from late August through to early October which was record streak according to the Japan Meteorological Agency. The Kyushu earthquake also forced factory shutdowns including in auto-related industries, and contributed to the stall in export growth. As a result, net exports subtracted -0.6ppts from growth in Q3. One bright spot was corporate investment which rose by 1.6% in Q3 following a drop of -0.4% in Q2.
Overall, we don’t expect weaker growth in Q3 that was reinforced by temporary factors to derail the BoJ’s pans for faster quarterly rate hikes. We still expect the BoJ to hikes rates again as soon as next month providing support for the yen. One of the leading hawks at the BoJ Hajime Takata also spoke overnight and emphasized that the BoJ “should not carry out rate hikes at a fixed pace and size but instead needs to raise the rate nimbly”. He believes the policy rate has “only finally approached the neutral zone” and believes “it is necessary to bring the policy rate sufficiently close to the neutral level”. He is not overly concerned by the recent weakness in AI-related stocks and expects AI investment to remain solid”.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
EC | 08:30 | ECB's Vujcic Speaks in Frankfurt | !! | |||
EC | 10:00 | Industrial Production SA MoM | Sep | 0.30% | -0.50% | !! |
CA | 13:30 | CPI YoY | Oct | 3.20% | 3.10% | !!! |
US | 14:05 | Fed's Williams Gives Opening Remarks | !!! | |||
EC | 14:15 | ECB's Kocher, Zigman Speak in Frankfurt | !! | |||
US | 17:00 | Fed's Warsh Participates in Fed Conference on Productivity | !!! | |||
US | 17:00 | Fed's Warsh Takes Part in Fed Conference | !!! | |||
US | 19:15 | Fed's Hammack on Bloomberg TV | !! | |||
AU | 22:50 | RBA's Bullock-Panel | !! | |||
Source: Bloomberg & Investing.com