
India: RBI (Oct 2026) – Is it hawkish enough for markets?
RBI raises its repo rate
RBI raised its key repo rate by 25bps to 5.50% from 5.25% in its Oct 2026 policy meeting, and shifted its policy stance to “calibrated tightening” from neutral previously. The decision was unanimous for a repo rate hike, and a 4-2 decision in favour of the policy stance shift. We were leaning towards a hold this meeting, but importantly we have already been ahead of the consensus in forecasting rate hikes by the RBI and ultimately thought it was just a matter of time before rate hikes are delivered (see India: Too much of a good thing?)
Overall, while it’s true that RBI has turned hawkish, we don’t think the central bank has quite turned hawkish enough to validate current INR rate market pricing based on today’s meeting. It’s true that RBI raised both growth and inflation forecasts, with an increasing focus on possible broadening and second-round effects on inflation. Nonetheless, the communication on the rate path for now does not strike us as a sharp rate hike cycle. For one, RBI said that rate cuts are off the table “in the near-term”. Second, the stance change was for “calibrated tightening” and the bar reasonably low to strive to align the weighted average call rate (currently at ~5.1%) to the repo rate. Third, RBI did not see meaningful demand-side pressures and supply-side constraints currently.
All this could of course change depending on how India’s growth-inflation dynamics play out coupled with external conditions including extent of Fed rate hikes and global commodity prices. Nonetheless, with 1-year onshore INR OIS at 6.26%, and 2-year at 6.45%, we don’t quite like chasing rates higher at these levels given how much has been priced in the front-end.
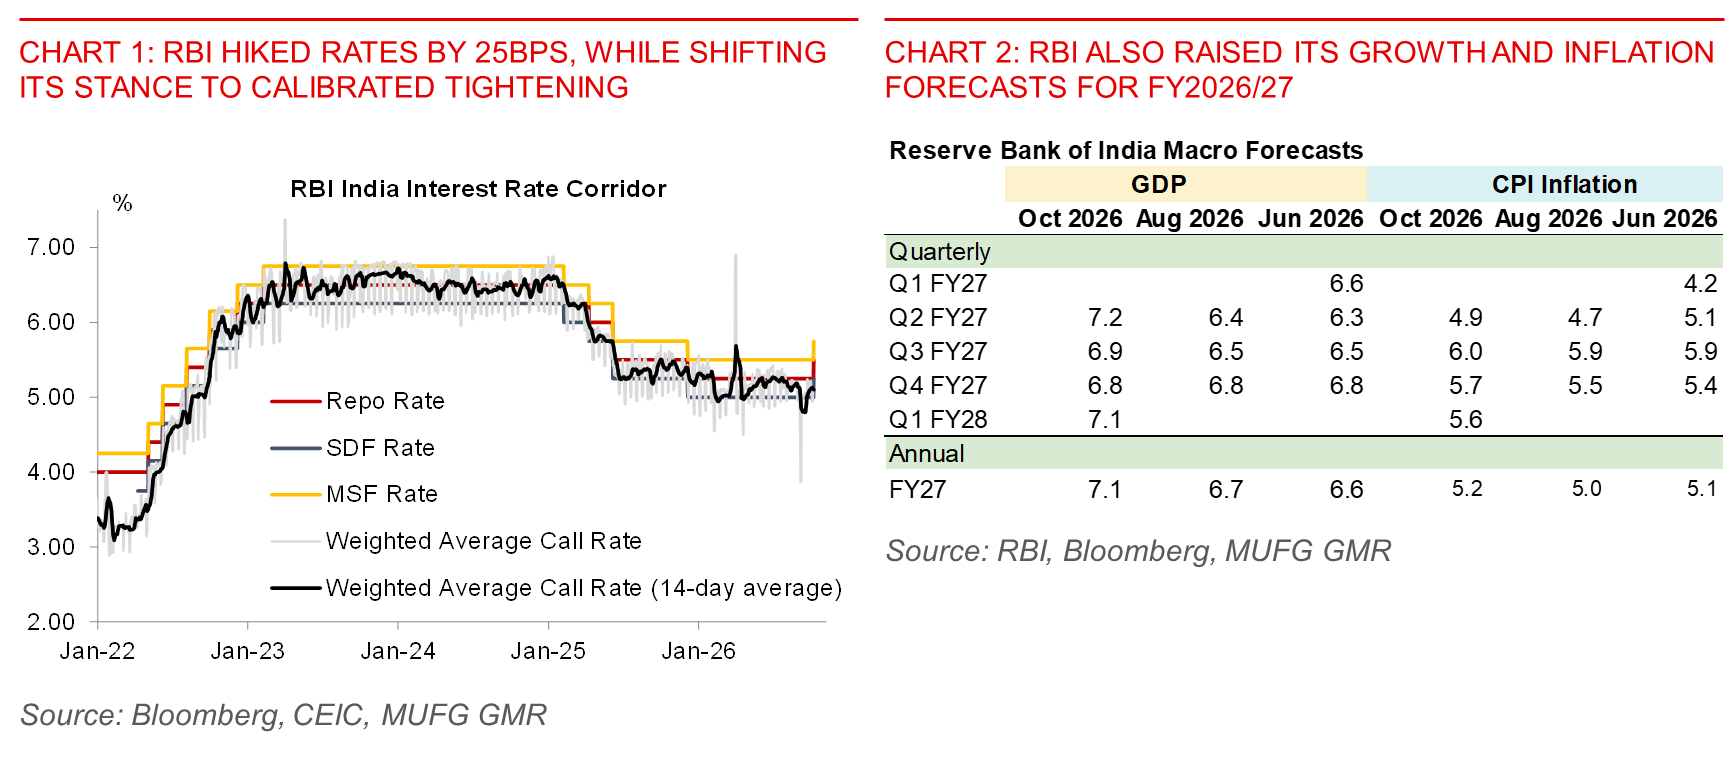
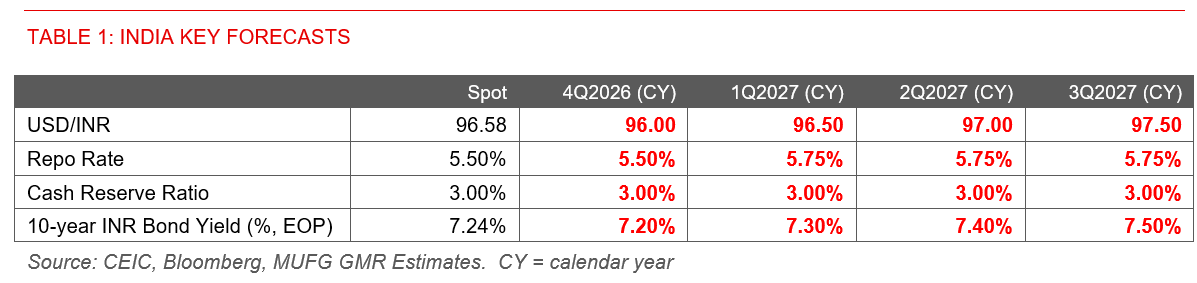
We have one more 25bps rate hike in our forecast pencilled for Feb 2027 which would bring the repo rate to 5.75%, and we also see some risk tilted towards RBI bringing the policy rate eventually to 6.00%.
We however still see some pressure on longer-end INR bond yields to move higher given RBI will likely have to sell more bonds through OMOs and we see 10-year yields rising towards the 7.50% handle over time.
From an FX perspective, INR continues to remain under some pressure from higher oil prices, elevated US rates, coupled with domestic factors such as weak foreign portfolio inflows and higher gross FDI repatriation.
We see USD/INR directionally moving gradually higher over time as our modal forecast, but the topside will be capped by RBI given the meaningful FX reserves that are on its balance sheet now with US dollar inflows from RBI’s June measures including close to US$140bn from the FCNR(B) facilities. In addition, given that US rates markets have already priced in quite a bit in terms of Fed rate hikes in the curve, the risk-reward may tilt towards US yields moving lower from here at least more so for the front-end, and capping any moves higher in USD/INR.
We are forecasting spot USD/INR at 97.50 by 3Q2027 (calendar year), with the risk of sharp INR depreciation capped by RBI.