
Seasonal improvement in current account likely not enough for CBRT
Seasonal tourism flows and lower energy prices helped the current account
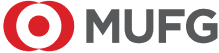
Turkey’s current account balance moved into surplus in August at USD 4.05bn, supported by a seasonal increase in the services surplus related to tourism flows and a narrower goods deficit thanks to lower energy prices during the month. On the capital account, net FDI into Turkey remained positive but dropped to USD 141m in August while portfolio investment switched to a new outflow of USD 1bn.
Turkey’s current account balance shows a high degree of seasonality as tourism inflows peak during the summer months. Tourism arrivals from non-citizens have been running softer in 2026 year-to-date, down 1.8% as of August at 34.8m tourist arrivals. Sticky elevated average-daily rates as domestic inflation still remains high albeit on a disinflationary path and longer nights spent are helping to compensate for the drop in volume of arrivals in 2026. The August print also reflected the narrowest goods deficit in 2026 year-to-date as energy prices were lower over the summer months compared with earlier in Q1/Q2 as oil and gas exports from the Middle East region moved higher.
Central bank has been selling FX recently
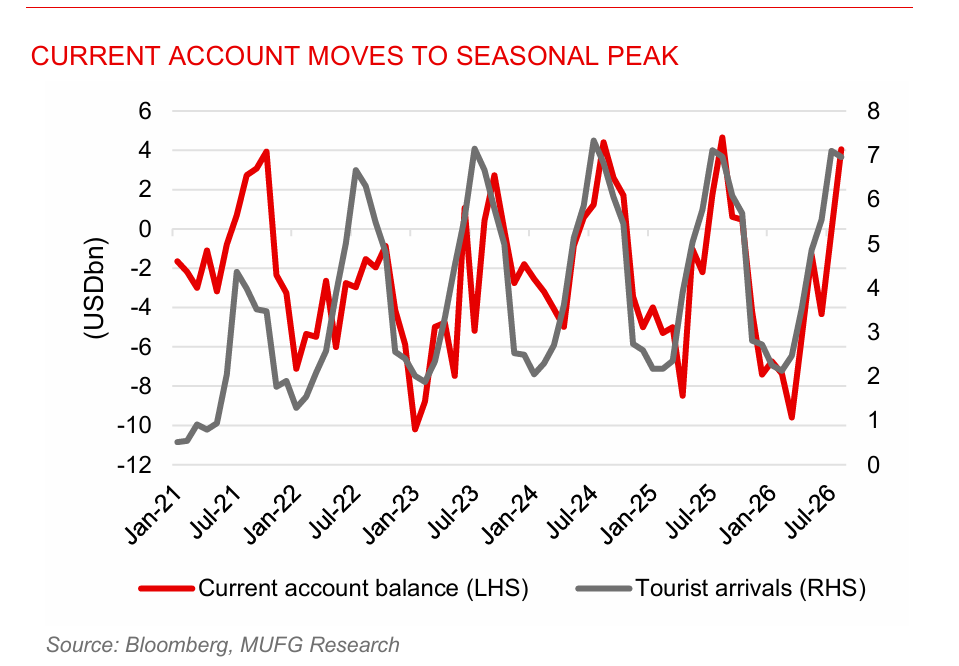
The improvement in the current account position tallies with the rebuild in FX reserves over July-August but since then the TCMB has been selling FX. Since the start of September the central bank has sold USD 10.8bn in FX reserves to ensure ample TRY liquidity is available as the financial system absorbs the impact of several investment funds being wound down.
Disinflation has remained in place ahead of next policy meeting
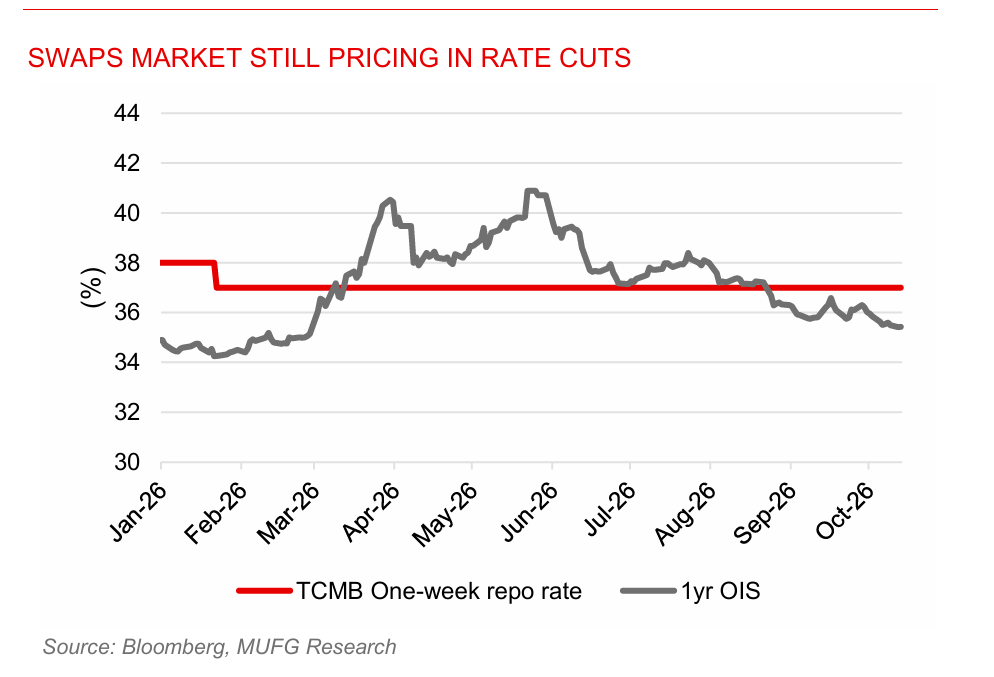
The central bank next meets on October 22 to set policy after holding rates unchanged for the last five meetings. Inflation surprised positively for September with the annual rate falling to 29.7% y/y from 31.5% a month earlier. We expect that the central bank will look through the highly seasonal improvement in the balance of payments and will still treat the disinflation path with caution: since the start of October energy prices have remained elevated with Brent futures holding above USD 100/b every day and gasoil prices holding onto gains reached last month. The sharp drop in FX reserves may also give the CBRT pause before deciding when to restart its rate cutting cycle. Swaps markets are still pricing rates cuts over the next year with nearly 160bps of easing priced in though with much of that easing priced in later in the period.