
USD reverses US mid-term election losses as AI-equity sell-off intensifies
USD: Deeper correction lower for AI-related stocks boosts safe haven demand
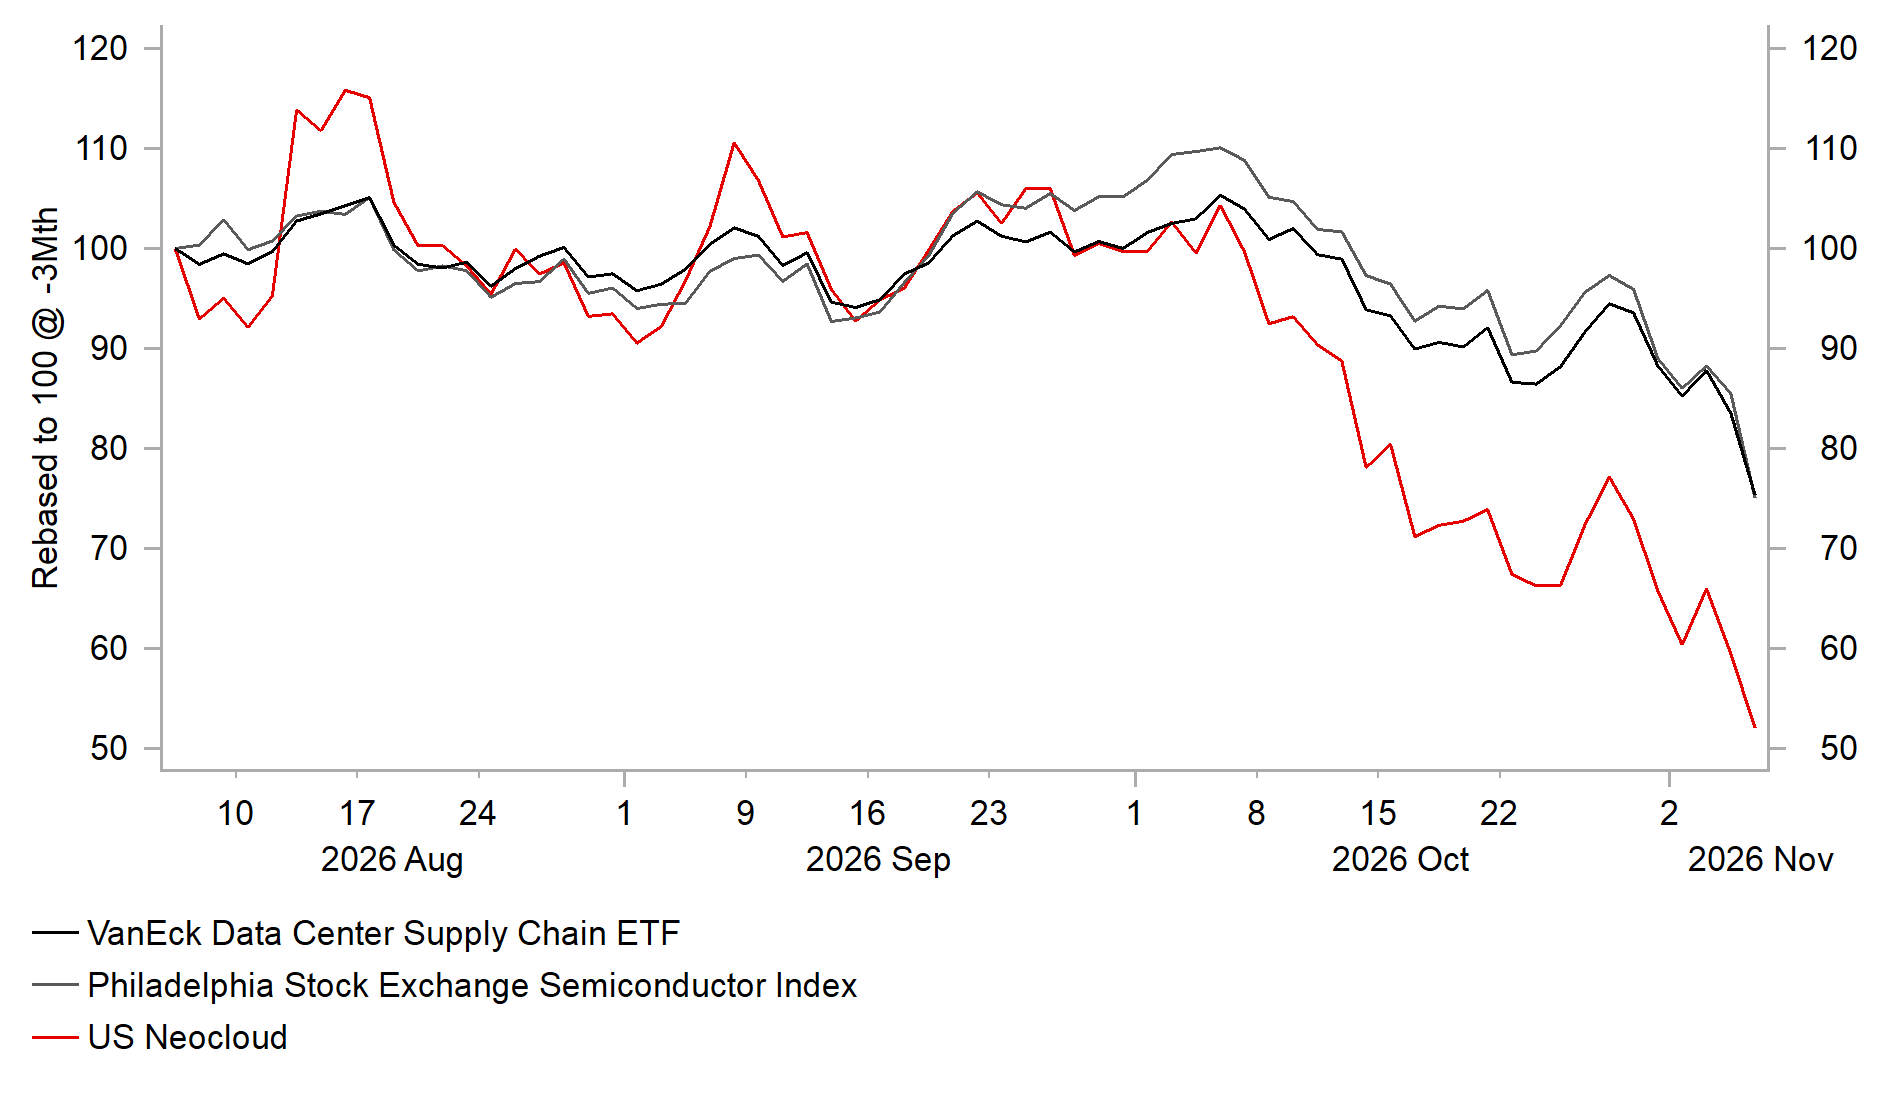
The main development overnight has been sharp sell-off for AI-related investments. Acute weakness in the US equity market has spilled over into Asian markets overnight with the Topix and Kospi equity indices both falling by around 6%. It follows on from a similar sized drop in the Nasdaq composite index of around -5.5%. The sell-off in the Nasdaq composite index accelerated yesterday after it broke below support from its 200-day moving average that came in at around 25,090. It is the first time that Nasdaq composite index has fallen below the 200-day moving average since earlier this year in March and April. After yesterday’s sell-off the Nasdaq composite index now stands just over -12% below the peak from last month which compares to the sell-off in the first three months of this year totalling around -13.8%. Yesterday’s sharp sell-off appears to have been a delayed reaction to the US mid-term elections results which have heightened investor uncertainty over AI-related investment returns. The strong performance of the Democrats in the has triggered investor concerns that the ongoing build out of AI data centres could be disrupted, and policy could shift towards implementing tighter regulation on the AI sector in the future. One of the biggest casualties yesterday were chipmakers such as Nvidia which fell by over 9% and has reversed all of its year-to-date gains. At the same time, neocloud companies continue to underperform. Adding to negative investor sentiment yesterday, Microsoft announced that it is tightening oversight of some data centre projects and stepping away from ones it deems risky due to delays, regulatory snags, and high costs. They are also reportedly debating internally whether to sign new neocloud deals, with some leaders expressing strong reluctance to add new capacity from third-party providers. Microsoft highlighted in recent earnings calls that delays in the delivery of some third-party capacity was disrupting the company’s spending plans.
The spillover impact from the AI-related equity market sell-off into the foreign exchange market has remained surprisingly modest so far. The Australian dollar has been hit the hardest so far falling by around -1.5% against the US dollar since 4th November undermined as well by the recent sharp correction lower in energy prices including natural gas. At the other end of the spectrum, the three best performing G10 currencies so far have bene the traditional safe haven currencies of the yen, US dollar and Swiss franc. It has resulted in the dollar index reversing all of its initial losses since the US mid-term election results were announced. The resilience of the US dollar is somewhat surprising given the ongoing unwinding of investor confidence in AI-related investments in the US, and sharp correction lower in energy prices reflecting renewed optimism over a US-Iran deal. US dollar strength this year has been supported by higher energy prices and record foreign demand for riskier US assets. If both these drivers continue to reverse, it would increase the likelihood of the US dollar weakening.
At the same time, the sharp sell-off in AI-related investments is contributing to a further tightening financial conditions in the US. A development acknowledged by Fed Cahir Kevin Warsh at the last FOMC meeting. If financial conditions continue to tighten it could make it less likely that the Fed will hike again in December as planned thereby adding to downside risks for the US dollar. The US rate market still judges that a December hike remains more likely than not although the probability dropped in recent days. It is currently pricing in around 16bps of hikes compared to around 21bps of hikes on 4th November. The tightening of US financial conditions could prove more important in decided Fed policy action in December than today’s NFP report which is expected to show stronger employment growth.
DEEPENING AI-RELATED EQUITY SELL-OFF
Source: MUFG Research, Macrobond, Bloomberg
GBP: BoE to finally hike rates but provide cautious guidance update
The market impact of yesterday’s BoE policy update was overshadowed by the deepening sell-off for AI-related investments. UK yields and the pound both rose initially after the BoE’s hawkish hike although have since reversed those moves after the sell-off in US equity market intensified. UK yields have held up better than in other major economies supported by the hawkish message from the BoE signalling that at least one more hike is likely in the current tightening cycle. We had expected more cautious policy guidance from the BoE pushing back against expectations for more aggressive rate hikes but that did not materialise.
Governor Bailey stated clearly that there was a strong case for another rate hike if the US-Iran conflict is not resolved. It was a view shared by the majority of other MPC members, with Catherine Mann, Huw Pill, Megan Greene and Clare Lombardelli all leaning towards at least one more hike. We have been forecasting that the BoE will follow up today’s hike with another increase in February next year, but acknowledge that there is now a higher risk of a back-to-back hike in December. The UK rate market is now attaching around 13bps of hikes by December.
One important caveat is that Governor Bailey indicated that the BoE will be mainly focused on energy price developments heading into year-end. The price of oil has dropped sharply over the past week, which was not incorporated in the BoE’s updated economic forecasts. If oil prices remain at much lower levels, reflecting perhaps progress towards a US-Iran deal following the US mid-term elections, the BoE may be more inclined to hold off on hiking rates again as soon as next month. After one more hike, the case for further increases is judged as less clear-cut by MPC members. Governor Bailey stated, “I’m not going to sign up to the idea of ‘two-and-done’” while emphasising that a series of hikes is “not inevitable”. The BoE will be watching closely for evidence of building second-round effects to assess whether further rate hikes are required in 2027. At the same time, a deeper sell-off in AI stocks and resulting tightening of global financial conditions could dampen the BoE’s willingness to tighten policy further.
The GBP has recently been supported by growing optimism over stronger UK growth, higher UK yields and fiscal concerns becoming a bigger market issue in the euro area than in the UK. At today’s policy meeting, the BoE acknowledged that UK growth has surprised positively, partly reflecting stronger exports and an AI-related investment and productivity boost. In the near term, stronger activity suggests less spare capacity in the economy and has added to the case for tighter monetary policy. However, the inflation implications are ambiguous. The BoE still needs to determine whether the recent improvement in productivity represents a persistent increase in the economy’s supply capacity. Overall, today’s hawkish BoE policy update should reinforce the GBP’s bullish momentum heading into year-end. One downside risk for the GBP would be a deeper sell-off for AI stocks and tightening of financial conditions given the GBP’s role as more of a high yielding G10 currency. Please see our latest FX Focus for more details (click here).
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Forecast | Previous | Mkt Moving |
EU | 10:00 | Retail Sales (MoM) | (Sep) | -0.1% | 0.1% | ! |
GB | 12:15 | BoE MPC Member Pill Speaks | - | !! | ||
US | 13:30 | Nonfarm Payrolls | (Oct) | 65K | 29K | !!! |
US | 13:30 | Unemployment Rate | (Oct) | 4.2% | 4.2% | !!! |
US | 13:30 | Average Hourly Earnings (MoM) | (Oct) | 0.3% | 0.1% | !!! |
CA | 13:30 | Unemployment Rate | (Oct) | 6.5% | 6.5% | !! |
CA | 13:30 | Employment Change | (Oct) | 14.6K | -68.3K | !! |
US | 15:00 | Michigan Consumer Sentiment | (Nov) | 48.1 | 48.0 | !! |
JP | 16:00 | BOJ Gov Ueda Speaks | - | !!! |
Source: Bloomberg & Investing.com