
FOMC to stay hawkish but maybe with a nod to tighter financial conditions
USD: FOMC on hold with Warsh staying hawkish
The US dollar remains under upward pressure although FX moves are generally well contained – apart from NZD/USD, which is down over 1% following the surprise hold by the RBNZ today. We would argue that it is perhaps evidence that inflationary pressures are not feeding through more broadly across many economies and it’s not just the RBNZ that is grappling with how much rates need to be raised given the mixed economic conditions. Clearly the RBNZ is divided on that key aspect, and it was a big surprise to hold given a hike was nearly fully priced. We were already of the view that the RBNZ would not hike as much as priced in the market over the next 12mths and this decision reinforces our view. NZD will continue to underperform.
Today is a day of key events – the UK budget; the BoC rate decision followed by the FOMC policy decision this evening. The FOMC is very likely to remain on hold but the OIS indicates close to 10% probability of a hike. A hold would likely be accompanied by a statement similar to the statement in September when the FOMC hiked underlining the fact that the economy remains resilient. There is a risk that there could be some dissents and that would certainly be one signal of the leaning and would strengthen the market’s conviction of a hike in December. A December hike is close to fully priced. If the press conference is similar in tone to previous public engagements by Chair Warsh he is likely to come across as hawkish. We certainly don’t expect anything explicit in regard to a policy decision in December but we can expect Warsh to emphasise the determination of the FOMC to meet its price stability objective.
We will be watching out for comments regarding financial conditions. The Nasdaq has rebounded modestly in the last two trading sessions but there has been some increased volatility in AI-related stocks and some signs that higher yields are impacting risk. Credit spreads have widened and there is certainly more compelling evidence today of more challenging market conditions. Might Warsh give a further nod to tightening financial conditions doing more of the work that could curtail expectations on policy action further out in 2027. If that view was emphasised more, it could even weaken expectations modestly for a December hike. A hawkish communication is generally expected so any surprise dovish elements would likely have a bigger impact weakening the dollar than a hawkish message would strengthen the dollar further.
Prior to the FOMC decision we will get the budget announcement in the UK and 12:30 GMT. We have written a preview (here) and expect the government to announce a reasonably cautious budget with no major surprises. We expect the headroom to decline to approx. GBP 14bn (from GBP 23.6bn) with that drop entirely down to the rise in Gilt yields. We suspect the bond market will be accepting of this decline in headroom as long as the details are generally credible. How the government intends to lift defence spending will be one area of focus (media reports suggest classing spending as investment via funding through the British Business Bank). The global backdrop is important here too and with yields having corrected lower the challenge of avoiding any big Gilt sell-off is a little less. We do not expect fireworks this afternoon and avoiding any big Gilt move is achievable which would help provide a modest lift for the pound.
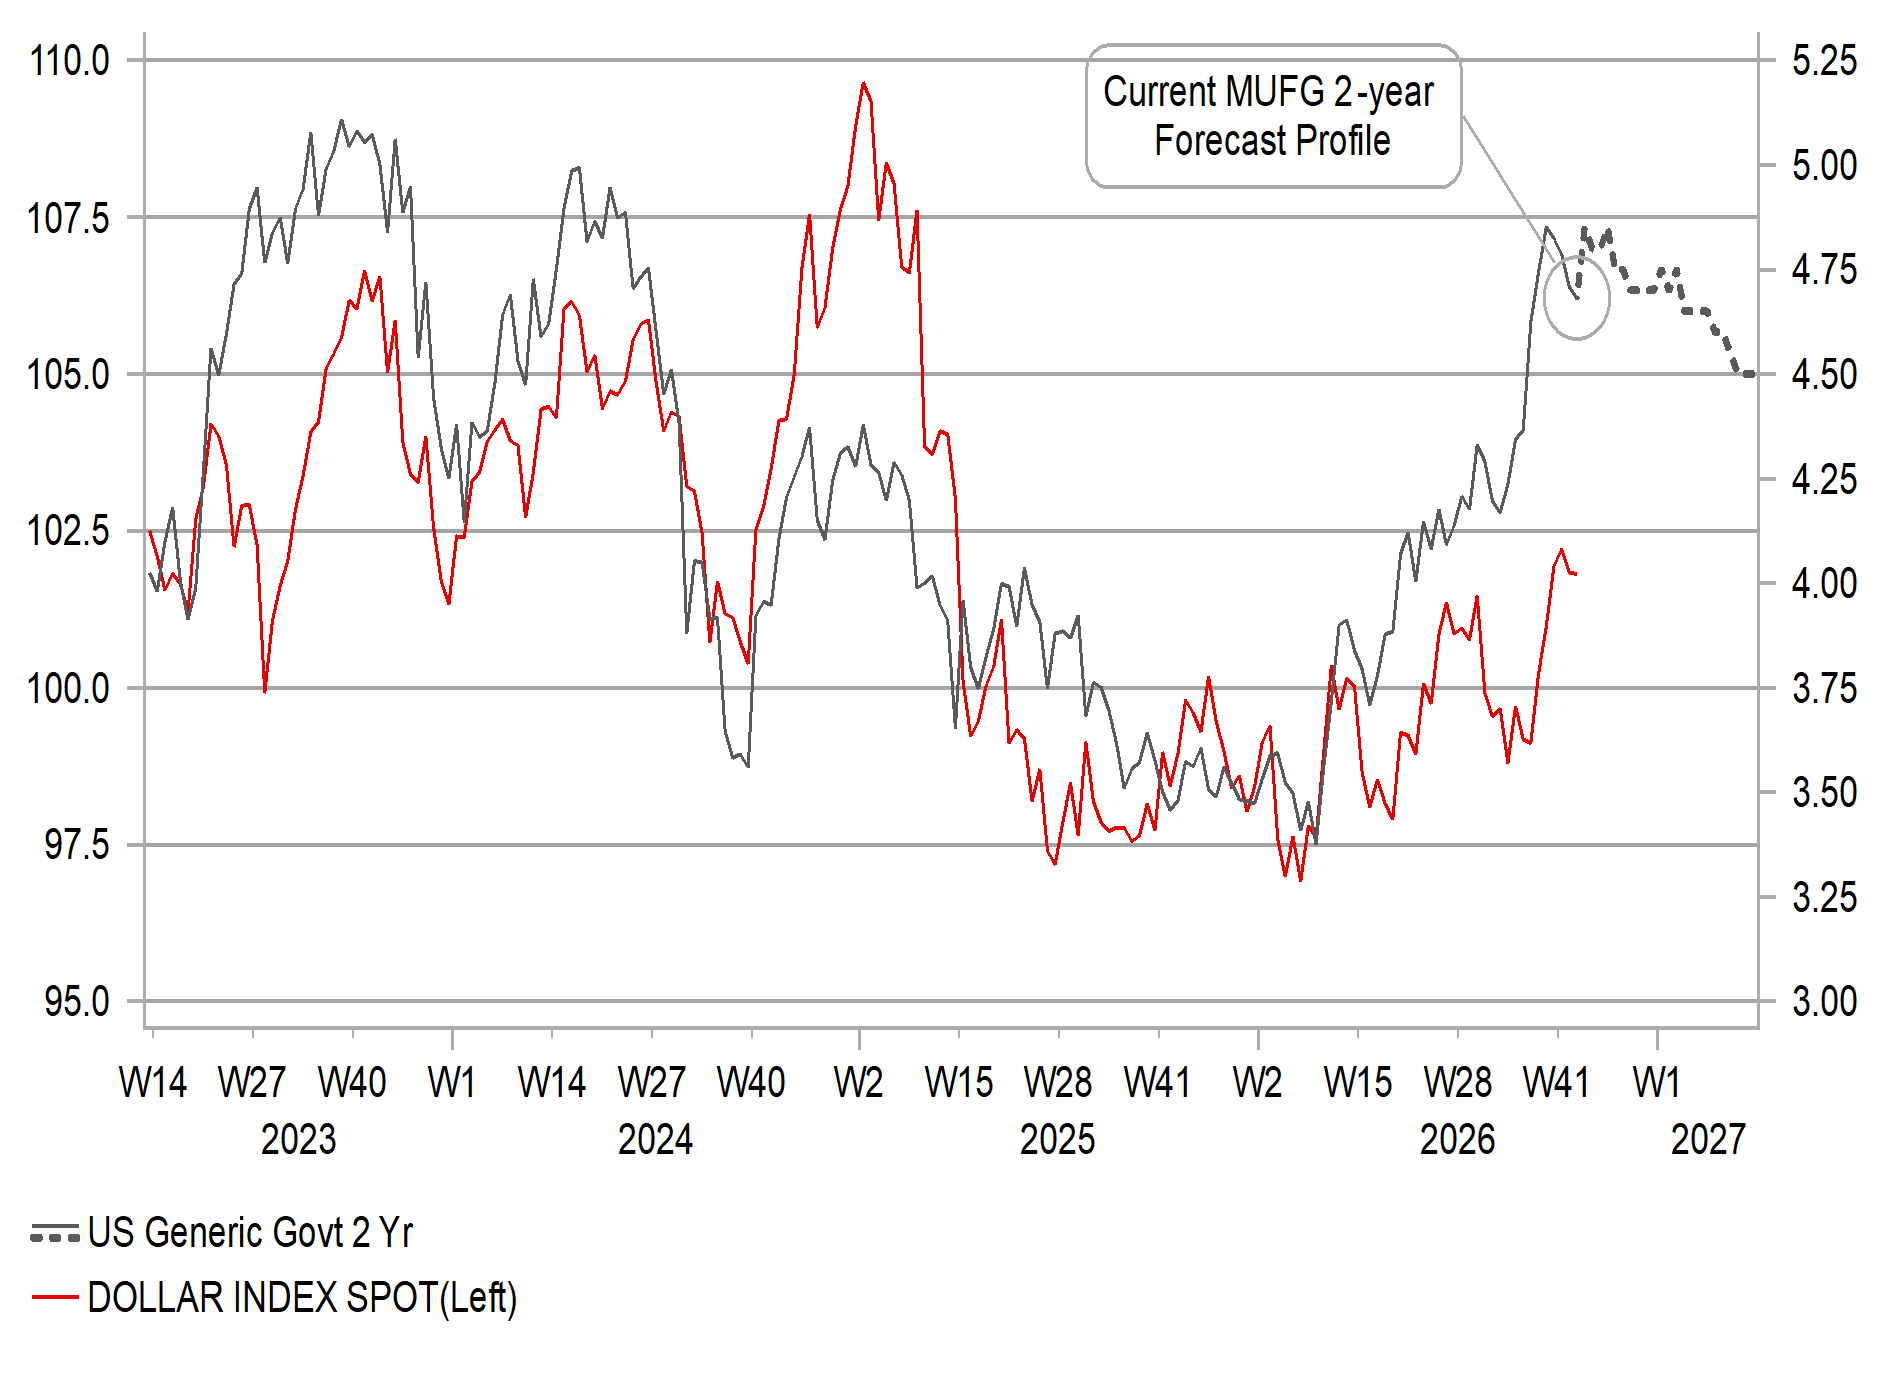
OUR US RATES FORECASTS TO KEEP DOLLAR WELL SUPPORTED
Source: MUFG Research, Macrobond, Bloomberg
CAD: A hike won’t do much for CAD
The pricing for today’s BoC meeting indicates an 80% probability of a rate hike which is not quite in done-deal territory and there is scope for a surprise. However, we expect the BoC to hike and recent communications does point to action being taken. Expectations were a lot lower prior to the CPI data for September. The headline, median and trim annual rates all came in less than expected but this was the day market expectations adjusted higher. The CPI report failed to override comments made just prior to the release when Governor Macklem spoke (17th Oct) and expressed clear concerns over the outlook for energy-related inflation risks. These comments were made at a point Brent crude oil was trading lower than today’s levels and hence we can be sure that Macklem and probably the rest of the policy committee will be more concerned now. An oil price of USD 100pbl was higher than what was assumed in the July projections so it’s very likely that the inflation projections today will be higher than in July – offering justification for a rate hike today.
But there is 100bps of hikes priced into the OIS curve out to September next year and hence the question is – will today’s communications be consistent with that extent of hikes currently priced? That’s the big risk and we are doubtful that Governor Macklem will convey such a hawkish message to keep the markets confident of a prolonged period of rates hikes. If Macklem had not steered the markets on 17th October it’s unlikely based on incoming information that pricing would be sitting at an 80% probability of a hike.
The labour market in particular looks weak and was a key reason rate hike expectations were much lower prior to Macklem’s comments. The Canadian economy lost 68.3k jobs in September after a loss of 41.7k in August. While there have been reports of a trade deal being reached between the US and Canada that has not yet been confirmed and hence Macklem can’t use that as a source of good news or optimism.
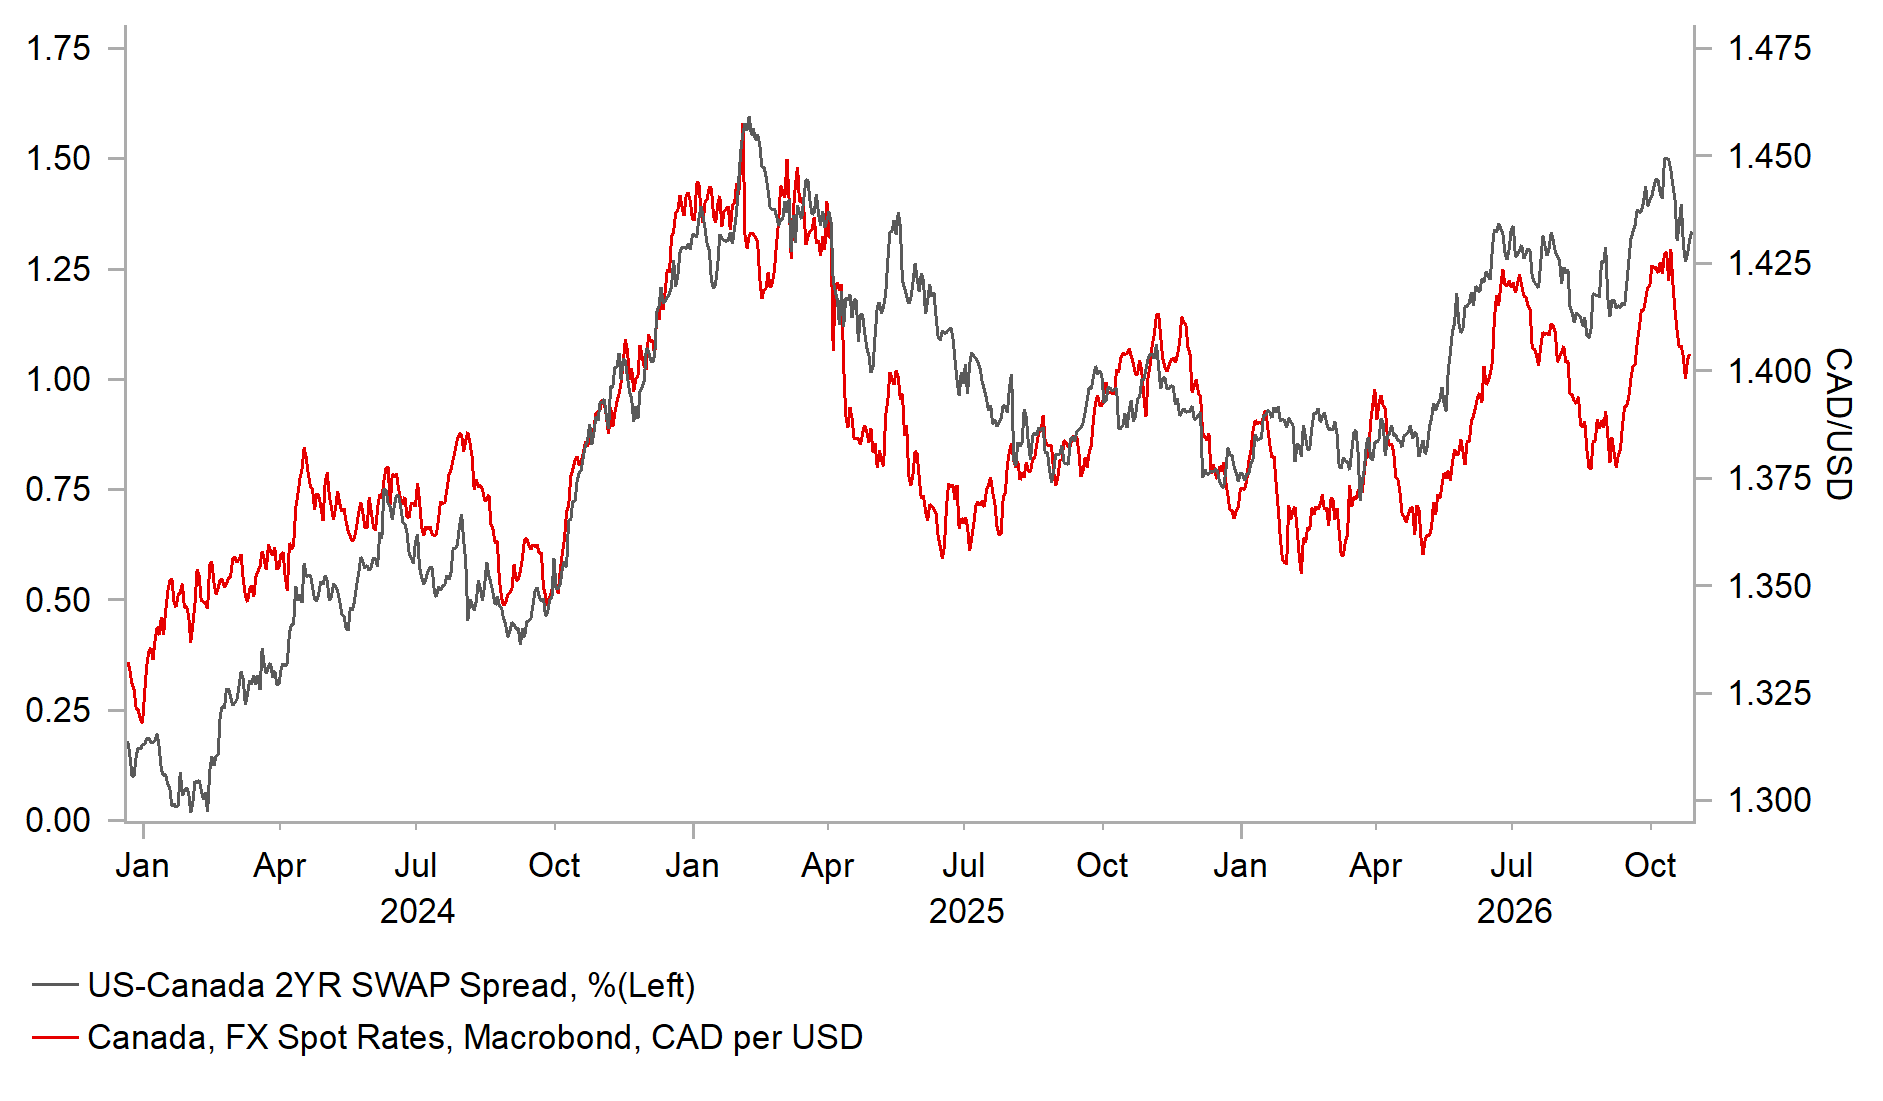
So we don’t see much scope for USD/CAD to move lower on the back of a hike today. Market participants will also be wary ahead of the FOMC meeting later on which will be much more important in shaping USD/CAD direction. Assuming Fed Chair Warsh does enough to keep markets positioned for three more hikes, a rebound in USD/CAD looks more likely than an extension further lower. CAD remains a lower-yielder than most of the rest of G10 and given the fundamental backdrop (limited signs of inflation pass-through, weak labour market conditions, US-related trade risks) we doubt there is much upside scope to front-end yields, especially given what is already priced.
USD/CAD SCOPE TO THE DOWNSIDE LOOKS LIMITED
Source: MUFG Research, Macrobond, Bloomberg
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
US | 11:00 | MBA Mortgage Applications (WoW) | - | - | -5.3% | ! |
UK | 12:30 | Autumn Forecast Statement | - | - | - | !!!! |
US | 12:30 | Goods Trade Balance | (Sep) | -130.40B | -132.07B | !! |
US | 12:30 | Wholesale Inventories (MoM) | (Sep) | 0.5% | 0.5% | ! |
CA | 13:45 | BoC Interest Rate Decision | - | 2.50% | 2.25% | !!!! |
CA | 13:45 | BoC Monetary Policy Report | - | - | - | !!! |
CA | 13:45 | BoC Rate Statement | - | - | - | !!!! |
CA | 14:30 | BOC Press Conference | - | - | - | !!!! |
US | 18:00 | Fed Interest Rate Decision | - | 4.00% | 4.00% | !!!!! |
US | 18:00 | FOMC Statement | - | - | - | !!!! |
US | 18:30 | FOMC Press Conference | - | - | - | !!!!! |
Source: Bloomberg & Investing.com