
EUR underperformance persists with JPY joining
USD: Focus on Fed with RBNZ up first as EUR & JPY lag
The euro remains under downward pressure and is still the worst performing G10 currency on a month-to-date basis. The yen has now also renewed its downward momentum despite further comments today from Finance Minister Katayama threatening “bold action” in the FX market if needed. We are likely still some distance from that with the 160-level the obvious point in which those threats could turn into action. The yen may well struggle through this week with investors likely anticipating BoJ Governor Ueda being more cautious in his words on Friday given the global backdrop. Governor Ueda has a history of communicating a cautious message when the level of uncertainty is high. We have had a glimpse of how the yen may perform if there was a major AI-related correction in global equity markets when the yen showed traits of its previous safe-haven status following the recent AI sell-off. The BoJ will be mindful of that and while we expect the BoJ to signal more rate hikes are necessary, Ueda’s style of communication suggests he may not provide a strong message on a move in December that remains 80% priced. That could mean USD/JPY retraces further higher this week, especially if investor sentiment related to AI stabilises.
For the euro, the notable narrowing of the OAT/Bund spread did little to bring EUR buyers to the market and that underlines the continued negative sentiment and momentum. The focus looks to have shifted away from imminent OAT risks to the risk to the economy from rising energy prices – natural gas prices. For much of the time in recent months, rising natural gas prices had limited impact on the euro with ECB rate hike expectations strengthening to provide support. However, EUR/USD is now sinking again even though the 2-year swap spread has moved by nearly 15bps in favour of the euro since 5th October. Over that same period, the TTF natural gas price has advanced by over 30%. Since the US-Iran deal broke down in June TTF is up 140%. The European economy has shown resilience to date to the energy price shock but investors are turning sceptical over the prospect of that resilience continuing.
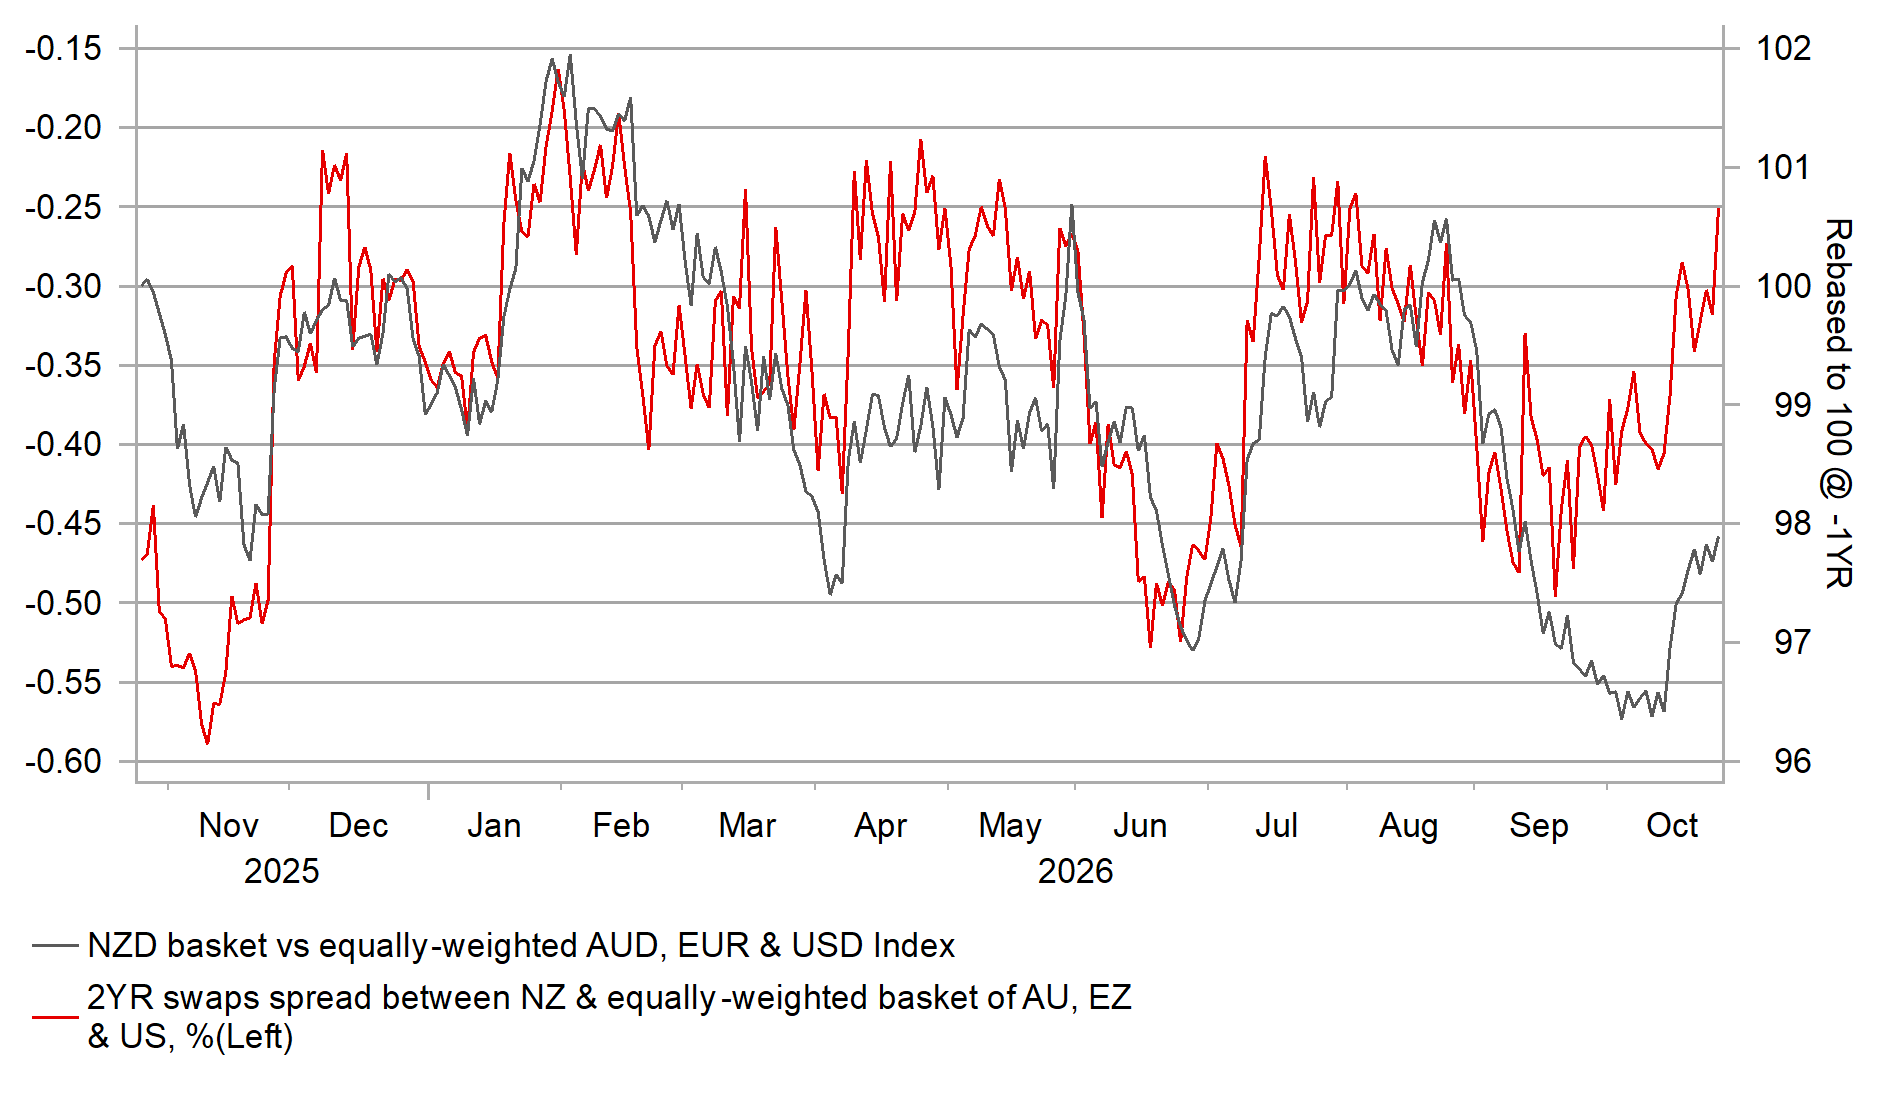
First up in the schedule of G10 central bank announcements this week is the RBNZ which will announce later tonight, and the rates market is nearly fully priced for a 25bp hike. NZD is the third best performing G10 currency this month and a hawkish hike is what is required for that currency performance to continue – three rate hikes in total are priced by March so strong guidance supporting that pricing is required. We expect the RBNZ to deliver tonight but ultimately under-deliver what is priced. We expect only one further hike to 3.25% – the market pricing implies 3.5 additional hikes after tonight’s. Q3 inflation was a little weaker than expected and that likely highlights the level of spare capacity in the New Zealand economy that won’t require what market pricing implies. The unemployment rate jumped to 5.6% in Q2, the highest level since Q3 2015. Risks are skewed to the downside for NZD and even if the RBNZ does deliver a hawkish hike, investors will at some point likely question the extent of hikes priced. We expect NZD to underperform over the forecast period ahead.
RBNZ RATE HIKE PRICING REFLECTED IN NZD PERFORMANCE
Source: MUFG Research, Macrobond, Bloomberg
BRL: Election shock sell-off contained to Brazil
The shock victory for President Lula de Silva in Brazil over the weekend had a huge impact for Brazilian markets with USD/BRL surging close to 10% yesterday as the IBOVESPA plunged 17% on the open. This drop more than wiped out the gains made following Flavio Bolsonaro’s victory in the first round of the election. Still, despite such a huge one-day drop (closed -13.9% biggest one-day drop since covid), the IBOVESPA only closed at a level close to where the market was trading around the end of August. Optimism of a possible Bolsonaro win then helped the market further higher in September.
The scale of the move is still significant and marks the potential for further volatility in Brazil markets over the coming days. A possible curtailment of selling may come from the fact that the make-up of Congress is more right-leaning at about 60% of seats. This could force Lula to compromise in order to make any progress with policy. He will be more reliant on centrist parties that could mean he is forced to make credible attempts to tackle government waste. But that will not become clear immediately and hence investors will be quick to assume the worst leaving the markets vulnerable.
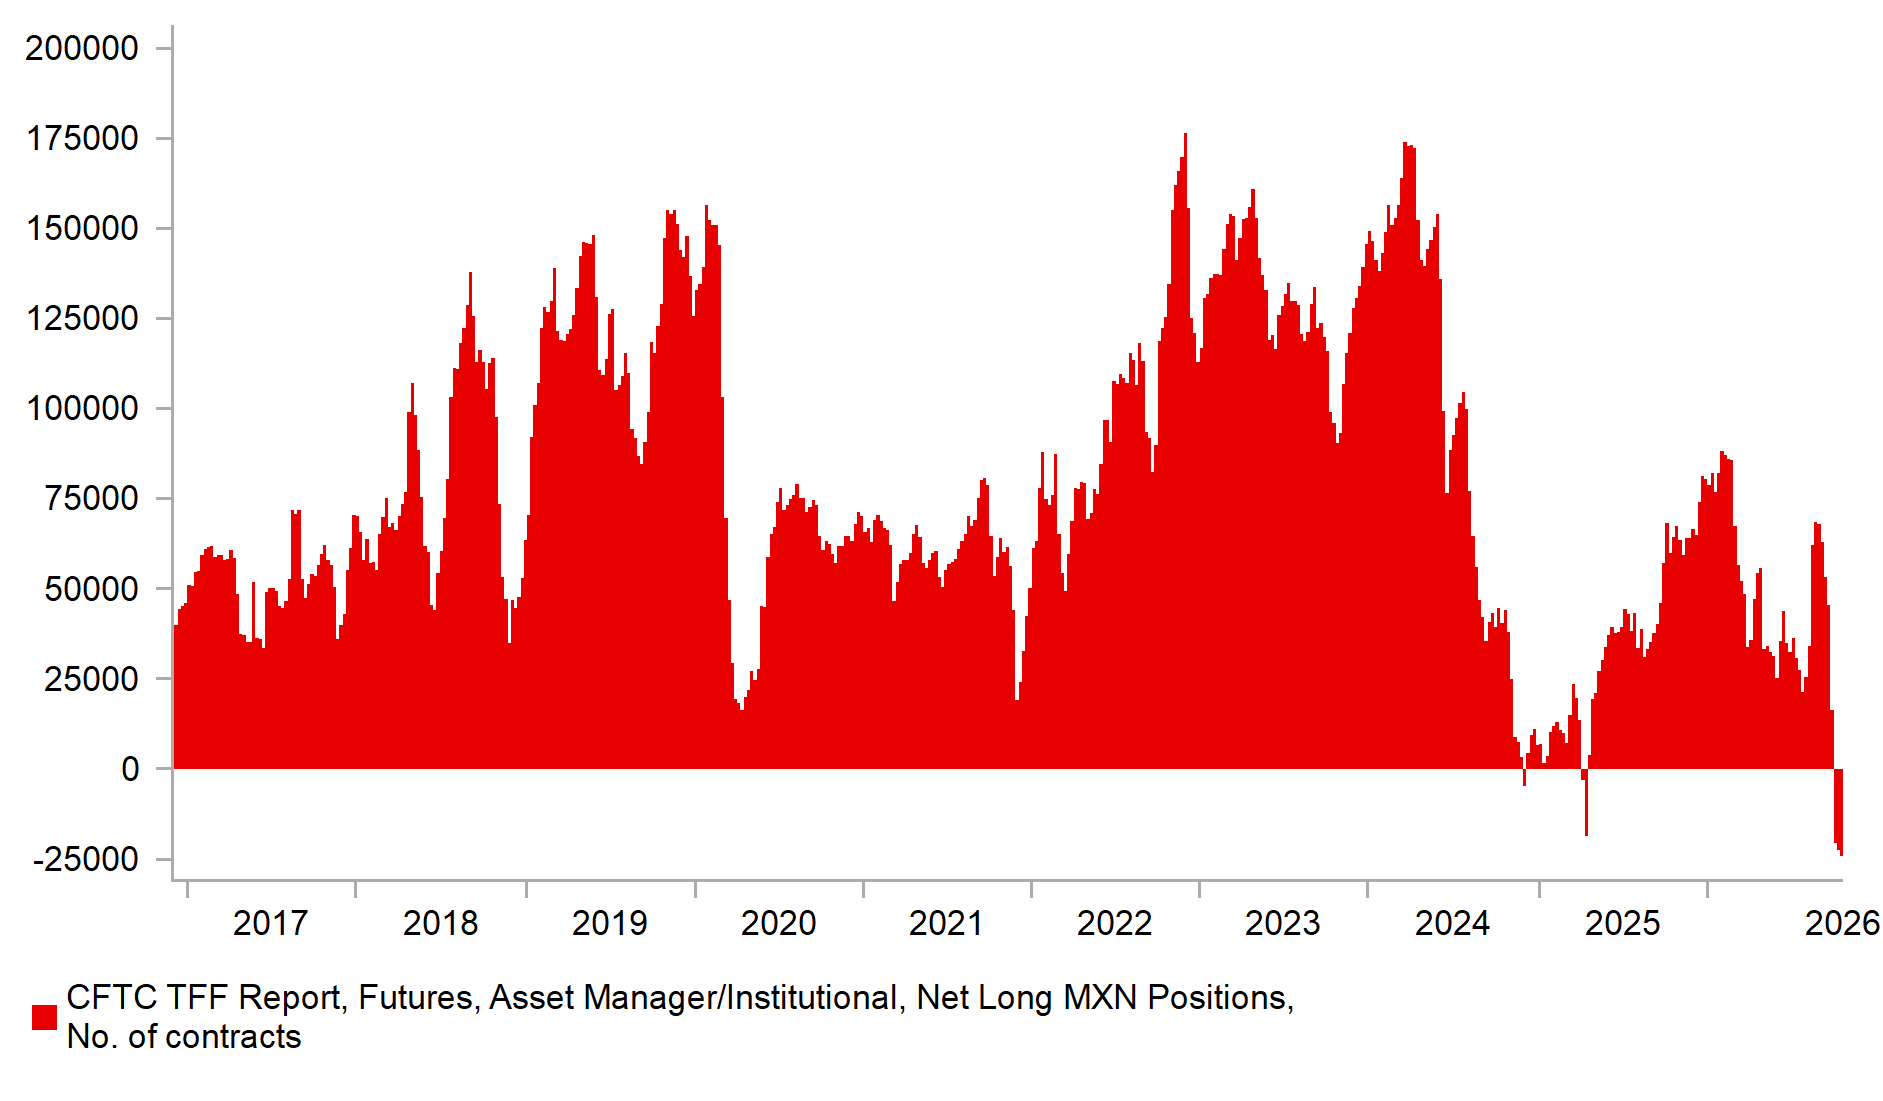
What does look clear from the initial reaction is that this is being viewed understandably as very Brazil-specific with little sign of contagion in the region. There was always a risk of sharp liquidations of long BRL positions could drag other currencies down too – investors who say for example hold long LatAm carry positions. However, the limited sign of contagion reflects the fact that there has already been a position clear-out. USD/MXN is 11% higher since the end of August while USD/CLP is 7% higher. The weekly IMM data confirms a big shift in positioning amongst Asset Managers and Institutional Investors. From a long position of 69k contracts this sector of the market has swung to a short position of 24k. The current short position is the largest in the record of the series going back to 2006. Indeed, part of that shift may have been into long BRL positions since Bolsonaro’s first round win and hence the 0.5% drop in USD/MXN yesterday. The rest of LatAm is also being helped by the fact that US and global yields have retraced lower from recent highs.
RECORD SHORT MXN POSITION AMONGST AM/II LIMITS BRL CONTAGION
Source: MUFG Research, Macrobond, Bloomberg
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
EU | 09:00 | M3 Money Supply (YoY) | (Sep) | 3.6% | 3.5% | ! |
EU | 09:00 | Private Sector Loans (YoY) | (Sep) | 3.1% | 3.1% | ! |
US | 12:00 | Building Permits | (Sep) | 1.400M | 1.403M | ! |
US | 12:00 | Building Permits (MoM) | (Sep) | -0.2% | -2.1% | ! |
US | 12:30 | Durable Goods Orders (MoM) | (Sep) | 1.8% | 0.0% | !! |
US | 12:30 | Core Durable Goods Orders (MoM) | (Sep) | 0.6% | 0.3% | !! |
US | 12:30 | Goods Orders Non Defense Ex Air (MoM) | (Sep) | 0.7% | 1.6% | ! |
US | 13:00 | S&P/CS HPI Composite - 20 n.s.a. (YoY) | (Aug) | 2.7% | 2.5% | !! |
US | 13:00 | House Price Index (YoY) | (Aug) | - | 2.6% | ! |
US | 14:00 | CB Consumer Confidence | (Oct) | 80.5 | 81.9 | !!! |
US | 14:00 | New Home Sales | (Sep) | 649K | 684K | !!! |
US | 17:00 | 5-Year UST Note Auction | - | - | 5.033% | !! |
EU | 17:00 | ECB President Lagarde Speaks | - | - | - | !! |
Source: Bloomberg & Investing.com