
CAD & GBP supported by hawkish repricing of BoC & BoE policy outlooks
GBP: UK labour data adds to evidence of stronger UK cyclical momentum
The pound has continued to strengthen at the start of the European trading session resulting in EUR/GBP falling back towards yesterday’s year-to-date low of 0.8393 while cable has risen above 1.3350. The pound’s recent upward momentum has been reinforced this morning by the release this morning of stronger UK labour market data which revealed that payrolled employment increased by 13k in September. The drop in payrolled employment from the previous month was also revised away from a -26k contraction to a marginal increase of +1k. While the monthly data can be volatile and prone to revisions, the pick-up is consistent with recent surveys pointing towards stabilization in labour market conditions. It was the strongest monthly reading for payrolled employment growth since last summer. For most of this year the performance of the UK economy and labour market has been diverging with the labour market remaining weak even as the economy has grown strongly. The latest labour market report could show now that stronger growth is now helping to improve labour market conditions with a lag. In addition, the labour market report revealed that private sector wage growth moved up to 3.0%Y/Y which was in line with the BoE’s projection. However, it was the first increase since 20024, and the BoE will be watching closely as we go into the pay settlement period for 2027.
Overall, the stronger labour market data will encourage the BoE to begin hiking rates as soon as next month. Boe officials including Governor Bailey have clearly signalled recently that is becoming harder to look through higher energy price and leave rates on hold. Weak labour market conditions have been used to justify caution over tightening policy. We continue to expect the BoE to hike rates next month and deliver a second hike early next year. A view that is already well priced into the UK rate market which is anticipating even more tightening and has almost three hikes priced in by March of next year. Positive cyclical economic momentum in the UK remains favourable for a stronger pound as long as the government ‘s upcoming Budget doesn’t undermine confidence in the credibility of their fiscal consolidation plans. EUR/GBP is currently attempting to break into a new lower trading range between 0.8200 and 0.8400 that was last in place between September 2024 and April 2025.
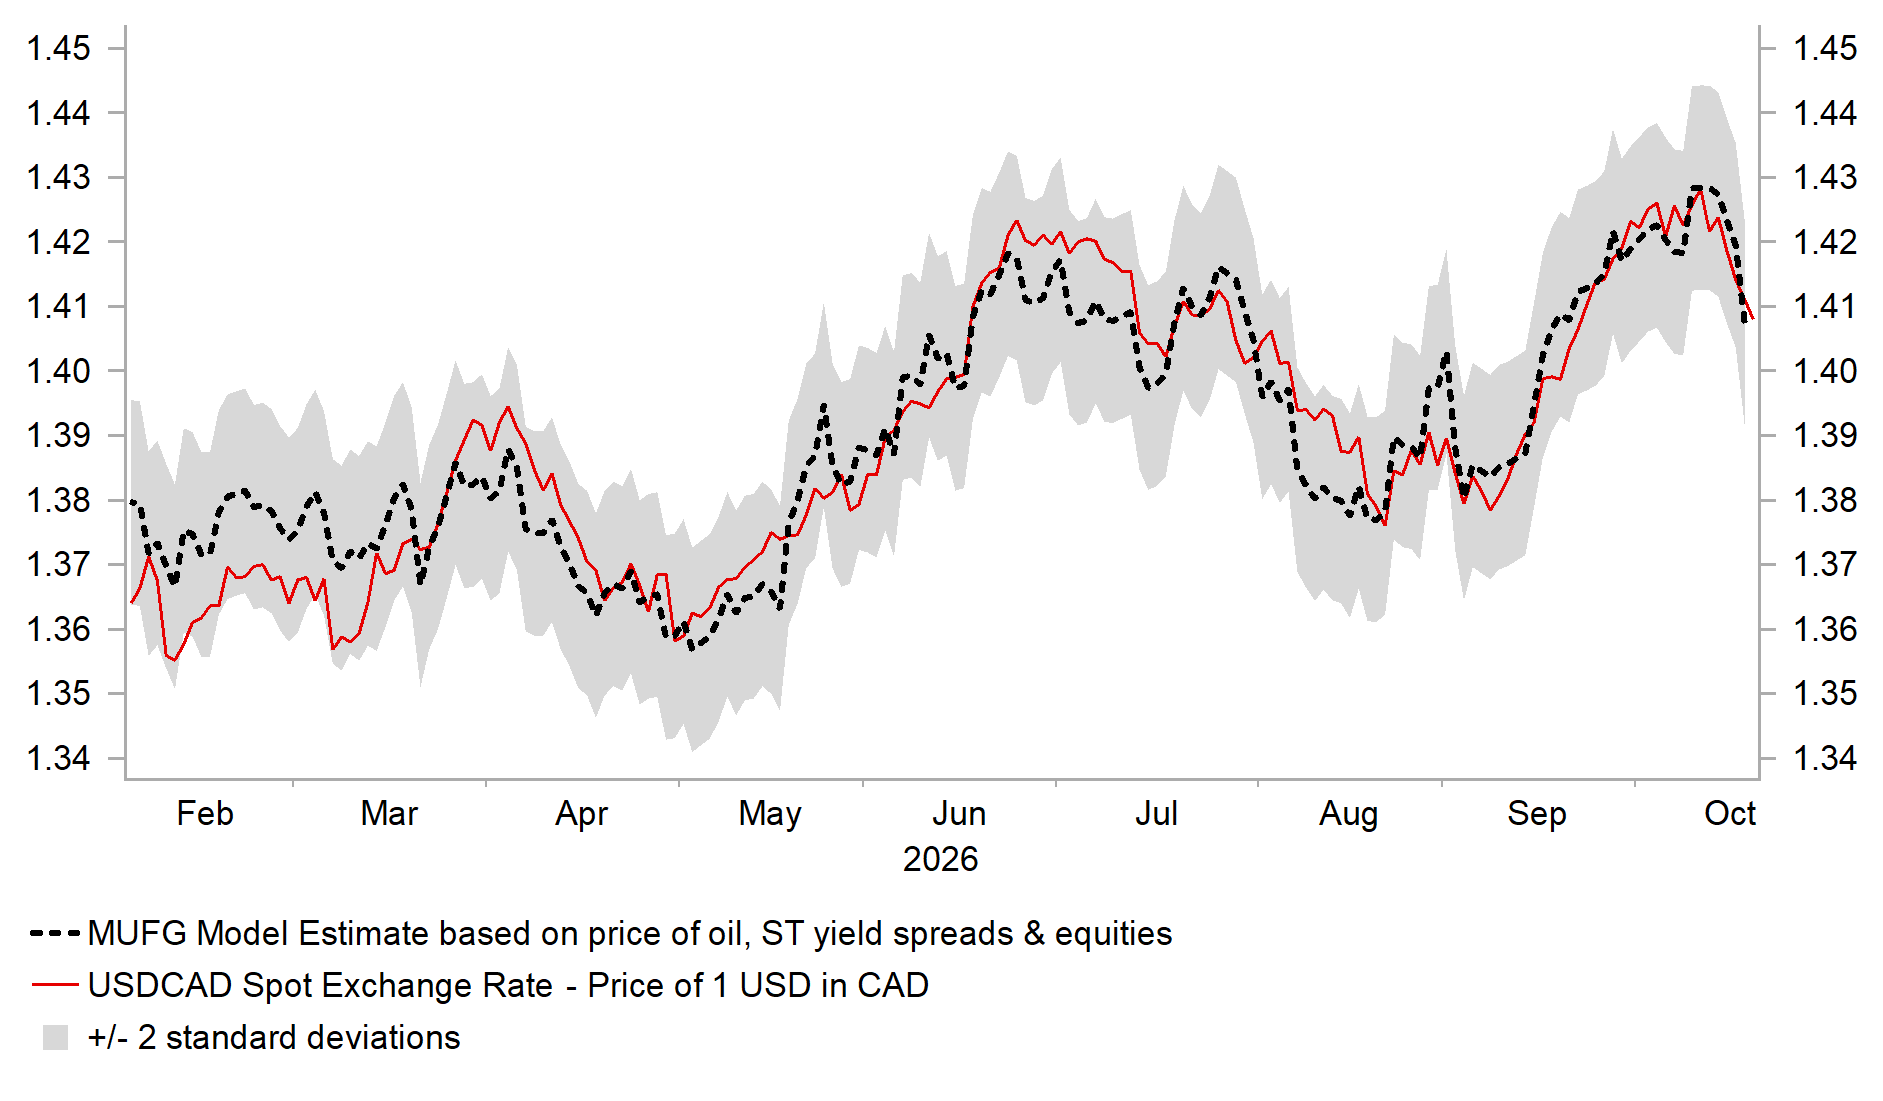
CAD SUPPORTED BY BOC RATE HIKE EXPECTATIONS
Source: MUFG Research, Macrobond, Bloomberg
CAD: BoC rate hike expectations move in favour of October hike
The Canadian dollar has continued to rebound against the US dollar resulting in USD/CAD hitting a low yesterday at 1.4071 as it moves further below the high from 14th October at 1.4300. The Canadian dollar has outperformed recently alongside the other G10 commodity currencies of the Norwegian krone and New Zealand dollar. The one exception has been the Australin dollar which has bene the worst performing G10 currency perhaps reflecting its tighter link to AI related demand. The recent wobble for AI-related trades may have weighed more on the Aussie than other G10 commodity currencies.
The Canadian dollar has been boosted by the hawkish repricing of BoC rate hike expectations. The Candina rate market has moved to more fully price in a 25bps hike as soon as next week. There are currently around 21bps of hikes priced in compared to only 9bps at the end of last week. Those expectations have been encouraged by three major Canadian banks all changing their rate calls to a hike at next week’s policy meeting. The latest inflation data from Canada released yesterday was mixed with headline and core inflation measures coming in a little softer than consensus forecasts at around 3.1% and 1.9% respectively in September. The BoC also released its latest business and consumer outlook surveys which found that households’ longer-term inflation expectations are rising. Roughly half of the businesses surveyed also plan to pass along some or all of their cost increases from higher energy prices and tariffs to customers.
The BoC has recently signalled that they are moving closer to hiking rates. If they place more weight on forward looking measures of inflation risks, and the Candina rate market continues to price in a high probability of a hike heading into next week’s meeting, we expect the BoC to pull the trigger and tighten policy. However, it is not a done deal given the recent softer economic data flow from Canada including the second consecutive month of heavy job losses in September. A decision to raise rates this month would then encourage speculation that they could follow that up quickly with a second hike before the end of this year in December providing more support for the Canadian dollar.
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
EU | 09:00 | Current Account | (Aug) | 29.2B | 27.6B | ! |
DE | 10:00 | German ZEW Current Conditions | (Oct) | -45.0 | -47.1 | !! |
EU | 10:00 | Construction Output (MoM) | (Aug) | - | 0.00% | ! |
DE | 11:00 | German Buba Monthly Report | - | - | - | ! |
US | 13:30 | Housing Starts | (Sep) | 1.300M | 1.275M | !! |
US | 13:30 | Building Permits | (Sep) | 1.390M | 1.403M | !! |
Source: Bloomberg & Investing.com