
Warsh focuses on AI rather than Fed policy
USD: Warsh reduces rate hike expectations by saying nothing
The US dollar is broadly unchanged following the comments from Fed Chair Warsh. All we got from Warsh on monetary policy was the repeat emphasis that the Fed would remain focused on achieving its inflation goal. The lack of comment on policy was seen by market participants of an endorsement of current market pricing that implies only a small chance of a hike in October. The probability of an October hike fell from 26% to 14% and the 2-year yield has fallen by 3-4bps. Warsh’s explanation for the lack of guidance was that he doesn’t “pre-judged meetings”. His comments on AI certainly suggested the near-term risks from this new technology was inflationary given his belief that AI would be a demand shock to the economy before it becomes a supply-side shock. He also added that AI would “fundamentally change the conduct of monetary policy” that over time likely means greater uncertainty over the reaction function of the Federal Reserve and other central banks. Another reason perhaps to assume that FX and rates volatility will be higher going forward.
G10 FX volatility is gradually picking up. 1mth implied volatility hit the highest level this month since April but has subsided back modestly although the average volatility level so far this month is also the highest since April. Higher yields has seen bond market volatility jump to highs not seen since March and that has spread to FX markets. LatAm carry positions have been unwound with the Chilean peso and Mexican peso by far the two worst performing currencies so far in October. Carry has been less popular in Asia but volatility related to AI remains evident. The Korean won is an incredible 16% stronger versus the US dollar this month despite the Kospi falling notably as the AI trade suffers. The won strength points to huge structural Korean corporate demand that is countering any equity market-related outflows. These big moves continue to highlight the potential for positions being unwound which could see the US dollar suffer given the recent strengthening and demand for the dollar.
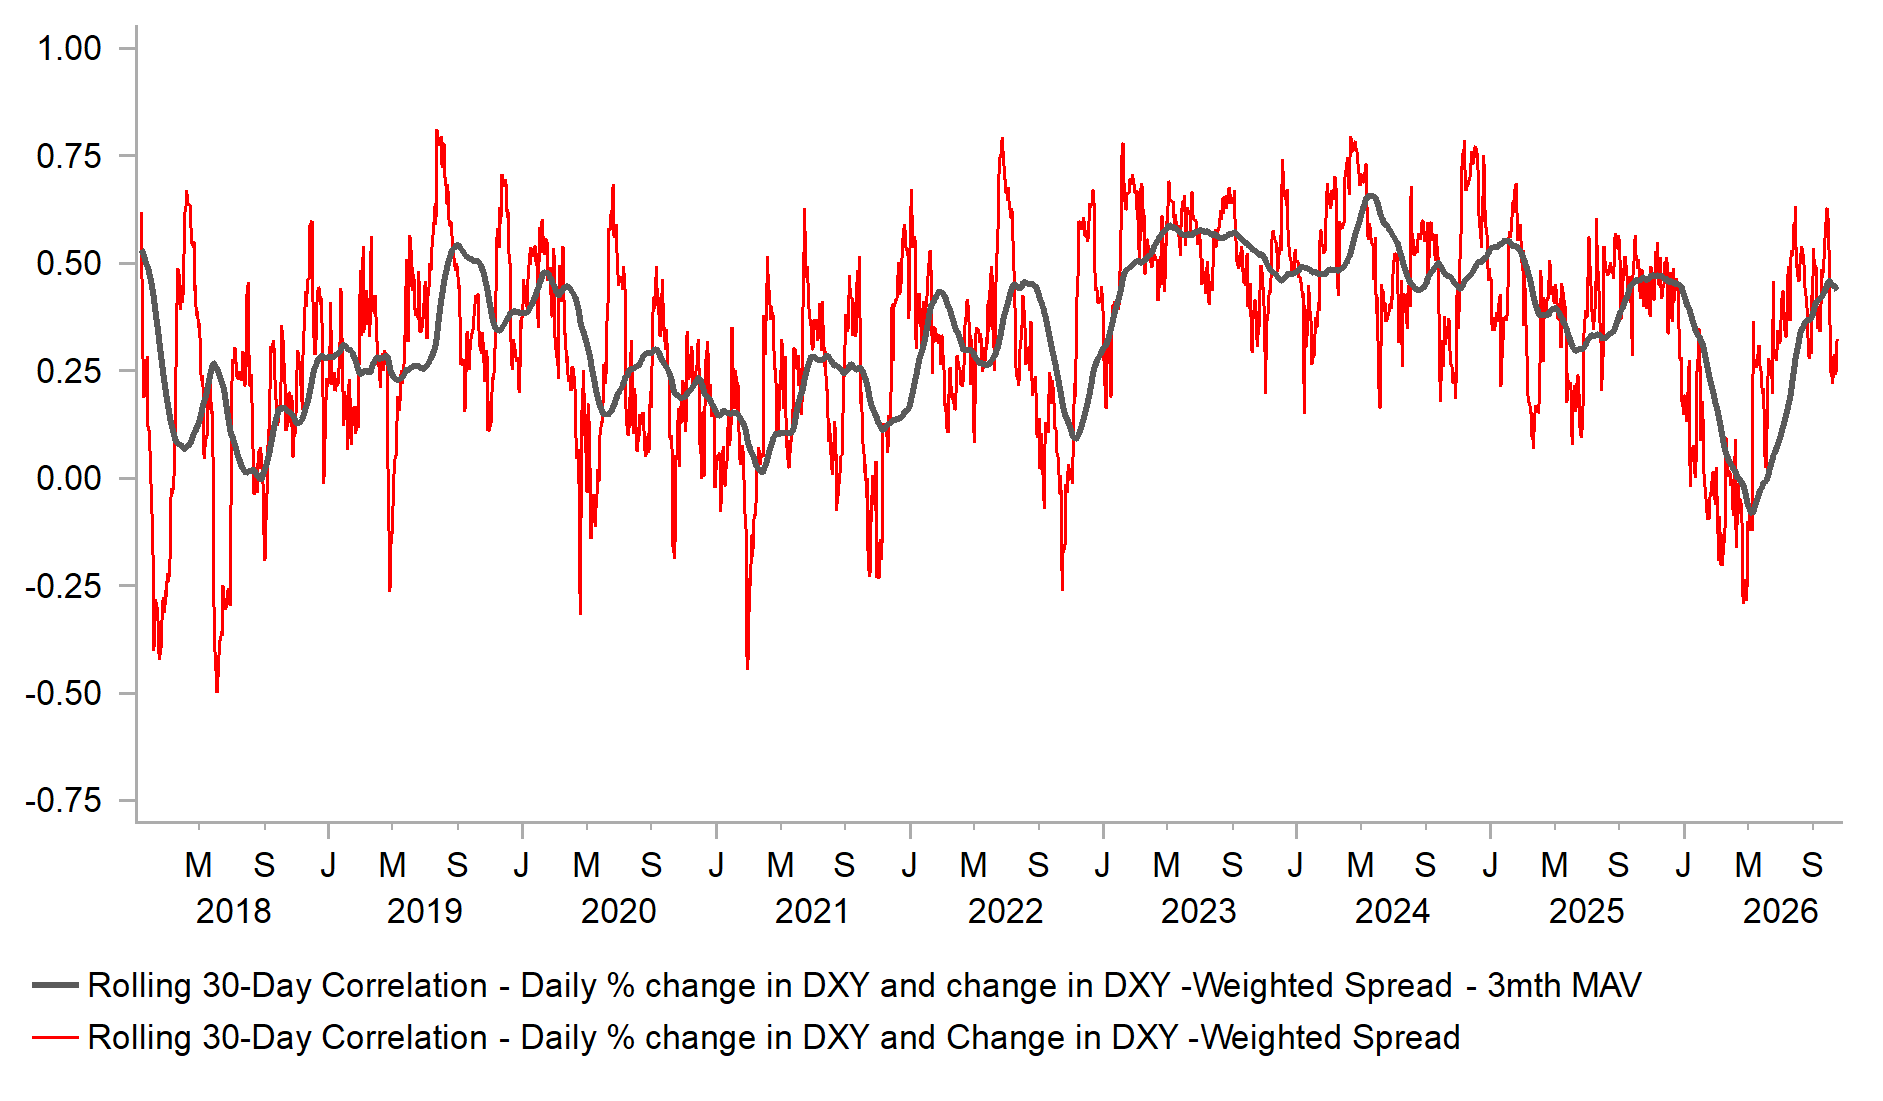
Warsh gave little away today that underlines the potential for surprises ahead under this new Fed regime. We will likely get a better understanding of that when numerous working groups will report findings, including on AI and inflation. A December rate hike is still very likely but the pricing of hikes in 2027 looks overdone, which was a view expressed by New York Fed President Williams this week – one of the more senior members of the FOMC. That richness in the yield curve will likely act to curtail near-term momentum for further appreciation of the dollar.
YIELD CORRELATION WITH THE US DOLLAR HAS STRENGTHENED
Source: MUFG Research, Macrobond, Bloomberg
GBP: BoE rate expectations still excessive
The pound continues to show resilience with economic data reinforcing expectations of monetary tightening by the BoE. The pound is roughly unchanged versus the US dollar since the end of June with only the energy-related CAD and NOK outperforming and the yen, helped by yen buying intervention by the MoF, with assistance from the US. So the pound has done well on the back of improving sentiment and evidence of economic resilience.
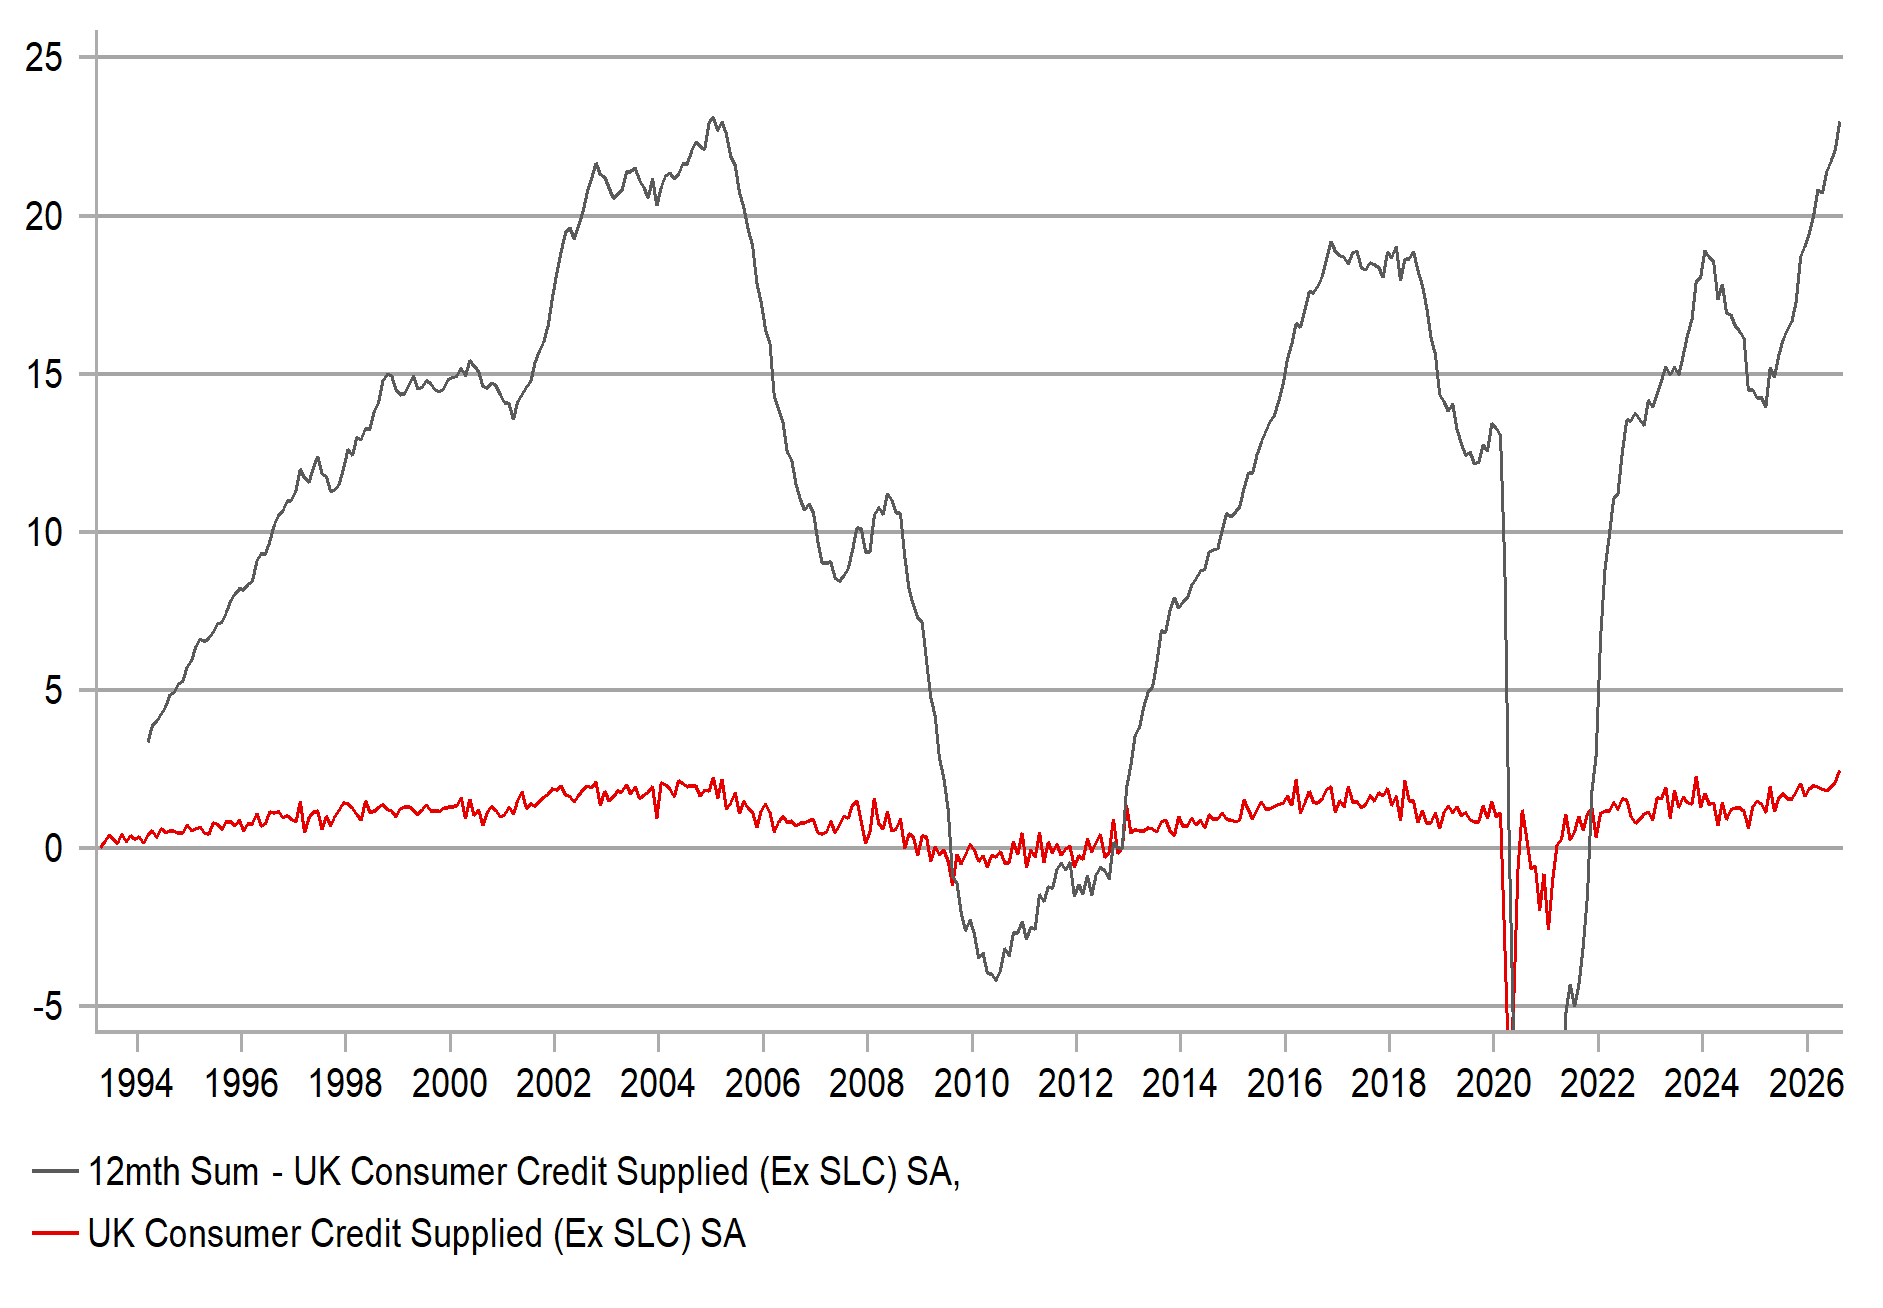
The data this week has helped. The GDP data again was stronger than expected – the m/m gain of just 0.1% was modest but still better than expected, helping the 3mth/3mth rate to 0.7%, 0.2ppt stronger than expected. The 3mth/3mth gain was helped by services activity although the one-month reading was flat in August and could be a sign of weakening momentum. The breakdown of the services sector showed consumer-facing weakness while a Bloomberg Intelligence survey released yesterday indicated vulnerabilities that could see a slowing in the months ahead. 55% of respondents stated that they couldn’t cover bills for more than 3mths, up 13pts from a year earlier. The BoE’s quarterly Credit Conditions Survey released earlier this month revealed an increase in defaults on credit card debt for the sixth consecutive quarter underlining the increased strains on UK consumers. Despite this these exposures are increasing with consumer credit up GBP 2.5bn in August to a new record high. If rates remain around these levels, it’s very likely that these figures will deteriorate further in the final quarter of the year. In addition to the onus of higher rates on borrowers, the OFGEM price cap increase will jump more notably in January after increasing by 4% this month.
So while the backdrop of the economic data has been positive, the outlook does point to increasing risks. The OIS market indicates 100bps of tightening is priced by next September and we continue to doubt the BoE delivering that, especially following the comments from Chief Economist Huw Pill who stated this week that he is sceptical that the UK will require four 25bp rate hikes. But it will be difficult for the markets to adjust lower given the global backdrop of higher rates. But in circumstances of a broader move back lower in rates, UK rates could fall more notably. The pound remains vulnerable to signs that recent economic resilience could be undermined by the notable move higher in yields.
UK CONSUMER CREDIT HAS HIT A NEW RECORD IN 12MTHS TO AUGUST
Source: Bloomberg, Macrobond, MUFG Research
KEY RELEASES AND EVENTS
Country | BST | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
EU | 10:00 | CPI (MoM) | (Sep) | 0.6% | 0.4% | !!! |
EU | 10:00 | CPI (YoY) | (Sep) | 3.8% | 3.2% | !!! |
EU | 10:00 | Core CPI (MoM) | (Sep) | 0.2% | 0.2% | !!! |
EU | 10:00 | Core CPI (YoY) | (Sep) | 2.5% | 2.4% | !! |
EU | 10:00 | Trade Balance | (Aug) | - | 14.2B | ! |
CA | 13:15 | Housing Starts | (Sep) | 234.0K | 229.0K | ! |
US | 13:30 | Import Price Index (MoM) | (Sep) | 0.9% | 0.7% | ! |
US | 13:30 | Export Price Index (MoM) | (Sep) | 1.0% | 0.6% | ! |
US | 14:15 | Industrial Production (MoM) | (Sep) | 0.4% | 0.0% | !!! |
US | 14:15 | Industrial Production (YoY) | (Sep) | - | 1.42% | ! |
US | 14:15 | Capacity Utilization Rate | (Sep) | 76.5% | 76.3% | ! |
US | 14:15 | Manufacturing Production (MoM) | (Sep) | 0.3% | -0.3% | !! |
US | 19:00 | Federal Budget Balance | (Sep) | -34.7B | -167.0B | !! |
US | 21:00 | TIC Net Long-Term Transactions | (Aug) | 75.2B | -27.9B | !! |
Source: Bloomberg & Investing.com