
Unified FOMC message but 50bp hike still seems unlikely
USD: Williams adds a bit of balance to policy outlook
The US dollar is consolidating at new highs above the 103-level on DXY, levels not seen since the Liberation Day period in April 2025. From the intra-day low last Friday, the 2-year UST bond yield has jumped 45bps to the high today – the move is the largest 5-day move since November 2022 and if maintained will continue to provide support for the dollar. A global Microsoft outage will like add to the recent poor tech sentiment that may intensify recent risk aversion, which in turn will hurt the high-beta G10 currencies further versus the US dollar. SEK, AUD are two of the worst performing G10 currencies this week. In fact one of the biggest safe-haven currencies is the worst performing – CHF. This likely reflects the surge in global yields and the reduced risks associated with France with the OAT-Bund spread considerably narrower.
The 2-year yield has now stabilised and that was in part a reflection of the comments from New York Fed President Williams. A centrist with dovish leanings the markets view him as a more pragmatic voice. While he described inflation as “far too high” he then added that “we’ll need to take actions over time that will ensure we get inflation back to our 2% goal” but that the Fed must make “sure that we don’t do undue harm to our maximum employment mandate”. He also stated that he didn’t think the economy was out of balance. These comments certainly suggest Williams would not be in the camp of pushing for a larger 50bp hike in December. Williams also highlighted the vulnerability of the US economy to a change in enthusiasm for AI. Given the evidence of AI in the latest Q3 GDP report that is something we have highlighted as well – can US personal consumption growth continue such strong growth (3.8% Q/Q SAAR in Q2 & Q£) when real disposable income is trending weaker and current is at just 1.0% YoY, way below current consumption growth.
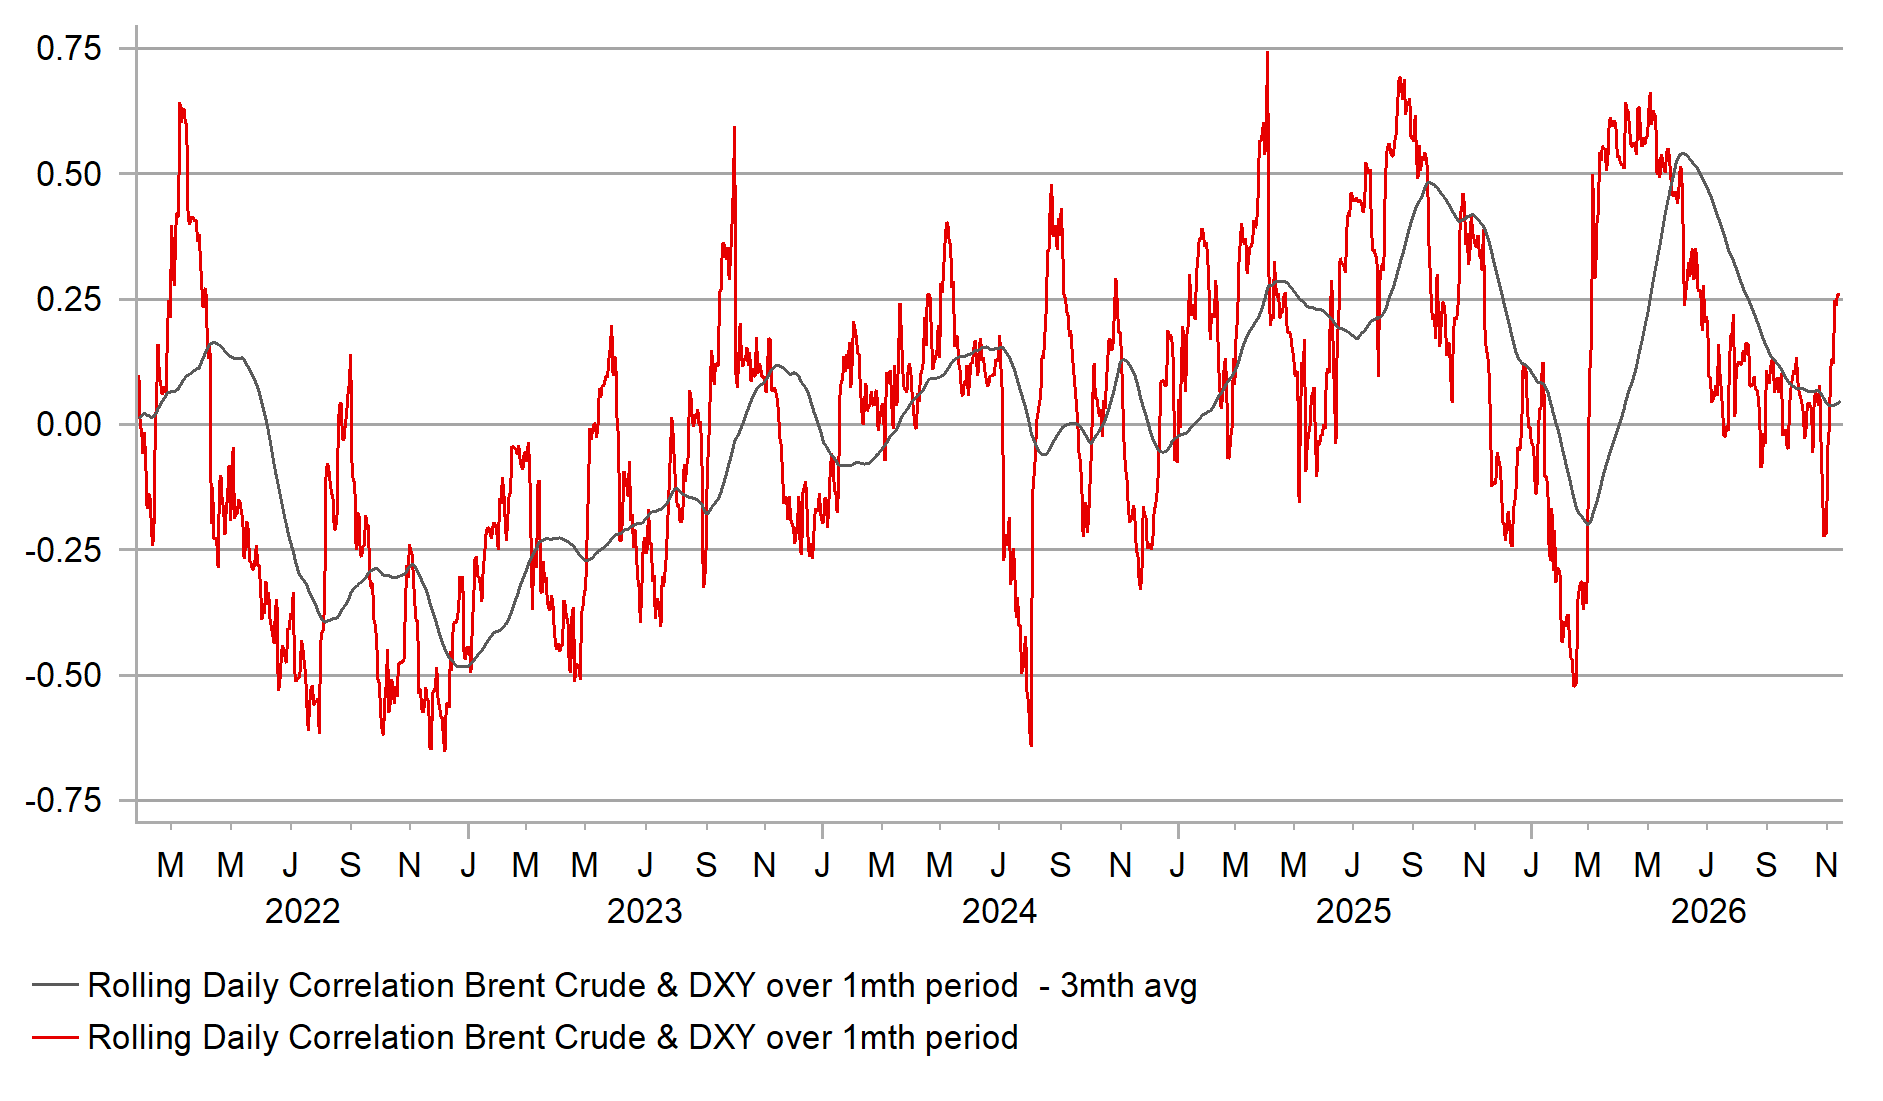
Still, while a 25bp rate hike from the Fed is the base-case, we need to be mindful of the risks. Another strong jobs report and a further rebound in energy prices would likely see further pricing for a 50bp move, or a number of back-to-back hikes – we are close to priced for a back-to-back hike in Dec-Jan and about 10bps short of three consecutive 25bp hikes through to March. The reversal of optimism over an end to the US-Iran conflict has reinforced this pricing and higher front-end yields. Brent crude oil is 8.5% higher from the intra-day low on Tuesday. Trump’s suggestion that no Iran deal is required points to a more prolonged period of energy supply uncertainties.
While Williams may have taken some of the upward momentum out of the yield move higher, the global backdrop suggests elevated to higher yields will persist and hence points to further dollar strength. One source of US dollar selling might come from Japan. FM Katayama has again warned against “sharp, one-sided” FX moves and underlined the close relationship with the US. However, US support is largely verbal with data released showing the US bought just USD 500mn worth of JPY in the joint intervention with Japan on 31st July. The US may want a weaker yen but the heavy lifting will have to come from Japan in countering any renewed yen weakness.
US DOLLAR CORRELATION WITH BRENT CRUDE OIL IS TURNING STRONGER ONCE AGAIN
Source: MUFG Research, Macrobond, Bloomberg
AUD: Retracement continues on Fed & AI
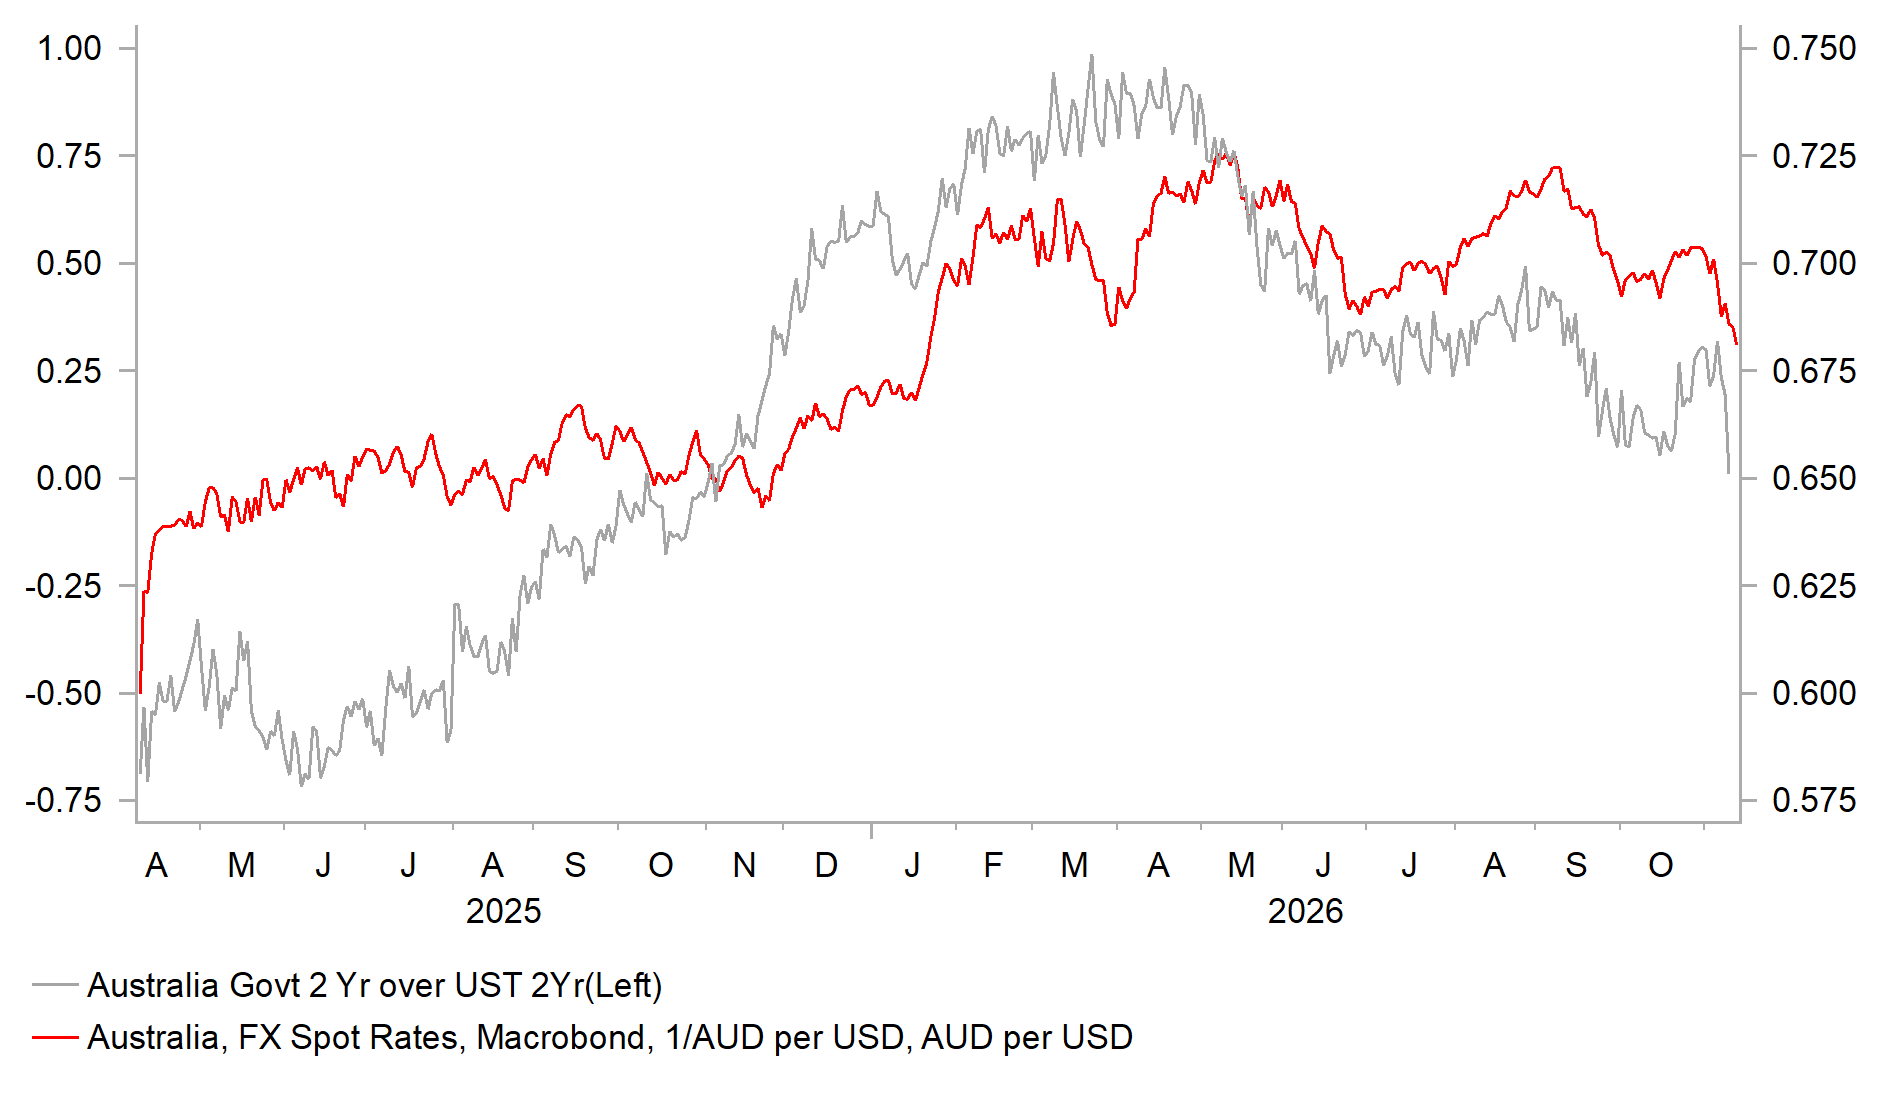
The pre-emptive nature of monetary tightening in Australia has benefitted the Australian dollar but time appears to have run out for providing support for the currency as investor conclude that RBA is running out of scope for additional rate hikes at a time when investors are reappraising their views on additional Fed rate hikes. The RBA has hiked on five occasions this year and the policy rate at 4.85% is the highest since 2008 when the RBA was cutting rates into the Global Financial Crisis. The pre-emptive action this year means the OIS curve through to Q4 2027 shows mostly a flat curve but a probability of a rate cut (-15bps priced) in Q3-Q4 next year. At the same time given the Fed has raised rates just once, the market has another 85bps of hikes priced – that’s a 100bp swing in expected policy rates by Q4 next year. The 2-year AU-US swap spread has moved 100bps lower since peaking in early April and has dropped 30bps just in the last week or so. The RBA vote when it hiked this month (6-3) underlined the growing opposition to hikes and RBA Governor Bullock signalled a pause to assess given some of the tightening will not have hit the real economy. But where you’d expect to see it first has started to come through – Australian home loans plunged 15.5% in Q3, double what was expected and the biggest drop in the data series back to 2002.
AI risks are adding to AUD underperformance. Data-centre rollouts are significant in Australia with investments doubling since 2023. Australian Energy Market Operator (AEMO) estimates that data-centre share of electricity consumption was around 3% in 2025 versus 4.9% in the US and 1.5% on average globally.
We view AUD as probably the most vulnerable currency in a sharp AI-related sell-off. It has a relatively high macroeconomic exposure, it also has energy and commodity exposures that would result in a negative terms of trade hit and AUD is high-beta and hence would underperform in a scenario of tightening financial conditions and a rise in financial market volatility. In the recent 6-day period of AI selling through to 5th November, AUD was the worst performing G10 currency. Despite the AUD sell-off from the most recent high in September, AUD is still the 2nd best performing G10 currency on a year-to-date basis. If the AI sell-off intensifies again, AUD remains more vulnerable than other G10 currencies.
RATE SPREAD STARTS TO MOVE MORE AGAINST AUD/USD AS RBA PAUSES
Source: Bloomberg, Macrobond, MUFG Research
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Consensus | Previous | Mkt Moving |
US | 09:00 | IEA Monthly Report | - | !!! | ||
EU | 10:00 | Trade Balance | (Sep) | -4.5B | -16.1B | ! |
EU | 10:00 | GDP (YoY) | (Q3) | 1.30% | 0.50% | !!! |
EU | 10:00 | GDP (QoQ) | (Q3) | 0.40% | 0.60% | !!! |
EU | 10:00 | Employment Change (QoQ) | (Q3) | 0.20% | 0.10% | ! |
EU | 10:00 | Employment Change (YoY) | (Q3) |
| 0.50% | ! |
US | 13:30 | PPI (MoM) | (Oct) | 0.40% | 1.30% | !!! |
US | 13:30 | Core PPI (MoM) | (Oct) | 0.30% | 0.70% | !!! |
US | 13:30 | PPI (YoY) | (Oct) | 6.60% | 6.30% | ! |
US | 13:30 | Core PPI (YoY) | (Oct) | 5.00% | 5.00% | ! |
CA | 13:30 | Manufacturing Sales (MoM) | (Sep) | 0.10% | 1.50% | ! |
CA | 13:30 | Capacity Utilization Rate | (Sep) |
| 81.90% | ! |
US | 14:10 | Fed Collins Speaks | - |
|
| !!! |
US | 14:40 | Fed Logan Speaks | - |
|
| !! |
US | 15:50 | FOMC Member Bowman Speaks | - |
|
| !!! |
US | 17:00 | FOMC Member Daly Speaks | - |
|
| !!! |
Source: Bloomberg & Investing.com