
USD weakens alongside continued move lower in energy prices
USD: Correcting lower ahead of today’s US CPI report
The US dollar has continued to trade at weaker levels overnight after giving back all of its gains yesterday following the release of the stronger NFP report on Friday. The dollar index has fallen to a low overnight at 101.54 as it moves further below the high from Friday at 102.36. The US dollar has been undermined in part by the sharp ongoing adjustment lower for energy prices this month. The price of Brent has fallen back towards USD90/barrel for the first time since the end of August. For this month as a whole, the price of Brent has now fallen by around 23% which is the sharpest sell-off since between May and June. The worst performing G10 currency during that period was the Norwegian krone which has again underperformed this month. The sharp ongoing adjustment lower for energy prices has been encouraged by renewed investor optimism over progress towards a US-Iran deal following the US mid-term elections. Investor optimism over a deal was encouraged further overnight by comments from President Trump who told reporters that “Iran, militarily, is effectively over”. It followed a meeting earlier in the day between President Trump and Qatari Prime Minister Mohammed bin Abdulrahman Al Thani who later posted that he was “grateful for the positive discussions on reaching a deal and bringing peace to the region”.
The move lower in energy prices is also helping to bring down government borrowing costs. The 10-year US Treasury yield has fallen by 50bps from last month’s high of 5.36%. If there is further progress towards a US-Iran deal to end the conflict it would help to sustain lower energy prices and ease pressure on major central banks including the Fed to keep hiking rates. The main focus today will be the release of the latest US CPI report for October. It will be closely scrutinized by market participants and the Fed to assess if there is evidence of broadening inflation pressures beyond higher energy prices. Core inflation has surprised to the upside for two consecutive months putting pressure on the Fed to tighten policy, although the consensus forecast for today expects some relief with the monthly change in core CPI forecast to slow to0.2%M/M in October. The US rate market still expects the Fed to hike rates again as planned at the end of this year in December but has been scaling back expectations for further hikes in 2027. Market participants now only expect one additional hike in 2027. A December hike has been more fully priced back in after the stronger NFP report on Friday and the rebound in US AI-related/tech stocks overnight. The Nasdaq composite index rebounded by 2.7% and closed back above support from the 200-day moving average at around 25,107.
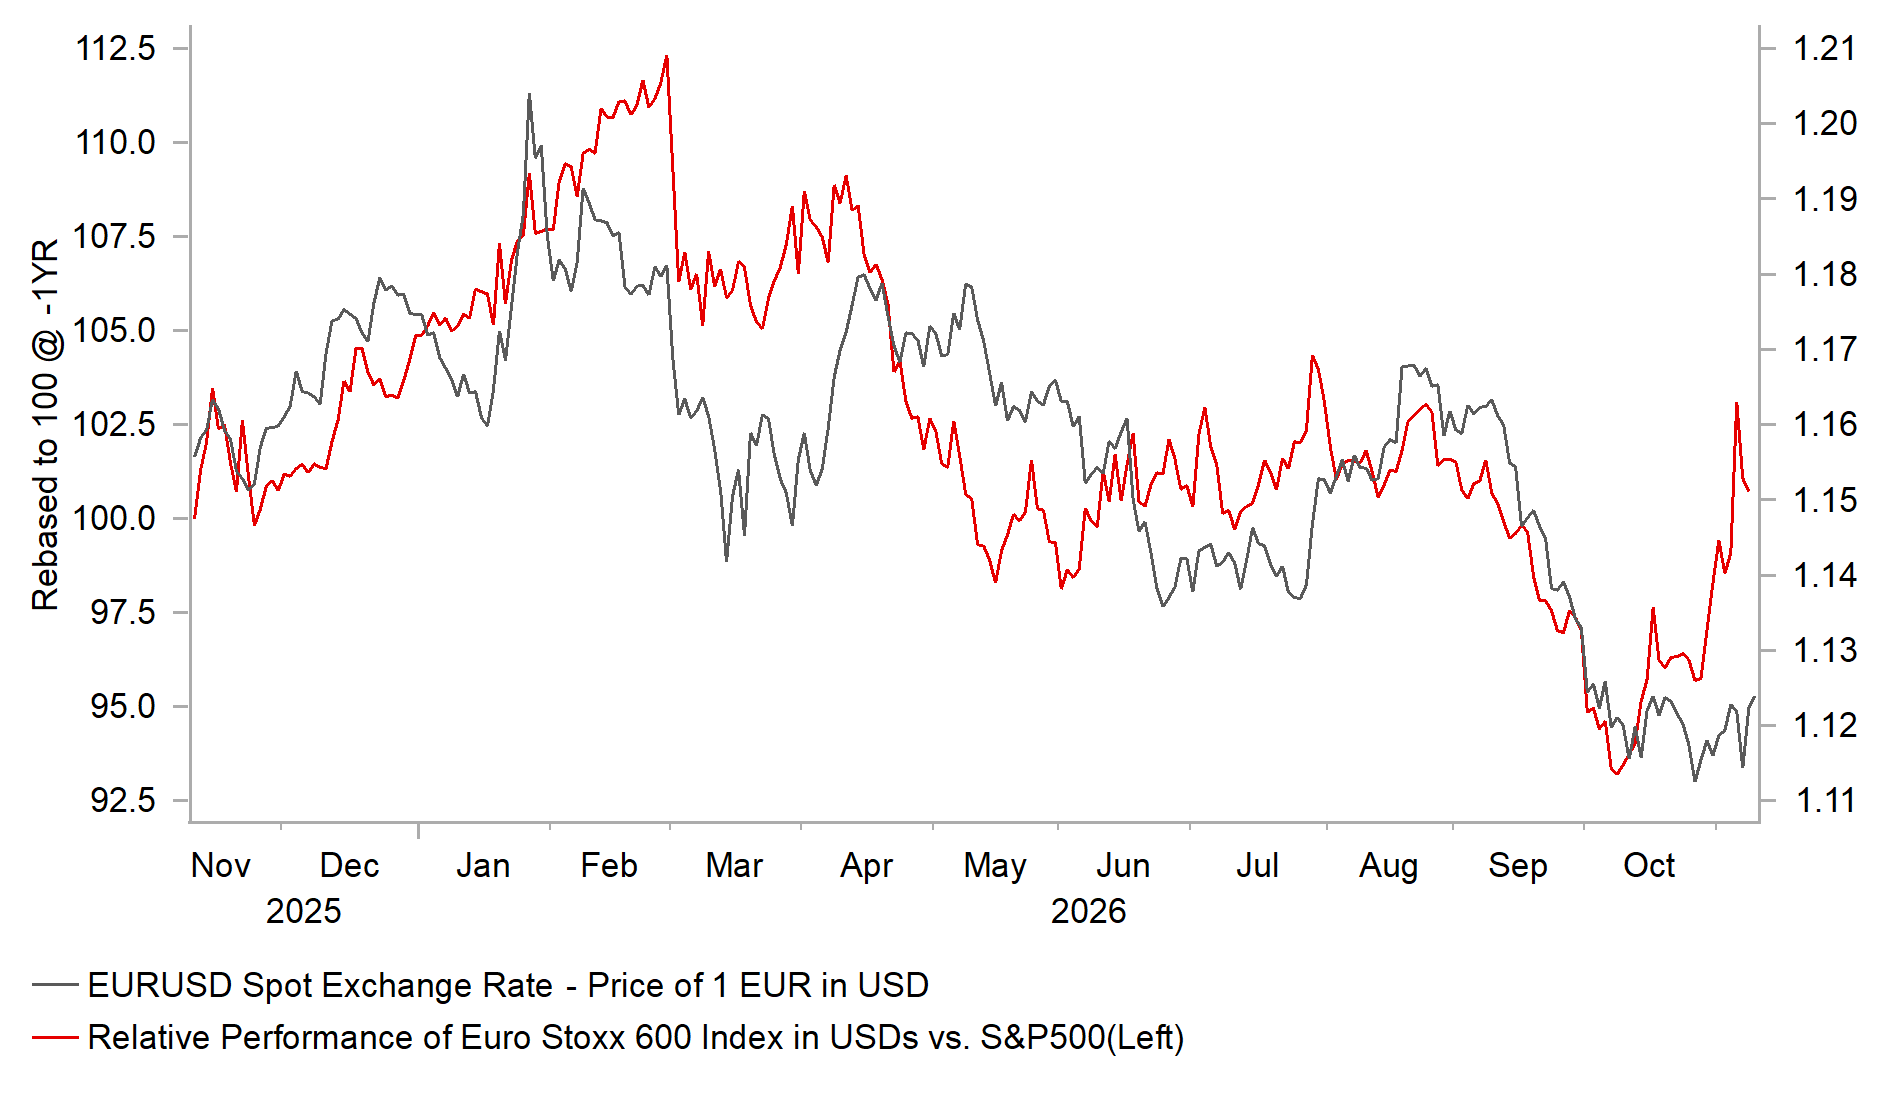
EUROPEAN EQUITIES HAVE OUTPERFORMED RECENTLY
Source: MUFG Research, Macrobond, Bloomberg
EUR: Easing of external headwinds provides some relief
The euro is staging a relief rally encouraged by lower energy prices, which if sustained would help ease headwinds for euro area economies. The recent unfavourable combination of higher energy prices and government borrowing costs particularly in France has reinforced euro selling pressure. The release of the latest IMM positioning report at the end of last week revealed leveraged funds are heavily short the euro. Short euro positions have increased sharply since mid-September and have hit their highest level since the start of the COVID shock in early 2020. It leaves the euro vulnerable to a short squeeze in the near-term if the investor concerns over the scale of the energy shock continue to fade.
At the same time, the yield spread between 10-year French and German government bonds has narrowed alongside lower energy prices. The yield spread has narrowed to around 145bps down from a recent high of around 175bps in October. The recent narrowing has been encouraged by positive external developments rather than domestic fiscal policy developments in France. The price action highlights that further progress towards a US-Iran deal would help make it easier for French politicians to restore investor confidence. The reduction in French fiscal risk and rebound for AI-related stocks yesterday contributed to the Swiss franc underperforming yesterday.
KEY RELEASES AND EVENTS
Country | GMT | Indicator/Event | Period | Forecast | Previous | Mkt Moving |
GB | 08:30 | BoE Breeden Speaks | - | ! | ||
US | 09:00 | Fed Waller Speaks | - | !! | ||
US | 11:00 | NFIB Small Business Optimism | (Oct) | 98.0 | 97.9 | ! |
US | 13:30 | Core CPI (MoM) | (Oct) | 0.2% | 0.3% | !!! |
US | 15:00 | Cleveland CPI (MoM) | (Oct) | 0.2% | ! | |
EU | 16:45 | ECB's Lane Speaks | - | !! | ||
GB | 18:30 | BoE MPC Member Pill Speaks | - | !! | ||
CA | 18:30 | BOC Summary of Deliberations | - | ! |
Source: Bloomberg & Investing.com