
Caught in the cross-currents of AI, yields, oil and capital flows
Download the full PDF report using the link above.
Week Ahead FX outlook:
Global markets were volatile this week, with the US midterm elections initially pushing Treasury yields lower and triggering renewed selling in semiconductor stocks. The USD weakened initially but subsequently rebounded amid the tech sell-off induced safe-haven demand and a renewed focus on the Fed rate outlook. Overall, Asia FX remained stable, but with significant divergence: KRW and TWD underperformed amid renewed semiconductor equity weakness, while INR and PHP were the strongest regional currencies.
The USD and rates factors should remain the dominant global driver next week, with the focus shifting from the labor market to inflation. US CPI on Tuesday and PPI on Friday will be important for the market’s assessment of the Fed path and US Treasury yields. A stronger-than-expected inflation print would likely push US yields and the USD higher and weigh on Asia FX broadly, while softer inflation would provide some relief. However, we expect regional differentiation to remain significant, with oil exposure, domestic policy settings and equity-flow dynamics continuing to matter.
China inflation will be the main macro focus early next week, with October CPI and PPI due on Monday. Subdued inflation would reinforce the case for maintaining an accommodative PBOC liquidity stance, particularly following the recent shift in its operating framework toward the overnight reverse repo rate. For CNY, however, October trade data should be more important: continued export resilience and a large trade surplus would reinforce the strong external balance that has provided underlying support for the currency in recent months. Against this supportive backdrop, near-term USD/CNY direction should remain largely driven by the broader USD/rates environment and China’s external balances.
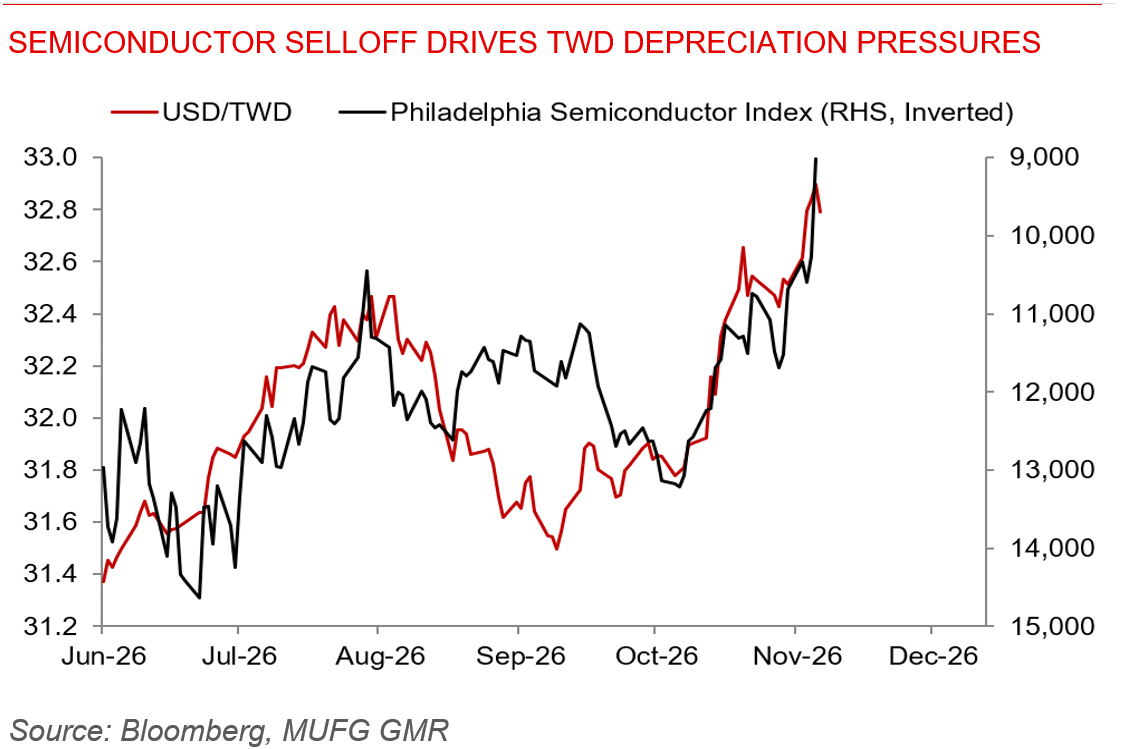
Asia FX performance is increasingly being shaped by the global technology cycle and cross-border portfolio flows. TWD and KRW remain particularly sensitive to semiconductor equity performance, with tech-sector moves likely to drive foreign equity flows and amplify currency swings. While we expect strong export data from South Korea and Taiwan next week to underscore resilient external fundamentals, near-term FX performance is likely to remain more closely tied to global tech sentiment and associated portfolio flows.
Semiconductor selloff drives TWD depreciation pressures