
Week Ahead FX outlook:
Key FX views:
This week's market focus centered on the Fed and BOJ policy meetings, both of which resulted in 25bp rate hikes as expected. The Fed's latest economic projections indicate scope for one further hike this year, supporting expectations of a prolonged period of restrictive policy. By contrast, the BOJ struck a less hawkish tone than some investors had anticipated, leading markets to scale back expectations for the future policy rate path. The policy divergence supported a stronger US dollar, pushing the DXY index and USD/JPY higher.
Next week, market likely shifts focus on preliminary September PMIs across the US, Eurozone and Japan, alongside US housing and labor-market data. Consensus expects US activity to remain resilient, with the services PMI holding around 56.0 and the manufacturing PMI at 53.6, while Eurozone activity expanding by a slower pace suggested by a September composite PMI of 51.5 compared with August’s 52. Market also expects some recovery from US housing data. These data are expected to reinforce the narrative of resilient US growth and support expectations of one additional 25bp Fed hike by year-end.
In Asia, key releases next week include Singapore CPI, trade data from South Korea, Thailand Hong Kong and Taiwan. Consensus expects a modest acceleration of both South Korea and Thailand’s exports growth.
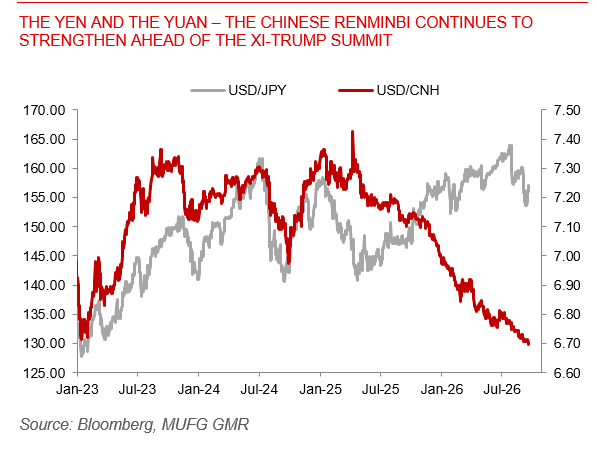
Markets will also closely watch the Xi-Trump meeting in Washington on 24 September for signals on the future direction of US-China relations. Economic and trade issues are expected to dominate discussions, while technology and AI-related restrictions are likely to remain key areas of contention. Our base case is that both leaders reaffirm high-level dialogue, make incremental progress on trade communication, risk management and crisis-prevention mechanisms, but deliver limited breakthroughs on technology controls. Any constructive post-meeting statement would be supportive for Chinese assets and regional supply-chain beneficiaries.
The Yen and the Yuan – the Chinese Renminbi continues to strengthen ahead of the Xi-Trump summit