
Download the full PDF report using the link above.
BSP, BI and BOK policy decisions amidst tech-led risk-off
Week Ahead FX outlook:
The focus in Asia will be on central bank policy decisions by Indonesia, Philippines and South Korea, China’s macro data, coupled with whether the tech and semiconductor-led risk-off sentiment continues into next week.
In particular, we see BSP raising rates by 25bps next week, bringing the policy rate to 5.25% from 5.00%, given higher oil prices and the risk of a Super El Niño, while we expect the Bank of Korea to keep rates on hold at 3.00% after back-to-back hikes. While the consensus expects Bank Indonesia to keep rates on hold at 5.75%, MSCI’s announcement on Friday (16 October) that Indonesia’s continued emerging-market classification was no longer appropriate sent the JCI down more than 10% and put pressure on IDR. These developments lead us to forecasting a 25bp hike next week to 6.00%, followed by a further 25bp hike to 6.25% by end-2026.
Meanwhile, China’s third-quarter GDP and September activity data are expected to show some stabilisation with stronger public investment and buoyant exports supporting industrial production, although the composition of growth likely remains uneven amid continued weakness in private investment and household consumption. Markets will also monitor the APEC finance ministers’ meeting in Hong Kong and remarks from PBOC Governor Pan Gongsheng at Beijing’s Financial Street Forum for indications of China’s policy direction.
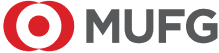
These events will also unfold against a fragile market backdrop following the technology and semiconductor-led equity sell-off. Concerns over AI financing, the sustainability of infrastructure spending and elevated valuations have driven heavy losses in semiconductor shares, with the KOSPI falling by 15% this week and large foreign outflows weighing particularly on the Korean won and the Taiwan dollar in the near-term. However, it is important to note that KRW and TWD have been very resilient before this sell-off. The associated flight to safety has also supported US Treasuries and lowered US yields, and the week ahead will test whether this represents a temporary position adjustment or a more persistent reassessment of the AI investment cycle.
The Tech sell-off weighs on KRW and TWD