
Staying selectively cautious as the dollar firms
Ahead Today
G3: US Initial Job Claims, Wholesale Inventories
Asia: Taiwan exports
Market Highlights
The US dollar remained firm, with DXY rising around 0.4%, while the 10-year Treasury yield stayed elevated at around 5.3%, about 112bp above its start-of-year level. The continued sell-off in US Treasuries is becoming an increasingly important driver for global markets. Should long-end yields rise further, market attention could shift towards the broader tightening in US financial conditions and whether policymakers begin to signal greater concern over Treasury-market conditions
The FOMC minutes added to the backdrop of higher US rates. The minutes confirmed that September's 25bp hike was backed by all 19 officials and indicated that most participants viewed another increase in the fed funds target range as likely appropriate by year-end. Some of them also highlighted continued concern over inflation risks and the case for maintaining a higher rate path on risk-management grounds.
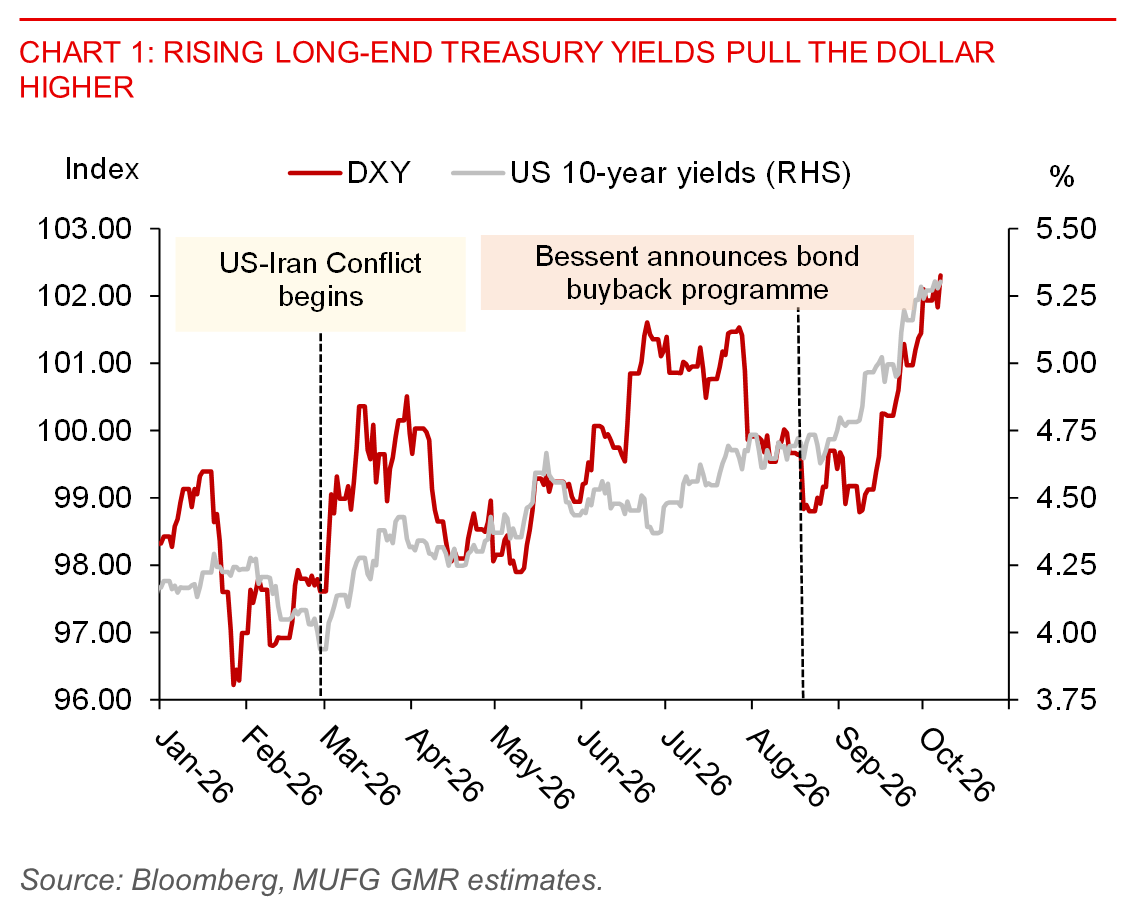
For Asia FX, we remain cautious on selective emerging-market currencies. DXY is around 3.2% stronger since Jackson Hole, while dollar positioning does not appear stretched, in our view, to provide a strong contrarian case for Asian currencies. While Asian bond yields have also been rising, that has not translated into stronger currencies, particularly when the increase is also taking place alongside a large global repricing of duration and persistent dollar strength.
INR remains one of the currencies where we would stay cautious despite a hawkish RBI. The RBI’s 25bps rate hike yesterday to 5.50% was in line with market expectations. The RBI policy tightening, along with the shift in stance from neutral toward “calibrated tightening”, reinforce concern over inflation risks. Focus could now shift towards how quickly the RBI intends to proceed with further policy tightening and whether inflation pressures would continue to broaden in the months ahead (see here).
Meanwhile, the latest round of foreign reserves data yesterday across Asia (China, Singapore, Malaysia, Philippines, India) was broadly in line with market expectations. But they are useful for assessing how regional economies are currently navigating the backdrop of elevated US yields, high oil prices, and a firmer USD.