
Asia tech-linked FX could outperform
Ahead Today
G3: Bank of Japan Governor Ueda speech, Japan JGB auction, Fed Musalem and Bowman speech
Asia: Philippines inflation, Thailand inflation, India HSBC PMI
Market Highlights
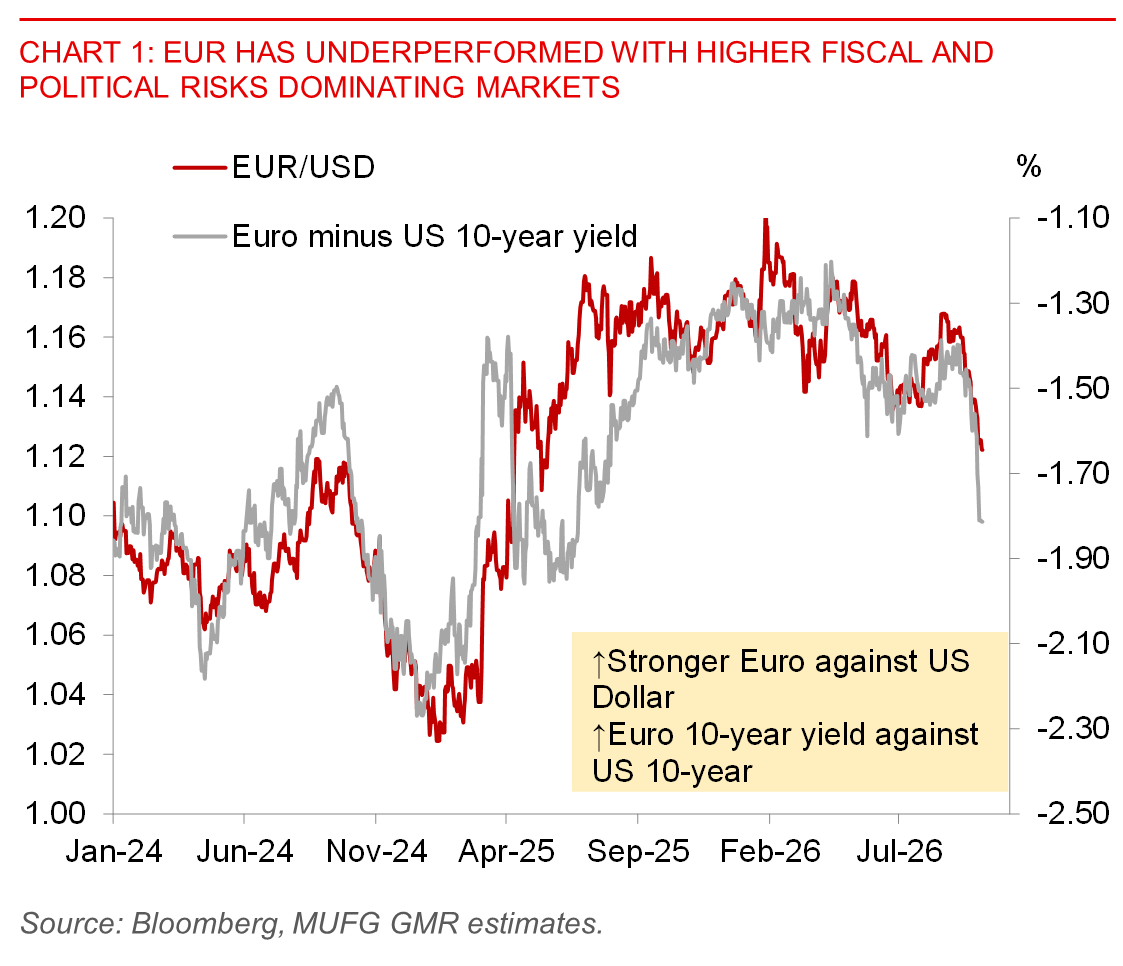
Political, economic and fiscal risks continue to dominate the outlook in Europe and as such the outlook for the EUR right now, while markets will look closely at BOJ Governor Ueda’s speech and today’s JGB 10-year auction to gauge sentiment towards the Japanese Yen and assets. In France, continued concerns around the political and fiscal backdrop ahead of next year’s Presidential elections are dominating markets, with opposition parties including far-right candidate Marine Le pen and far left rival Jean-Luc Mélenchon likely to advance to the second-round run-off. Meanwhile, Spanish Prime Minister Pedro Sanchez called for a surprise snap election in the midst of a housing affordability crisis, with polls pointing potentially for a heavy defeat for his party with the center-right People’s Party potentially working with the far-right Vox party. Of course France and Spain have different starting points, and in Spain the economic and fiscal outlook is better, but overall these developments underscore how politics have increasingly been dominant drivers of EUR and FX markets.
What’s also potentially adding fuel to the fire in the coming months is news that both Germany and France are urging the European Union to adopt new trade powers to cut off access to the EU single market if China or other nations destabilise trade relations. The suggestion came in a letter sent to European Commission President Ursula von der Leyen, with both countries urging the EU to more aggressively investigate whether entire sectors such as chemicals, plastics and hybrid cars are facing unfair competition from heavily subsidized imports with potential new tariffs. There were also other measures touted including encouragement of supply chain diversification.
Looking at Asia, it’s interesting that Asian currencies in general have been somewhat more resilient this time around relative to other currencies. We think this is due to AI exports remaining quite strong so far, while from an oil and oil product perspective especially diesel the supply situation in our region seems less acute relative to others. Concerns around unwinding of FX carry trades have earlier dominated markets and led to underperformance of Latam currencies but this has stabilised.
Moving forward, we see a good chance that Asia FX can outperform across a range of scenarios but with some continued dispersion across key FX pairs. We like the tech-linked currencies such as TWD and KRW, and to a smaller extent MYR and SGD. Given the political risks in Europe, it may make sense in the near-term to sell EUR against TWD or KRW. We have an existing trade idea to sell USD/TWD, and we now like switching to EUR as the funding currency instead in part to lower the cost of carry (sell EUR/TWD) (see Why US yields matter for Asia). We close out our existing idea of Paying INR 5y NDOIS (Entry 6.4767%, current spot 6.744%) ahead of RBI’s policy meeting tomorrow (see Pay INR rates post RBI minutes).