
Focus on FOMC
Ahead Today
G3: US FOMC Policy Rate decision, MBA Mortgage Applications, Wholesale Inventories
Asia: Thailand Policy Rate, India Industrial Production
Market Highlights
Markets are focused on today’s FOMC decision, with the Fed widely expected to leave the policy rate unchanged following September's hike. With little policy surprise anticipated, markets will turn to the guidance, if any, particularly whether elevated energy prices and inflation risks leave policymakers open to further tightening. A hawkish tone would reinforce rate hike expectations, keep US yields elevated, and weigh broadly on Asian FX.
On the US macro front, durable goods orders rose 1.8%mom in September, while core capital goods shipments suggest another solid contribution from business investment in Q3. Some resilience in US activity, along with elevated oil prices, could keep upward pressure on US yields in the near term, leaving Asian currencies with current account deficits particularly vulnerable.
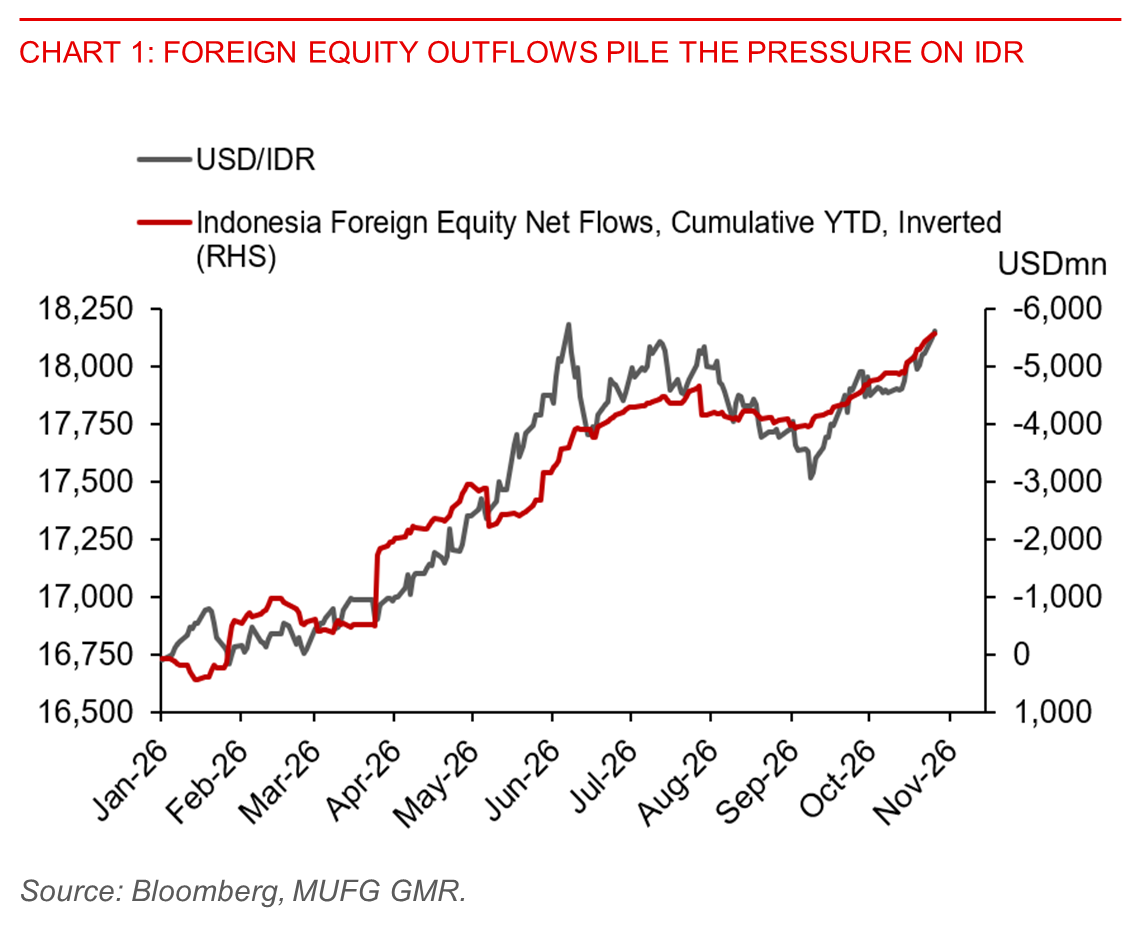
USD/IDR closed at 18,153 on Tuesday, leaving it within striking distance of the record high reached in June. More importantly, the move back towards these levels has persisted despite BI intervention efforts and recent measures to support the rupiah. The rupiah continues to face multiple headwinds from elevated US yields, higher oil prices, MSCI-related uncertainty, and net foreign equity outflows. As USD/IDR approaches the June peak, attention may increasingly shift from near-term currency stabilisation measures towards whether a more forceful policy response, such as further rate hikes, may be needed to arrest a further deterioration in the rupiah outlook.
Meanwhile, South Korea's Q3 GDP surprised to the upside, growing 3.4%yoy, exceeding market consensus of 3.1%yoy. AI-related semiconductor demand remained a key growth driver, supporting exports and investment even as private consumption weakened. The stronger growth backdrop reinforces the BOK’s hawkish bias and should offer some support to KRW, although broader USD moves and the semiconductor cycle will remain important drivers. SK Hynix, Korea’s memory chipmaker, reported a seven-fold increase in its quarterly profit.
We maintain our view that Bank of Thailand will leave its policy rate unchanged at 1.00%. While headline inflation rose to 2.82%yoy in September, close to the upper end of the BOT’s 1%-3% target range, policymakers are likely to look through oil-driven price pressures given still-subdued domestic demand. With household spending and domestic activity continuing to lag the export sector, the BOT is likely to remain cautious. This leaves THB relatively exposed to external headwinds, particularly elevated oil prices, US yields, and broader risk sentiment.