
Chip curbs cloud ASEAN’s tech boom
Ahead Today
G3: US MBI Mortgage Applications and Housing Starts, Eurozone CPI
Asia: Indonesia Policy Rate
Market Highlights
US economic data were mixed, with October headline retail sales rising 0.2%mom after September’s 0.8% increase, while industrial production fell 0.4%mom against expectations for a 0.1% gain. The underlying control-group retail sales (excluding auto, gas, building materials and food services) however, expanded strongly by 0.6%mom and that highlights continued underlying spending momentum. The dollar index remained resilient above 103.5, keeping the external backdrop challenging for Asia FX. Markets will now look to the October FOMC meeting minutes for insight into the pace of further tightening, alongside Thursday’s expected meeting between Xi Jinping, Donald Trump and Vladimir Putin in Shenzhen for signals on geopolitical relations.
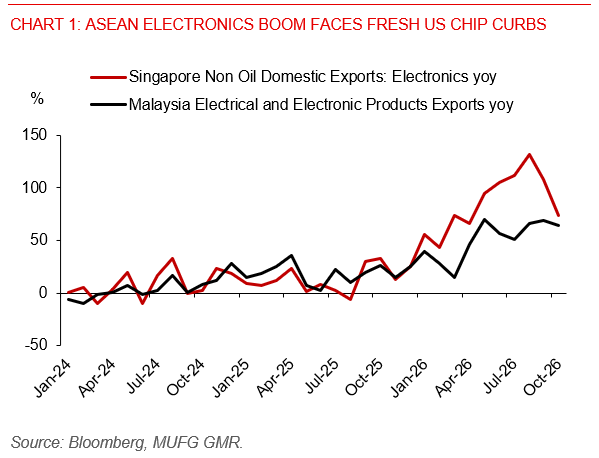
Fresh US chip restrictions put ASEAN’s technology-led expansion in focus ahead of the summit, with Singapore’s 73.9%yoy growth in October electronics exports underscoring the strength of the cycle now facing greater policy uncertainty. New licensing requirements covering Singapore, Malaysia, Thailand and Indonesia could complicate advanced-chip access and delay data-centre investment, although exemptions mean this is not a blanket ban. For regional FX, the restrictions could temper exports and weaken trade balances, while uncertainty over investment plans could weigh on capital and portfolio inflows.
INR continued to outperform, with USD/INR falling towards 93.48, the lowest since April, as foreign equity inflows reinforced the benefit of cheaper oil. Foreign investors have bought a net US$9bn of Indian equities this month as investors seek alternatives to the AI trade. Elevated forward premium also makes outright INR shorts more expensive, providing an additional cushion against depreciation pressure. India’s relatively limited exposure to semiconductor manufacturing helps explain its appeal amid the technology selloff, although sustained currency gains would require continued inflows rather than a temporary rotation alone.
USD/IDR remains well above 18,200 ahead of today’s Bank Indonesia decision, with persistent currency pressure and fragile investor confidence keeping policy in focus. We expect BI to raise rates by 25bps to 6.00%, as sharper Fed repricing and a resilient dollar increase the need to curb IDR’s depreciation. A hike would help preserve Indonesia’s yield appeal, support portfolio inflows and maintain a competitive rate differential as other major economies continue their tightening cycle.