
US CPI in focus as lower oil provides reprieve
Ahead Today
G3: US CPI
Asia: China Trade Data, Malaysia Industrial Production
Market Highlights
Attention turns to US CPI today after stronger payrolls reinforced the risk of further Fed tightening. October employment rose 165k versus 70k expected, alongside upward revisions to September and a decline in unemployment to 4.1% from 4.2%. Markets now price more than an 80% probability of a December hike. October headline and core CPI are expected to slow to 0.3%mom and 0.2%mom, respectively. A downside inflation surprise would challenge rate hike expectations and could weigh on the dollar.
Global equities stabilised after last Thursday’s tech-led selloff, but concerns around AI valuations and the sustainability of capex spending remain an overhang. Brent fell below $95/bbl on some diplomatic optimism, while the dollar softened despite stronger US payrolls. For Asia FX, the combination of a softer dollar and lower oil remains broadly supportive, although equity-flow differentiation continues to matter.
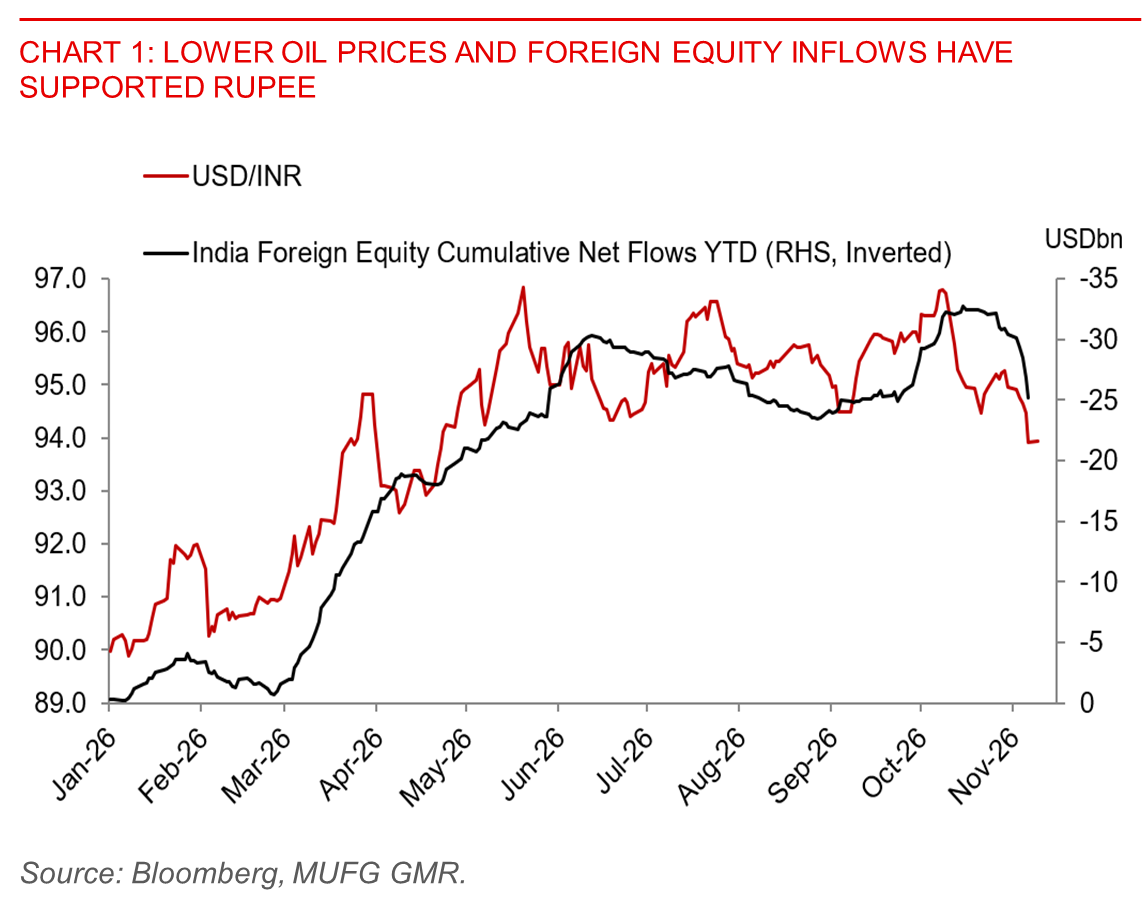
INR has emerged as a key beneficiary of the recent combination of lower oil prices and returning foreign equity inflows, with USD/INR falling below 94.00 to its lowest since April. Lower crude improves India’s terms of trade and eases pressure on the import bill and corporate margins. Meanwhile, foreign investors bought a net $5.2bn of Indian equities last week, with inflows accelerating towards the end of the week. This contrast with net foreign equity selling in South Korea and Taiwan.
Lower oil prices have also helped PHP strengthen late last week, briefly pushing USD/PHP below 63.00. But weaker domestic growth has limited that recovery. The pair rebounded towards 63.30 level after Q3 GDP slowed to 2.1%yoy, well below the 3.1% consensus. With inflation still elevated at 7.8%yoy, BSP faces a growth-inflation trade-off, leaving PHP less compelling than INR despite the common oil tailwind.
China’s inflation data highlighted rising factory costs rather than a broad recovery in domestic demand. October PPI accelerated to 5.7%yoy from 5.0%, while CPI slowed to 0.7%yoy and core inflation eased to 0.8%. Lower oil should provide some relief to manufacturers’ margins, but it does little to address weak final demand. Today’s trade data will therefore be important in assessing whether external demand remains strong enough to offset domestic weakness and provide support to CNY.
Taiwan’s October exports surged 58.9%yoy to a record $96.76bn, lifting the trade surplus to a record $27.9bn. Strong shipments underscore continued AI-related demand, even as investors reassess future spending and earnings. The external surplus remains fundamentally supportive for TWD, but persistent foreign equity outflows are limiting the near-term currency response.