
Key Points
We remain cautious on THB and maintain our USDTHB forecast of 34.00 by end-year. While Thailand is benefiting from the technology cycle, stronger electronics exports are insufficient to offset deteriorating terms of trade, weak growth, low rates, persistent portfolio outflows, and rising fiscal constraints.
Thailand's electronics boom is generating less FX support than headline export growth suggests. Thailand is a net importer of semiconductors required for electronics production. Rising chip prices and higher imported content have increased the electronics import bill, limiting the net electronics trade gains.
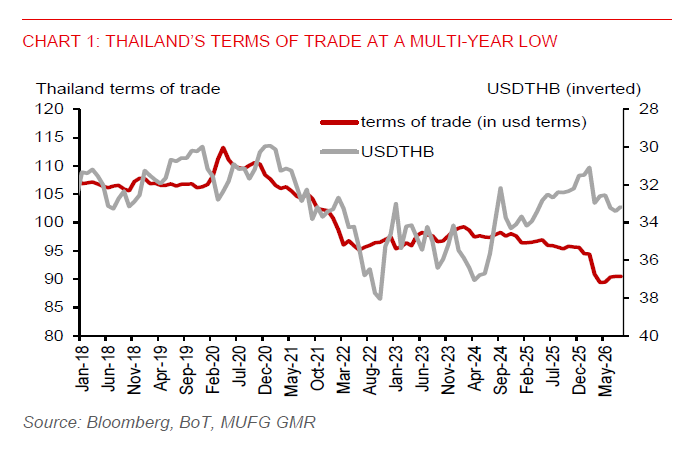
Thailand faces a broader commodity shock that is weighing on external balances. Terms of trade have fallen to a 27-year low, given higher prices of energy, metals, and intermediate goods.
The growth backdrop suggests scope for higher USDTHB. US growth remains resilient, while Thailand's GDP growth slowed to 1.9%yoy in Q2, with net exports posing a major drag on Thailand’s growth.
BOT policy rate remains at just 1.0% and is likely to stay there into early 2027, even as the Fed has raised rates and could tighten more in the coming months. Low BoT rates, along with baht overvaluations, persistent net foreign portfolio outflows, and limited fiscal capacity to cushion the oil shock impact, should keep THB under pressure.